
Published
- 04:00 am
Superscript, the business insurance challenger, has announced a new £8.5 million fundraise, led by existing investor, BHL Holdings, alongside investment from the Government's Future Fund, Seedcamp, Concentric and the London Co-Investment Fund.
An insurance provider for the new normal, Superscript delivers flexible insurance to match small businesses’ changing needs. The investment will help the company to double its UK workforce over the next 12 months and further invest in its proprietary technology. This will enable Superscript to ramp up its capabilities to support the new wave of small businesses that want and need flexibility in the way they manage their insurance.
The company has seen rapid growth in 2020. Throughout the COVID-19 pandemic, it’s offered payment breaks for customers and allowed businesses to add additional activities to their policy without extra fees. It’s also offered free medical malpractice cover for NHS health workers and insured clinical trials for COVID-19 tests.
Cameron Shearer, Co-Founder and CEO at Superscript, comments: “The current pandemic has hit small businesses a lot harder than their larger, established counterparts. The economy is experiencing significant turbulence right now and the business landscape will be unrecognisable in a year’s time. As a small business championing small businesses, this investment will speed up our ability to deliver bespoke insurance to underpin individual business needs. Helping businesses to not only weather this storm, but scale and thrive.”
Tom Wilson, Partner at Seedcamp, adds: “We’re pleased to be continuing our investment in Superscript’s growth. What first attracted us to invest in the insurtech is what still excites us today. Superscript has truly transformed the insurance experience for small businesses, with an attractive online user journey and bespoke, flexible cover options. It has proven its commitment to supporting its small business customers during the current pandemic and we’re excited to see its next stage of growth.”
This additional investment follows Superscript’s £8 million Series A funding in February 2020. Since launching in 2015, Superscript has turned the business insurance market on its head. Where incumbent insurance providers are unable to adapt their policies fast enough to keep up with changing business needs, through its proprietary technology Superscript has built a reputation for reacting quickly with personalised, affordable and flexible subscription-based cover that helps small businesses adapt to changing environments, to grow and scale.
- 09:00 am
Tata Consultancy Services (TCS) (BSE: 532540, NSE: TCS), a leading global IT services, consulting and business solutions organisation, announced that Volt, Australia's first neobank, has partnered with TCS to power Volt 2.0, its next-generation Banking as a Service (BaaS) platform.
Set to launch in 2021, Volt 2.0 will leverage TCS BaNCS™, a global payments solution, to expand the bank's offerings to include NPP, BPAY and DE, enabling full-service banking capabilities for all its customers. Volt will work closely with TCS to incorporate the real-time capabilities of TCS BaNCS for payments, along with API-based access to open banking components that are not dependent on traditional legacy structures. The end-to-end solution provides full back-end support, the flexibility to integrate leading technologies, and connect with an extended ecosystem to offer innovative new products and services.
“Volt’s unique platform technology places it at the forefront of Australian banks, and positions us well for incredible growth into the future,” said Steve Weston, Founder and CEO, Volt. “Operating in a highly regulated industry and the goal of becoming a market leader has led Volt to partner with exceptional global technology players like TCS whose commitment to continuing innovation will ensure Volt’s banking platform remains cutting-edge.”
"In this digital age, consumer expectations have soared, yet many banks are held back from innovation by lack of speed from legacy systems. TCS BaNCS is a cloud based solution for Australian banks seeking to collaborate with a range of partners and fintechs, to launch innovative products and deliver a superior customer experience," said Vikram Singh, Country Head, TCS Australia and New Zealand. "TCS is thrilled to be working with Volt to launch its next-generation payments digital banking platform Volt 2.0. Our deep knowledge and experience with payments technology will enable us to support Volt with a full-service, end-to-end solution leveraging TCS BaNCS."
TCS BaNCS for Payments offers multi-entity, currency, and country capabilities covering the complete value chain to Australian banks of all sizes. Its proven application architecture ensures anytime, anywhere digital access, scalability, resilience, high performance, and compliance.
- 04:00 am
Societe Generale - Forge, the digital capital markets platform of the Societe Generale Group, has selected ConsenSys to provide technology and services as part of its ongoing Central Bank Digital Currency (CBDC) pilot activities.
As part of this partnership, Societe Generale - Forge will continue to build upon its recent groundbreaking achievements such as the issuance of a 100 million Euro covered bond on blockchain in 2019, and the issuance of a 40 million Euro bond that was settled with a CBDC in 2020, a joint project with the Banque de France, the French central bank.
ConsenSys will provide technology and expertise to Societe Generale - Forge, focusing in particular on CBDC issuance and management, delivery versus payment, and cross-ledger interoperability.
Jean-Marc Stenger, CEO of Societe Generale - Forge, noted: “We are pleased to partner with ConsenSys, a company who is a key player in the development of distributed ledger technology globally and offers many of the infrastructure and development tools used by the blockchain community.”
Ken Timsit, Global Head of Enterprise Solutions at ConsenSys, noted: "We have high regard for the accomplishments of Societe Generale - Forge and are proud to be working with them. ConsenSys is committed to advances in the CBDC space and has assisted six central banks around the world on CBDC projects."
- 07:00 am
corfinancial, a leading provider of specialist software and services to the financial services sector, announced that it has won the coveted ‘Innovative Client Solution’ category at the WealthBriefing European Awards 2020 for its BITA Risk private client solution.
BITA Risk now brings practical ESG (Environmental, Social and Governance) management to the desktop for wealth managers.
Commenting on the firm’s triumph, Daryl Roxburgh, President and Global Head of BITA Risk, said: "We are delighted to have won this WealthBriefing award because it represents recognition of our innovative approach to managing ESG for private clients. Built on our client risk profiling and portfolio management modules, the BITA ESG Manager makes a difference to both client managers and clients alike in the world of ESG investing. Winning this award will add greatly to the confidence of our customers. Again, thanks to my great team. We could not have done this without them.”
Showcasing ‘best of breed’ providers in the global private banking, wealth management and trusted advisor communities, the WealthBriefing awards were designed to recognise companies, teams and individuals which the prestigious panel of judges deemed to have ‘demonstrated innovation and excellence’.
At last year’s event, BITA Risk secured the honours for ‘Best risk profiling solution’ (for the fifth year in a row) and was also awarded the ‘Best implementation of a technology solution’ award for its successful deployment on behalf of Quilter Cheviot.
- 05:00 am
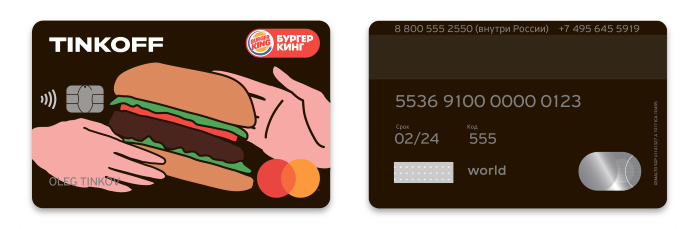
Tinkoff, Russia’s largest digital bank, has partnered with Burger King, a fast-food chain of restaurants to issue 10,000 limited-edition Tinkoff – Burger King co-branded debit cards with progressive cashback rewards. The two companies will also hold a social media contest for a chance to win a year's supply of Burger King food.
The launch of a Tinkoff – Burger King fast-food card, the first card of its kind in Russia, came about after the two companies engaged in some light-hearted banter on Twitter.
Tinkoff – Burger King cardholders will get progressive cashback rewards for a period of one year for spending money at Burger King. For spending of up to RUB 300 at a time, cardholders will receive a 5% cashback reward, while purchases for up to RUB 800 and higher will translate into cashback rewards of 10% and 15% respectively. After the first year, a cashback bonus of up to 30% will be awarded in accordance with Tinkoff Black debit card conditions. These terms will only apply to new Tinkoff debit cardholders.
Anyone is eligible to try their luck to win food for a year. To enter this contest, one must visit a dedicated landing page, generate a friendship-themed comic strip and share it on social media*. The winner will be chosen on 26 November 2020, using a random-number generator.
Alexander Bro, Head of Partnership and Loyalty Programmes at Tinkoff, said: “This Tinkoff – Burger King card is all about friendship, social media, and terrific, memorable collaborations. We often use social media platforms to communicate with other brands and even indulge in some good-natured trolling. So when Burger King first approached us with this offer, we thought they were just goofing around. But after they posted their letter to make it official and customer comments popped up, we realised this is a feasible idea after all.
It was obvious from the start that it had to be something special rather than your average debit card. So, we created this eye-catching design and added progressive cashback rewards of up to 15% for Burger King purchases. And as icing on the cake, we are giving active social media users a chance to win a year's food supply from Burger King.”
- 02:00 am
Today Mobiquity – a full-service digital transformation enabler that delivers compelling digital products and services that serve a purpose, by blending strategy, creative and engineering – launches a ‘Friction Report to benchmark UK & NL mobile banking apps,’ identifying ‘frictions’ within the UK digital banking app customer experience.
The study of 50,000+ UK customer banking app reviews within the Google Play Store and the App store shows the main ‘frictions’ across prominent UK retail banks.
One of the key issues was with login and password authentication. Nearly a third (30%) of digital banking app customers had issues logging into the app through their devices and 1 in 5 (20%) cited problems with username and password or password authentication.
Another ‘friction’ was customer service; nearly a quarter (24%) of users felt like they were waiting too long for customer support.
Almost a quarter (24%) cited problems with notifications. Either the wrong operation was performed, or no operation was performed at all when they clicked on the notification icon. 23% didn’t receive notifications for payments while 1 in 5 (20%) received too many notifications.
Meanwhile, over 1 in 5 (22%) were unhappy with the customer resolution, and over 1 in 10 (16%) customers cited that the support over chat was unavailable or not useful.
Commenting on the report, Matthew Williamson, Vice President of Global Financial Services, Mobiquity, said: “As the use of digital payments increases during the pandemic, so has mobile banking usage. The launch of Mobiquity’s Banking Friction Report helps banks to identify the ‘business frictions’ in their mobile banking experience to help align with evolving customer expectations.”
“An interesting observation that can be made is that most of the banking apps in the Google Play and App store score highly, but when you only account for reviews where people actually leave comments regarding an app feature, i.e. feature ratings, scores are quite low. This can be attributed to users no longer having to proactively go to the Google Play or App store to rate an app, but now are prompted to review an app while they are using it.”
“Nowadays, banks cannot risk treating their customers as passive observers, building products and features that do not take their feedback into consideration. Looping customer feedback into the decision-making process is key as banks get real-time information regarding which aspect of the app customers value the most, and where they find the most friction while interacting with the app.”
- 07:00 am
Fenergo, the leading provider of digital transformation, customer journey and client lifecycle management (CLM) solutions for financial institutions (FIs), today announced rapid adoption of its Cloud Managed Service, Fen-Cloud, powered by Amazon Web Services (AWS). 67% of all deployments of Fenergo’s CLM solution within financial institutions in 2020 will be on Fen-Cloud, as more financial institutions take advantage of cloud-based services to streamline processes, drive cost efficiencies and radically improve the customer experience. ICBC Standard Bank and Aviva Investors are among those signed up to leverage Fen-Cloud.
Michelle Calcutt, Head of Client Experience at Aviva Investors, said: “Developing our offering of digital tools in order to improve overall client experience (CX) is an area that we have placed great emphasis on over recent years. With Fen-Cloud, we will have the ability to quickly scale our CLM solutions according to changing customer demands while guaranteeing availability, no matter the location. We believe it will further enhance our CX credentials and add a layer of agility to the way we service our clients.”
Launched in 2019, Fen-Cloud is a cloud-based solution powered by AWS that delivers frictionless, end-to-end customer journeys and CLM on a single platform. By accessing Fenergo’s CLM offerings in the cloud, financial institutions can quickly get business solutions up and running while still maintaining the flexibility of customer-specific configuration, interfaces, and processes. Prior to 2020 many of Fenergo’s clients prioritized private on-premise solutions over cloud however the impact of COVID-19 has sparked rapid transformation across the entire financial services sector.
“Current market conditions and the impact of COVID-19 have compelled financial institutions to accelerate cloud adoption to take advantage of significant costs savings, enhanced reliability and proven scalability. The industry now recognizes that cloud-based solutions can help them safely and securely accelerate their digital transformation initiatives while focusing on their core business, which is evident based on the impressive client response to our Fen-Cloud service this year. We will continue to work closely with our global clients, as more financial institutions prioritise cloud, to help them improve customer experience, ensure compliance and streamline their CLM processes,” said Niall Twomey, Chief Technology Officer, Fenergo.
The platform enables financial institutions to automate and streamline multiple processes, from initial client onboarding to Know Your Customer (KYC), regulatory compliance and ongoing client and account maintenance – all in an easy-access and seamless cloud-based environment. Clients also have the option to deploy Fenergo’s CLM platform to their own cloud, maintaining full control of their environment.
- 09:00 am
A new study from Juniper Research has found that the number of digital identity apps in use will exceed 6.2 billion in 2025, from just over 1 billion in 2020. The research found that civic identity apps, where government-issued identities are held in an app, will account for almost 90% of digital identity apps installed globally in 2025; driven by the increasing use of civic identity in emerging markets and the lasting impact of the pandemic.
The report identified that the unprecedented shift to digital services during the pandemic across the world will stimulate rapid growth in civic identity; growing by 467% between 2020 and 2025, as robust onboarding and verification for digital services becomes vital.
Civic Apps to Overtake Digital Identity Card Use in 2023
The new research, Digital Identity: Technology Evolution, Regulatory Landscape & Forecasts 2020-2025 Report, found that civic identity apps will overtake the number of digital identity cards in use in 2023, with the number of apps in use 41% higher than cards by 2025. While digital identity cards are still growing, the research shows that apps are much easier to scale, and better support increased involvement in digital commerce, which will be critical to digital identity’s future use.
Research co-author Nick Maynard explains: ‘Civic identity apps have come into their own as a way to boost digital financial participation, particularly in emerging economies. Post-pandemic, this capability will be crucial in enabling increased digital engagement.’
Blockchain Important to Securing Identity Networks
The research found that blockchain will be important to the future of digital identity, with blockchain-based third-party digital identity apps accounting for 16% of all installed third-party identity apps in 2025. However, this is not necessarily the much-lauded self-sovereign model, where numerous parties such as banks, identity providers and mobile network operators work together to provide identity as a part of a wider network. Blockchain will be an effective way to secure federated access to data; injecting trust and transparency.
Juniper Research provides research and analytical services to the global hi-tech communications sector; providing consultancy, analyst reports and industry commentary.
For more insights, download the free whitepaper: https://www.juniperresearch.com/document-library/white-papers/why-digital-identity-is-critical-to-post-pandemic.
Find out more about our Digital Identity market research: https://www.juniperresearch.com/researchstore/fintech-payments/digital-identity-research-report.
- 09:00 am
Contour, the Singapore-based global trade finance network has today announced its partnership with CargoX, a blockchain platform for transferring documents and data including a certified electronic bill of lading solution. The news follows Contour’s transition to full production, with the network supporting electronic bills of lading as part of digital transformation of trade.
The partnership provides Contour customers another option for electronic bills of lading to be used in synchronisation with their Contour trade finance transaction. This will not only reduce the overreliance on paper documents that is common in the industry but also streamline trade processes, reducing time and improving communication.
Contour’s non-partisan network, powered by R3’s Corda blockchain technology, allows all banks, financial institutions, and corporates to improve access, communication, and transparency when conducting trade finance agreements.
CargoX’s blockchain-powered document transfer platform allows users to easily manage digital original documents, such as electronic bills of lading, and provides the tools for secure and instant transfers of those documents. The platform also provides transparency by including auditable histories of document ownership and changes.
Bills of lading have been an effective tool for trade finance due to their negotiability, allowing banks to finance goods still at sea without having to take control of an entire vessel. Digitally transforming these documents requires complicated digital registries with the support of shipping lines, banks, and corporations. Through achieving this process, bills of lading will become electronic and will no longer require ‘wet ink’ to be verified.
Carl Wegner, CEO at Contour, said: “Transforming trade finance can’t be achieved by a single company acting by itself – collaboration is central to building a trade finance network that is truly global. Bills of Lading can be a challenge for digital transformation, due to their complex nature. That is why it is a key focus for our partnerships to streamline this common pain point. Our work with CargoX marks an important milestone towards establishing an ecosystem of technology providers, banks and corporates that makes digital trade finance not just a reality, but a tangible, accessible option for all.”
Stefan Kukman, CEO and founder of CargoX, said: “The reliance on paper-based processes within international trade continues to be a challenge to improving the efficiency within the industry. Our service, enhanced through being a part of Contour’s network, allows trade to thrive and meet the demands of the modern world. Documents that used to travel for days or even weeks, with mediocre reliability and security, sometimes causing delays, loss, and damages, can now be delivered within minutes, and with extreme cryptographic security.”
- 08:00 am
Global technical body EMVCo has published a white paper which provides guidance to merchants, card issuers, acquirers and processors on how FIDO Authentication Data can be used in EMV® 3-D Secure (3DS) messages to reduce fraud and friction in the payment process for consumers.
EMV 3DS is a payment messaging protocol that enables consumers to authenticate themselves with their card issuer when making e-commerce purchases. The ‘Use of FIDO Data in 3DS Messages’ white paper focuses specifically on EMV payment use cases to demonstrate how FIDO Authentication Data can be leveraged to attest that merchant-initiated strong consumer authentication has taken place prior to an EMV 3DS transaction. This can reduce the need for issuers to authenticate cardholders for every transaction when shopping online and streamline processes for merchants, card issuers, acquirers and processors.
The ‘Use of FIDO Data in 3DS Messages’ white paper focuses on the newly defined FIDO attestation data set. Using this defined data set, merchants can deliver a structured set of data elements and present the card issuer with a consistent set of values for the same user or device (along with other data they would receive as part of an EMV 3DS transaction), reducing the need for repeated consumer authentication.
The white paper is an output of an ongoing collaboration between EMVCo and FIDO Alliance, focused on evaluating how FIDO Authentication standards can support EMV payment use cases to help reduce fraud globally, while maintaining and optimising the consumer experience. This includes efforts to define how EMV 3DS messages may be used to pass FIDO authenticator attestation data.
“Outlining exactly how the data can be used by card issuers to analyse merchant-initiated FIDO Authentication as part of their risk evaluations, can increase authorisation approval rates, streamline online checkout and reduce fraud,” comments Junya Tanaka, Chair of the EMVCo Executive Committee. “Analysing the use of FIDO data in EMV 3DS transactions is just the first step in the joint work efforts between EMVCo and FIDO Alliance, and we look forward to continued collaboration to enable consistency, convenience and additional security for EMV payment use cases and beyond.”
A complementary technical note from the FIDO Alliance, “FIDO Authentication and EMV 3-D Secure: Using FIDO for Payment Authentication” can be found on the FIDO Alliance website.
“This paper, as well as FIDO Alliance’s complementary technical note, provides essential information on how FIDO can be used alongside EMV 3DS to provide higher levels of security, enhanced user experiences, and better overall approval rates for e-commerce merchants,” said Christina Hulka, Executive Director and COO of the FIDO Alliance. “These papers are part of our longstanding relationship with EMVCo and our shared focus on providing answers to the questions we often receive on how our FIDO Alliance standards and EMVCo specifications can work together.”
The EMV 3DS white paper ‘Use of FIDO Data in 3DS Messages’ is available for free download from the EMVCo website. To find out more about EMV 3DS, view the resources on the EMVCo website.








