
Published
- 07:00 am

Appsbroker, the largest Google Cloud-only Managed Services Provider in EMEA published a comprehensive report of the health of Machine Learning in the UK private sector. Based on an extensive survey* amongst corporate UK IT leaders and decision makers, the report is the most comprehensive nationwide analysis of the state of Machine Learning (ML) in the UK. The insight the report provides is overwhelmingly positive, pointing to significant technical and commercial progression, while also underlining the challenges that must be overcome if ML is to be validated as one of the most transformative technologies for a generation.
Four key findings have emerged from the survey data:
- In the first instance, ML for UK business is no longer a hypothetical possibility; more companies now are validating ML or are using it in a live business context than the proportion of companies that are still assessing its merits and applicability. 69% of UK companies report that ML will be relevant to their organisation in the next 36 months; with exactly a quarter saying it is relevant right now and a further 17% within 12 months. For this reason, the report has dubbed ML as a ‘now thing’ for business, reflecting its advancing maturity and commercial potential.
- 39% of organisations surveyed are accelerating their ML initiatives in response to the Covid-19 pandemic. Only 11% indicated that they were in any way de-prioritising ML activities while for half of respondents, their ML plans have remained unchanged by the pandemic.
- While the investment levels businesses are prepared to commit to ML solutions are advancing, with 57% of companies expecting to invest more than £1m over the next 24 months, the report also contains a striking insight that the average UK company adopting ML expects to see a 10x return on investment. If realised, ML will become one of the most productive contributors to enterprise profitability of recent times.
The biggest barrier for delivering ML is the lack of in-house skills (cited by 44% of companies).
- The report disavows a conventional wisdom that ML is destined to devour jobs and replace human endeavour. In fact, twice as many businesses (40%) saw ML as enhancing human roles in business as those who regarded the technology as central to automation and cost-cutting (20%).
Despite the overwhelmingly positive outlook, the report does however issue a stark warning to business that ML must shift constructively from being the preserve of analysts and technicians to a position in the heart of the business. 68% of businesses reported that ML sat within their IT or Data capability, with only 16% of companies confirming that the capability had been more fully integrated into commercial operations. Many respondents identified a lack of understanding and leadership for ML from senior executives as a major potential stall point for the technology and something that needs to be overcome to ensure ML’s successful evolution as a primary toolset in UK businesses.
Henry Brown, Head of Data & Machine Learning at Appsbroker said, “The report paints a very positive picture of Machine Learning adoption and value across a diverse spectrum of enterprise Britain. Clearly this picture is changing, but it is good to note that many of the indicators point to growth, increasing maturity and an expectation of very positive value, which is consistent with the experience we have at Appsbroker as we guide businesses through the process of ML adoption.”
Industry sector highlights include:
- Financial Services organisations are the most likely to see ML as relevant to their business now or in the next 12 months (57%), followed by Healthcare (50%), Retail (48%) and Manufacturing and Industry (46%).
- The investment champions are undoubtedly Financial Services organisations - almost a quarter (24%) of firms confirmed an intent to spend more than £5m on ML in the next two years, followed by the Technology sector with 21% of companies looking to make a similar level of investment.
- Over half of Retail (57%) and Financial Services (52%) sector organisations are using ML for Fraud Detection to mitigate high financial risk and crime.
- The use of ML for customer segmentation and marketing is being deployed most among Professional Services organisations (65%) ahead of the Retail sector which ranks second (with 52%).
- A lack of in-house skills to embrace Machine Learning is most pronounced in the Healthcare sector (30%) and of least concern to the Manufacturing (13%) and Technology (14%) industries.
- Of the third-plus businesses choosing to accelerate their focus on ML due to the pandemic, Healthcare and Technology companies are the most prominent sectors with
45% of companies in both categories planning to accelerate their investment in ML.
The 2020/21 Appsbroker Machine Learning Insight Report which spans all aspects of ML progression in UK companies is available to download: https://info.appsbroker.com/lp/machine-learning-insight-report.
*About the survey
To produce the report, Appsbroker commissioned an independent online survey in August 2020 among 312 companies spanning 16 industry sectors in the UK with staff headcounts ranging from SMEs of less than 50 personnel to major enterprise businesses of 5,000 plus staff. 56% of the survey respondents were from organisations employing more than 500 staff. The respondents were IT leaders and IT professionals responsible for their organisation’s ML activities. Data was collected and analysed by size of organisation and industry. The full report can be downloaded from: https://info.appsbroker.com/lp/machine-learning-insight-report.
- 07:00 am
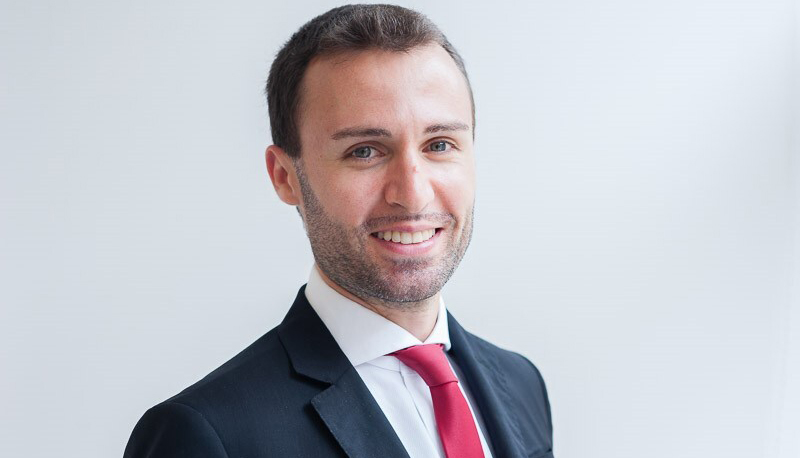
Dublin-based Reitigh Software, a leading provider of back office and regulatory solutions to financial services companies, has announced the hiring of a new senior project manager. This appointment spearheads a series of new hires as the company continues to invest and grow during lockdown.
Heading up the new hires is Giuseppe Schiavo. Originally from Italy, Giuseppe joins the company to manage Reitigh's digital transformation projects in the insurance sector. Giuseppe has vast experience as an actuarial project manager, having worked with the likes of Zurich in Milan, and Athora and Credit Agricole In Dublin.
The company has also announced the hiring of two new actuarial graduates from Dublin City University. Michelle Aw and Paddy Murphy join as junior consultants to bolster the company’s software implementation team. The pair join Reitigh's actuarial trainee programme as part of the firm's ongoing expansion in Dublin.
Giuseppe Schiavo, senior project manager at Reitigh Software, comments: “I’m delighted to be joining the Reitigh team to help this growing company reach new heights as a leader in the Dublin reg tech scene. It has never been a more important time to support financial services providers to deliver their digital transformation programmes.”
Reitigh Software is a software solutions company which works with financial services providers. The company marries technical and business expertise, setting itself apart with its distinct method of taking an actuarial approach to tackling digital transformation and software solutions.
Commenting on the new hires, Reitigh Software CEO, Brian Walsh, said: “These new hires bring further expertise, enriching our already strong team. Businesses need to evolve, and we are at the heart of enabling this transformation process.
“Dublin provides an ideal location and has been crucial to our success. Its status as a financial and tech hub and rich talent pool is attracting businesses and people from all over the world - creating a favourable business environment for Ireland’s thriving tech scene.”
- 07:00 am

The Center for Corporate Technologies (CCT), part of the Paymob Group, has become a Visa Ready Certified partner after developing Tap to Phone technology which can turn any Android smartphone into a contactless payment terminal.
This cost-effective technology enables businesses to accept contactless payments anywhere, any time via an app which they can download to their tablet or mobile phone. After registering and selecting their participating bank, the sellers can start accepting contactless payments in just a few minutes.
Co-founder and CEO of Paymob Technologies Ltd Kosta Du said: “This technology will revolutionise the whole payment acceptance industry and we’ve spent years and a vast amount of resources developing our Tap To Phone in-house solution.
“We’ve already been certified by Mastercard but becoming Visa Ready certified was another key milestone for us as it will enable us to partner with Visa clients to go to market and make our solutions available to sellers across the globe. It also gives sellers the peace of mind that our technology meets Visa’s high standards for functionality and security.”
Boris Federov, General Manager of CCT, added: “The COVID-19 pandemic has impacted small businesses by shifting them to remote work that has led to a significant increase in delivery services.
“Tap to Phone ensures the mobility and cost-efficiency which are crucial for SMEs during the pandemic. We have put lots of effort into creating a fully adaptable and secure solution, which will support SMEs and develop a cashless payment economy in the UK and beyond.
“We are thankful to the Visa team who supported and consulted us at all stages of the project development.”
CCT is currently certified by Visa and Mastercard for processing contactless transactions (non-PIN confirmed transactions) for which the limit in the UK is currently £45. However, the Paymob group has developed the existing non-PIN solution to empower it with revolutionary PIN-on-Glass technology. This means in the future sellers will be able to accept payments over £45 using only their smartphone.
Kosta said they want to be the first company to bring this Tap to Phone and PIN-on-Glass technology directly to sellers in the UK.
“We believe in our technology to such a degree that we chose one of the most advanced and competitive financial markets in the world, the UK, to launch our own payment company and win local businesses.
“Recently we became a registered Small Payment Institution (SPI) with the Financial Conduct Authority (FCA) and are planning to introduce a whole range of our technologies directly to UK merchants.”
To find out more about Paymob Technologies visit paymobtech.com.
They will also be exhibiting at Hong Kong Fintech Week (2nd to 6th November) and TechDay Online 2020 (17th to 19th November).
- 05:00 am
Financial services mobile platform DinarPAY has announced its partnership with global cloud communications provider Infobip, using its WhatsApp Business API and SMS offerings to deliver payments updates to thousands of customers across the globe.
Following an upsurge in government initiatives to drive the cashless economy and the COVID-19 pandemic continuing to push a rise in non-cash transactions, the mobile wallet market is expected to reach $7.58billion by 2027. DinarPAY enables consumers to pay with, transfer and top up funds in Dinar Currency via a dedicated mobile wallet. As market demand for its service continues to increase, relying solely on SMS updates to communicate with customers meant it was unable to reach certain handsets in certain countries.
DinarPAY chose Infobip as a technology partner to continue its SMS communications, but also employ WhatsApp as a channel given its broader reach. Through Infobip’s WhatsApp Business API and SMS, every customer across DinarPAY’s operations in Libya and Tunisia will receive instant notifications about account updates and transactions, as well as security reminders and two-factor authentication. Customers can also register for a DinarPAY account via WhatsApp, which offers a simpler alternative to SMS. The service is planned to launch in all Dinar Currency Dominated Markets in the next year.
Moad ALHASHMI, Sales & Marketing Director at DinarPAY, comments “The mobile wallet space is booming, so we have to meet this demand by ensuring we can connect with existing and new customers quickly and reliably, no matter where they are in the world. Our customers are already engaging with apps to use our wallet, so enabling communications via WhatsApp was a natural step. Pairing this with SMS, we now have full coverage when sending requests and notifications, which we’re delighted about.”
Another notable benefit of WhatsApp is the all-important verified tick to reassure customers. It also links through to DinarPAY’s website and contact page, enabling quick transition from app to website.
Noel Lavery, Sales Director at Infobip, said: “The number of people choosing mobile wallets to manage their payments has grown exponentially this year – and that’s only set to continue as the pandemic drives further necessity for contactless payments. We’re thrilled to be working with DinarPAY to ensure that, as its customer base grows, it can communicate with every single person over their preferred channel. You can’t place enough importance on simply being where your customers are, and that’s exactly what this partnership is about.”
- 05:00 am

Reliable information on investment restrictions, especially in the context of cross-border banking, has become a crucial factor for wealth managers in order to comply with mounting regulatory requirements. Avaloq, a global leader in digital banking solutions, is therefore integrating Investment Navigator’s advanced reg-tech (regulatory technology) offering into the newly launched Avaloq Wealth Platform. This white label solution includes suitability checks for the compliant distribution of investment products, covering all asset classes on ISIN level, as well as regulatory guidance on cross-border business activities.
Launched earlier this year, Avaloq Wealth enables banks and wealth managers to provide highly personalized investment advice and bespoke services to their clients, while reducing the time spent on preparing and analysing investment proposals. Cutting-edge API technology will connect the new platform with Investment Navigator’s Suitability Service to automatically assess regulatory, product-specific as well as tax requirements and restrictions.
Julian Köhler, co-founder and chairman of Investment Navigator, said: “We are very excited to partner with Avaloq. The default inclusion of the automated Investment Navigator suitability assessment into the Avaloq Wealth platform is a milestone for us and confirms once again that our services can constantly provide the highest degree of reliability for pre-trade checks.”
Alberto Rama, co-founder and CEO of Investment Navigator, said: “Unlike many other suitability service providers, Investment Navigator is truly independent. Our clients are not locked in and limited to the input of a specific rule-set provider, but we are rather giving them the freedom and flexibility that is needed to succeed over the long run in a rapidly changing world.”
Santiago Schuppisser, Avaloq Group Product Manager, Wealth Platform, said: “The Avaloq Wealth platform works across all asset classes, is powered by a high level of automation and offers an outstanding user experience for wealth managers and their clients. The seamless integration of Investment Navigator’s highly efficient solution exemplifies our holistic approach to simplifying digital banking, with the ultimate goal to democratize wealth management.”
- 06:00 am
Moorwand, a BIN sponsor and issuer that transforms compliance into an enabler of innovation, today announced that it has been selected by deVere Group to provide issuing services and BIN Sponsorship for Vault, its multi-currency Mastercard, across 14 different European markets.
deVere Vault, one of the digital banking products offered by the deVere Group, is a mobile app paired with a multi-currency Mastercard designed to meet the financial needs of international investors, expatriates and other globally-minded individuals.
Vault offers five wallets denominated in four currencies: EUR, GBP, USD and CHF. Users can also store and exchange funds in an additional 22 currencies. The Vault app allows funds to be moved by bank transfer and SWIFT as well as via instant Vault-to-Vault wallet transfers to other Vault users. Users can top-up their Vault wallet using bank transfer or debit card load.
Moorwand will issue deVere’s multi-currency card to four different user groups: existing Vault wallet users, deVere Group clients using its insurance and investment products, deVere Group employees, and deVere Group companies for salary payments. As the BIN Sponsor, Moorwand will also provide deVere with a single compliant connection to the Mastercard payment scheme for global transaction processing and settlement of cardholder funds.
“Fintech is the future of finance. New Brexit legislation, forcing UK banks to apply for new banking licenses to continue operating in the EU, will accelerate the trend towards digital-first e-money apps and firms which already have a pan-European presence,” said Nigel Green, CEO and founder of deVere Group. “The fact that Vault has already experienced a 67% jump in enquiries in Q3 2020 is a testament to this. To ensure we stay ahead of the curve, we need to continue to deliver a best-in-class service to our customers and our partnership with Moorwand is critical to that."
“The market is fast becoming congested with a plethora of digital banking apps and card offerings. To stand out and succeed, it’s no longer good enough to have a slick UX or nice functionality, you need to bring something different to the table,” said Luc Gueriane, Chief Commercial Officer at Moorwand. “Vault is different. It presents a unique solution to the unique challenges of globally minded individuals that live and work in a multi-currency environment. We look forward to working with deVere Group to ensure Vault continues to set industry standards.”
- 03:00 am
Icon Solutions, the specialist provider of world-class payment solutions and consultancy services, today announced a strategic investment from J.P. Morgan.
Icon Solutions is a leading global provider of payments technology and expertise, with a proven track record developing, implementing and running innovative, mission critical transaction banking solutions. Icon has also defined, architected and built IPF: a cloud native, highly cost-effective and collaborative payments platform that combines open source technology with light-weight integration.
“We’re excited to support Icon with this strategic investment as they look to continually build a simplified, collaborative payments ecosystem, driving emerging payments rails and innovation,” said Sara Castelhano, EMEA Head of Payments, Digital and Solutions, J.P. Morgan Wholesale Payments.
Icon will invest in its technology and geographic reach, helping new and existing customers do more with less and realise the potential of payments in the real-time, 24/7, open, data-driven world.
“Investment from J.P. Morgan is recognition of our achievements to date in supporting the evolution of the payments industry. Looking forward, it’s validation of our vision and ability to support ever-growing demand for technology transformation,” adds Tom Kelleher, Co-Founder and Commercial Director at Icon Solutions. “We will benefit greatly from the scale and insight of a global banking leader and one of the most visionary technology companies in the world, with the flexibility and independence to pursue our innovation and growth roadmap.
“The payments industry has woken up and realised that the money is in value-added services, not payments processing. The right approach to transforming technology estates reduces costs, increases resilience and supports innovation to deliver more value, while staying in full control. The investment with J. P. Morgan enables Icon to accelerate our plans and be perfectly positioned to help banks leverage this opportunity to drive new revenues and further develop existing business lines.”
Sara Castelhano will also join Icon’s Board of Advisors.
Learn more about how Icon Solutions is transforming payments.

James Booth
VP Head of Partnerships, EMEA at PPRO
Thanks to evolving consumer shopping behaviour, the rate of alternative payment adoption is continuing to move at lightspeed. see more
- 02:00 am

Fintech scale-up Pleo, which offers a simplified expense management tool and smart credit cards, today launches Pocket: a new way to track money owed between a company and its employees.
Pocket is a new feature that will sit within the Pleo app, covering a range of the most common occasions when employees spend their own cash on work-related purchases. The update aims to help businesses manage out-of-pocket expenses, where a worker pays for something with their own money – often to avoid overcomplicated processes.
Also covered by the feature are mileage claims, with Pleo digitising the outdated methods of tracking petrol costs for employees who travel for work. Likewise, expenses paid with ATM cash and the use of company cards for personal purchases will now be trackable with Pocket.
Rolling out to the 10,000+ customers across Europe who currently use Pleo’s cards and app to manage their expenses, Pocket will ensure that now when they log in, both employee and employer will be able to get a full overview of who owes what. And settling up is quick and easily - eliminating the friction and paperwork of traditional reimbursements.
Luke Richardson, Director of Brand and Communications at Pleo, says: “Pleo stands for the future of work, and there’s a strong connection between this and digitising the workforce, and ditching cash. However, Rome wasn’t built in a day, and we acknowledge that we need to provide tools that bridge the gap between digital and analogue work experiences. This is what we’re doing by launching Pocket, creating a set of features that can support businesses regardless of whether they’re dealing with online or offline payments.”
Pleo closed a $56M Series B round in May 2019 led by New York-based growth fund Stripes. Pleo cards are now used by over 10,000 customers across six European countries, with the company supported by strategic and technical partnerships with Mastercard, J.P. Morgan and Danske Bank.
- 02:00 am
Galileo Platforms, a specialist blockchain technology platform for the insurance industry, has become the first company to have its advanced blockchain platform used by an insurer as its core policy administration system with Singlife's launch in the Philippines.
Galileo Platforms joined with Singlife Philippines, a mobile-first life insurer from Singapore, and GCash, the largest e-wallet in the Philippines, to launch a platform for life insurance products. By using Galileo's scalable cloud-based blockchain technology, the new Singlife Philippines service can potentially reach a very large and mostly untapped insurance market.
The new blockchain-driven service is important because it will make affordable insurance available in one of the region's most under-insured countries. It does so at a time of growing concern in the Philippines about COVID-19 and rising demand for health insurance. The country has had more than 373,144 confirmed cases with over 7,053 related deaths.[1]
"We are very pleased to partner with Galileo Platforms to launch this radically new digital service to an important yet under-insured market in the Philippines," said Rien Hermans, President & CEO of Singlife Philippines. "Galileo technology is built for digital and for scale, offering easy low-cost solutions. That's perfect for Singlife and perfect for under-insured markets such as this one."
Galileo Platforms' patented blockchain technology enables insurers to connect with customers, distributors, and other key players in real-time using its digital platform, providing a shared source of truth to the industry participants, and eliminating the duplication of data. It provides a low-cost platform and flexible insurance products well suited for the Philippines, where insurance penetration is among the lowest in the region -- less than 1% when measured by gross written premiums as a percentage of per-capita GDP.[2]
"Many insurers are struggling to become digital, constrained by legacy processes and systems. We've re-thought the approach to managing policies, coverage and premiums to create flexible products and straight through processing giving the customer a complete digital experience," said Mark Wales, Chief Executive Officer at Galileo Platforms. "Our low-cost high-efficiency technology enables the whole life-cycle of insurance transactions to be completed at scale, without touching human hands."
Mr. Wales continued: "With Galileo, new business quotes, pricing, digital policy issuance, commissions and claims are completed in real-time with a single, secure "source of truth" that is agreed by all parties. It's an immutable point of reference that replaces the need for multiple copies of transactions, customer and policy records."
Galileo Platforms supports all types of retail insurance -- medical, life, and general. Its technology helps insurers and customers by removing the need for reconciliations and slow back-office processes, thereby reducing cost, complexity, and errors. Its vision is to make insurance more widely available to the mass of under-insured people across Asia.
"Two or three years ago, the idea of smallholder farmers in remote corners of the Philippines taking out insurance through blockchain technology would have seemed fanciful. But that is the reality now," said Mr. Wales, adding that medical insurance is usually one of the first types of insurance consumers buy. "Our digital technology makes insurance accessible and affordable for the mass market. What works on mobile phones across the Philippines can be replicated elsewhere in Asia and globally."
______________________
[1] John Hopkins University: https://coronavirus.jhu.edu/region/philippines (28 October 2020)








