
Published
- 01:00 am

Baker Hill, a leading provider of technology solutions for common loan origination, risk and relationship management, CECL compliance, and smart data analytics, announced that Farmers and Merchants Bank has chosen Baker Hill NextGen® Statement Spreading to support the bank’s continued growth.
From the beginning, Farmers and Merchants Bank has remained locally owned, operated and headquartered in Upperco, Maryland. A public banking institution founded in 1919, its independence has allowed them to provide customers with a team of local bank professionals who care deeply about its customers’ personal and business success.
With Baker Hill NextGen® Statement Spreading, Farmers and Merchants Bank can make credit decisions with complete confidence. Additionally, the bank will establish a consistent process for understanding and managing clients' credit risk through sound financial analysis. Featuring a wide range of formats and features to accommodate financial institutions’ needs for commercial lending, Baker Hill NextGen® Statement Spreading provides a reliable source of accurate comparative data. Farmers and Merchants Bank is also considering additional technologies within the Baker Hill NextGen®product suite.
“Baker Hill’s long-standing reputation for exceptional technology and service greatly impacted our decision,” said Christopher T. Oswald, Executive Vice President and Chief Operations Officer of Farmers and Merchants Bank. “We are looking forward to better reporting with quicker spreads thanks to all of the underlying features and functionality of Baker Hill NextGen®. Better reporting will lead to better service for our customers which is at the heart of everything we do.”
“At Baker Hill, we constantly strive to improve the quality and consistency of financial analysis available to financial institutions like Farmers and Merchants Bank,” said John M. Deignan, President and CEO of Baker Hill. “With Baker Hill NextGen® Statement Spreading, they will benefit from greater efficiencies within the lending process, helping drive growth and further position the bank as a leading community financial institution across Maryland.”
- 04:00 am

Softomotive, a leader in robotic process automation solutions, is pleased to announce a refreshed and enlarged RPA Academy. This is a state-of-the-art online learning portal offering comprehensive training in Softomotive’s RPA solutions. It makes it easy for students to join, learn and develop their RPA skills in a fast-moving market where such capabilities are in great demand by current and future employers. It is available athttp://academy.softomotive.com.
The Softomotive Academy is designed to improve the employability quotient of professionals and developers. It provides them with the opportunity to develop and deepen their RPA-focused skills which are in short supply at present as enterprises seek to accelerate their digitization efforts and improve productivity.
The e-learning platform provides everyone, including partners and customers, with an intuitive web-based interface that is accessible from any device (including mobile). Once logged in, learners can discover a rich catalogue of video-based tutorials that support on-demand and self-paced learning on Attended and Unattended Automation.
The Softomotive Academy features two different learning paths leading to either Certificates and Diplomas. Upon the successful completion of individual courses, learners will be awarded a Certificate which they can use to advance their careers. Professionals and developers that complete a structured learning program or have practical real-world experience of WinAutomation or ProcessRobot can earn a Diploma by passing a rigorous exam that proves their ability to develop effective and process automations.
“The relaunch of the enlarged Softomotive Academy supports our People 1st approach for RPA which is a new way to deploy RPA and helps to make the democratization of RPA a reality,” says Argyris Kaninis, Co-founder and Chief Operations Officer for Softomotive. “By giving our user community the depth and breadth of knowledge to fully leverage WinAutomation and ProcessRobot, we equip professionals and organizations to accelerate process automation discovery and development.”
The RPA Academy offers detailed, yet easy-to-follow individual courses helping learners to master RPA skills covering attended and unattended automation. Training ranges from a solid foundation on Robotic Desktop Automation (RDA) and enterprise RPA, to the development of complex process automation via scripting, and the advanced management and monitoring of software robots.
Each course consists of short online videos and rich documentation organized into sections. Each section concludes with an interactive quiz, which tests users’ knowledge and skills in RPA. Learners can watch RPA courses at any time tailored for specific roles, or can fully customize their learning experience based on their personal learning objectives.
The curriculum of the Softomotive Academy will be continuously updated, based on learners’ feedback and new product features being added, including new Attended and Unattended Automation content.
The online training site makes it easy to train employees in any organization, without the time and expense involved in face-to-face training. It helps teach the skills needed to implement RPA effectively in a company and to build a solid platform for future personal success while being a member of a rapidly growing global community of RPA professionals.
- 01:00 am

OneSpan, a global leader in software for trusted identities, e-signatures and secure transactions, today announced the launch of its open API, cloud-based Risk Analytics solution to help financial institutions stop fraud, including Account Takeover and New Account Fraud.
Account Takeover and New Account Fraud are the top two types of fraud challenging financial institutions and in the U.S. alone, ID fraud accounted for $16.8 billion dollars in fraud losses in 20171. Risk Analytics protects against these and other fraudulent activities across online and mobile channels using machine learning-based risk analysis, a form of artificial intelligence. This analysis identifies fraud in real time, predicts risk levels and takes immediate action when fraud is detected. The use of machine learning enables risk scoring to streamline processes, reduce operational costs tied to manual review and ultimately improve the user experience through fewer false positives.
“Even as criminals’ attacks on digital channels continue to escalate, financial institutions are under intense competitive pressure to reduce fraud and meet strict regulatory compliance requirements while growing their business,” said Aite Group’s Retail Banking and Payments Research Director, Julie Conroy. “Real-time fraud detection using advanced, machine learning-based risk analytics enables financial institutions to strengthen their security, lower fraud and achieve regulatory compliance.”
During a financial transaction, Risk Analytics collects and analyzes data from a variety of sources, including devices, user behavior, transactions, digital channels and business applications. The solution then scores the user, device and transaction data, and determines the risk associated with that transaction. Risk Analytics is then able to take immediate action to either allow, review or block the transaction, based on intelligent workflows incorporating bank-defined security policies and rules.
“Wherever money and data flows, fraud will certainly follow,” said OneSpan CEO, Scott Clements. “While stopping fraud has become increasingly challenging because today’s threats keep evolving, it’s critical for financial institutions to take proactive measures and a layered approach to security to monitor, detect and block fraudulent transactions from happening before they occur, ensuring the best possible experience for the user.”
OneSpan’s Risk Analytics is available now. Find out more at www.onespan.com/security-products/risk-analytics.
- 09:00 am

Worldpay, Inc. (NYSE: WP; LSE: WPY), a leading global payments technology provider, and Sage Pay, part of Sage Group (FTSE: SGE), a market leader in cloud business management solutions, have today announced a partnership that broadens the range of card payment solutions available to businesses.
This partnership will open-up the opportunity for businesses of all sizes to deliver cost effective, simple and transparent card payments solutions. Furthermore, the collaboration will help reduce time-to-trade for businesses, a vital pre-cursor for success.
Currently, 17% of all invoices from small and medium businesses are paid late in the UK and Ireland*. The UK currently has the highest proportion of invoices that are paid late, with 9% written off as bad debt. The acceptance of card payments helps businesses get paid on time.
Worldpay is a global leader in payments processing technology and solutions, enabling merchants to accept a vast array of payment types, across multiple channels, almost anywhere in the world. Processing over 10,000 transactions per minute, the company can service merchants 24/7 all around the world, from sole traders who process small volumes through to large corporates processing millions of transactions, daily.
Steve Newton, EVP, UK and Europe, Worldpay, said: “Worldpay is one of Europe's largest payments processors and we are delighted to be partnering with Sage to champion the needs of growing businesses across the UK and Ireland. By partnering with such an established market leader in business technology solutions, where we are unlocking the power of digital payments for businesses of all sizes.”
Seamus Smith, EVP, Payments and Banking, Sage, said: “We know it takes on average between 7 – 15 days for businesses to chase payments every year – time they could spend growing their business.
“By increasing the opportunities for businesses to accept card payments, their customers can quickly pay by card (or other digital payment methods of their choice), which helps reduce the businesses’ admin burden and the time it takes to chase them up.”
*Research: ‘The Domino Effect: the impact of late payments’; Sage, 2017.
- 06:00 am

The Private Banking arm of Emirates NBD, a leading bank in the region, recently introduced The LaunchPad, a homegrown concept that identifies the region's brightest start-up ideas and connects them with world-class angel and early-stage investors.
The LaunchPad is the first bank-facilitated deals platform of its kind in the region, offering entrepreneurs the opportunity to showcase their businesses and pitch for seed or growth capital to a panel of international investors and venture capitalists. Held under the theme of ‘Inspiring What’s Next,’ the initiative aims to introduce Emirates NBD Private Banking clients to alternative options of diversifying their investment portfolios.
Commenting on the initiative, Suvo Sarkar, Senior Executive Vice President, Head of Retail Banking and Wealth Management, Emirates NBD said, “‘Setting up of The LaunchPad platform highlights our commitment to nurturing budding entrepreneurs in the region by facilitating access to world-class investors, as well as showcasing exciting new avenues for investment to our clients.”
The inaugural edition of The LaunchPad saw a challenging race between 25 start-ups and early stage companies, with five businesses shortlisted to pitch their ideas to three international investors at an event in Dubai, attended by Emirates NBD Private Banking clients.
Investors included:
- Virginia Cha, a professor of innovation and entrepreneurship with multiple appointments across leading universities in Singapore as well as an active angel investor in early-stage start-ups. In her 37-year career, Cha founded, co-founded and ran several venture-funded hi-tech companies in Singapore and China.
- Bill Reichert, the Managing Director and Co-Founder of Garage Technology Ventures, a Silicon Valley-based seed and early stage venture capital firm. He brings with him 30+ years of experience as investor, entrepreneur and operating executive.
- Matt Penneycard, a venture capitalist for 16 years. Until recently he ran one of the UK’s most active seed-stage tech funds and he is now a co-Managing Partner of Ada Ventures, a pre-seed fund focused on tech ventures.
The five shortlisted business included:
- Seez, a mobile app aimed at using AI tech to fully automate car search and buying
- StreetLifeDXB, an on-demand travel assistant app
- Sippy, a prepaid subscription service to coffee drinkers from a network of independent coffee shops in the UAE.
- Wavenote, a vocal social networking app that lets you record, listen and share audio
- Jaib, a payment method that provides unbanked online shoppers with instant credit facility.
- 08:00 am
More than three-quarters (80%) of bankers believe challenger banks are an increased threat to their business, while almost one-third (30%) believe they will be the single most disruptive threat in 2019. The survey, commissioned by fintech provider Fraedom, found that in response the challenger bank threat, bankers expect their organisations to invest heavily in updating legacy systems (44%) and new technology (26%) in 2019.
“With challenger banks setting themselves apart by offering innovative technology platforms, commercial banks are now realising they must invest in key areas in order to counter this threat. This was also echoed by our survey which found other disruptive influences in 2019 to be digitalisation (36%) and consumerisation of technology (36%)” said Kyle Ferguson, CEO, Fraedom.
This comes as almost half (46%) of respondents perceive legacy systems to be the biggest barriers to the growth of commercial banks, while 32% cite it’s the pressure to save money.
With investing in new technology high on the agenda for commercial banks, the survey found that over half (53%) of respondents believe AI and Machine Learning will be the technologies to have the biggest impact on commercial banking in 2019.
“It is clear to see that challenger banks are a disruptive force within the sector. Through the use of innovative technology, these banks have plugged a gap left by established retail banks, and are acting as a stark warning to banks within the commercial space which remains open to similar disruption,” added Ferguson. “If commercial banks are to compete, they must become more agile and adopt new technology platforms suited to changing needs of businesses, or risk being left behind.”
- 09:00 am
Financial services aimed at the over 55 market is often ‘grey, big, ugly and uninspiring’. Considering that those who are 55 years of age and older, control the vast majority of the world’s wealth and investible assets, they are a market that it would be foolish to ignore.
Many in the over 55 demographic are thinking about retirement. And the concept of retirement, as we know it, is changing. Living longer and healthier lives means not just more time for leisure but, increasingly, a longer (and varied) working life. A hard stop to work, somewhere around 65 years old, is simply not the reality for many people.
According to a recent study conducted by the Royal London (and based on HMRC data) the number of taxpayers aged 65 and over nearly doubled from 3.32 million in 1995 to 1996 to 6.49 million in 2015 to 2016. This means that more than a quarter of taxpaying pensioners are still in paid work. Pensions and later life financial planning play an important role in thinking about retirement (in all its fast-evolving configurations). It requires some serious and consequential decision-making. This is a market that is ripe and ready for an influx of innovative solutions.
Yet they are often ignored by innovators. A fact made clear by players in this market in the article How Fintech Is Disrupting Retirement published by the Warton School of Management last year.
But too often, Silicon Valley is not innovating with the older group in mind. Most of the products designed for 50 and up are “grey, big and they’re ugly and not inspiring,” according to Rhian Horgan, founder and CEO of Kindur, a retirement planning startup. One reason is “anyone over 50 is grouped together,” she said, when digital skills can vary widely between someone who is 50 and a senior at 90. “Baby Boomers know how to use computers and mobile phones but use them very differently than young folks.”
The UK introduced pension reforms in 2015, giving more freedom to consumers with regards to accessing their pensions savings. It was hoped this would act as a catalyst to innovation in the pensions market. The reforms did offer a wide range of potential choices to retirees ranging from how they took their pension income and invested the proceeds. Providing new products and services to large a pool of consumers, potentially flush with pensions cash, should have been an innovators dream.
The reality, however, has not lived up to that hope. The FCA’s interim findings of its review of pension freedoms, published in July of last year, found that there was simply not enough innovation in the retirement income market.
No doubt there are many reasons. There has been a whole host of regulatory initiatives impacting key aspects of provision. In addition, there has not been enough time or effort spent on educating and informing consumers nor for innovative new products to come to the market.
As we age, a wide variety of massive life decisions can have a significant impact on the quality of life in retirement. Decisions that require information and often difficult to wrap one’s head around assumptions about future health and longevity.
There is a complexity to pensions, and retirement overall, that requires a more fulsome approach. As with the non-retired life, a suite of financial products and services is required but in the context of evolving needs and, ultimately, the end of life to consider. Factor in socio-economic and gender differences and the complexity grows. A one size fits all approach simply won’t deliver the best outcomes
Large pools of investible assets, a greater need for personalisation, a need to support complex decision making and knowledge of the technologies that can underpin all of these goals…this is a challenge and opportunity that should be turning heads and minds across our community to the over 55’s. As we convene our community of innovators thinkers and providers, we will look to explore the changing landscape and understanding of ‘retirement’ and kick-start more innovation for this ready-made market.
- 03:00 am
It is generally accepted that for insurance to match the majority of customer-facing industries in terms of customer service, omnichannel engagement and personalized products, insurers must undertake a series of radical organizational and technological transformations.
Of course, to effectively acquire customers, offer them personalized products and seamless service requires careful analysis of data from which insights can be drawn. However, the chief challenge to insurers’ effective use of analytics is data quality, or lack thereof (Insurance Nexus’ Advanced Analytics and AI survey).
This may, in part, be due to the evolving nature of data and our understanding of how its changing qualities impact how we use it. It stands to reason that the nature of data should alter over time; as technology changes and different data sources emerge, so the characteristics of data evolve. Despite this, while discussions about the proliferation of data are commonplace, considerations about the changing nature of data itself are less so.
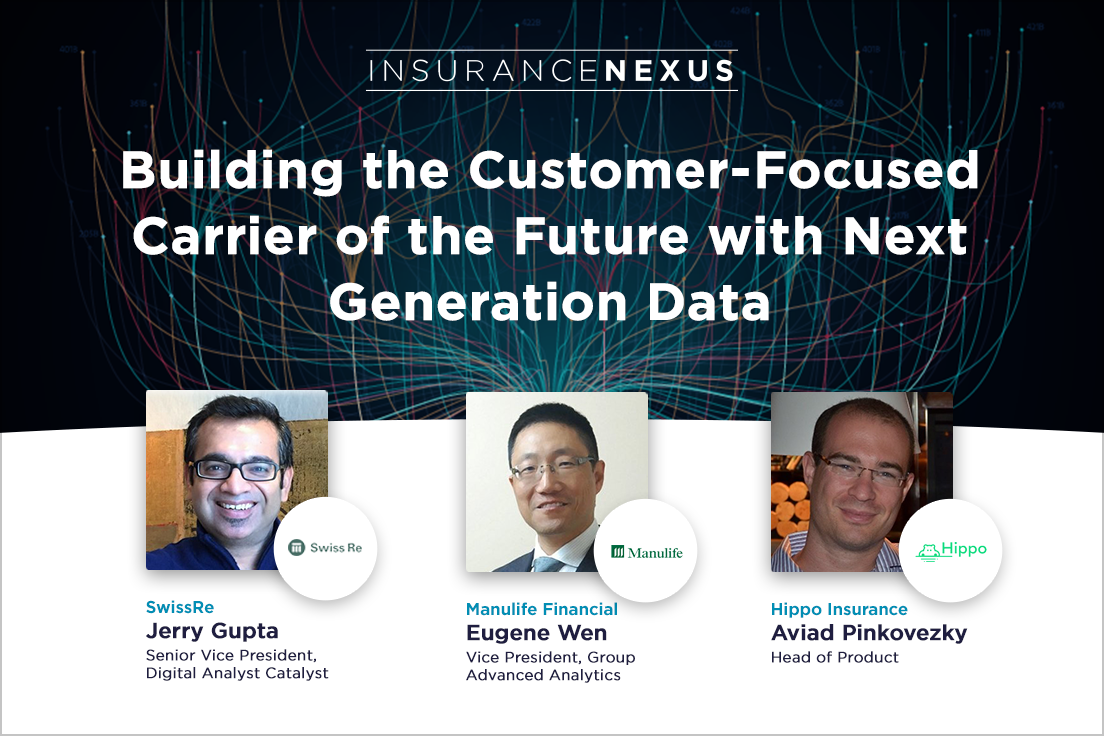
Insurance Nexus spoke to three insurance data experts, Aviad Pinkovezky (Head of Product, Hippo Insurance), Jerry Gupta (Director of Group Strategy, Swiss Re Management (US) Corporation) and Eugene Wen (Vice President, Group Advanced Analytics, Manulife), for their perspectives on what each generation of data mean for insurance today, and how subsequent generations will influence insurance tomorrow.
Read the whitepaper today for insights into:
- Defining the different generations of data: from proprietary, third party, and IoT data, understanding how data evolves on a generational basis can help map strategy for future-focused insurers
- The Next Generation: more data isn’t just more data. Understanding how its changing characteristics will impact the fundamental nature of insurance itself is crucial
- Why ethics and caution are essential: trust is hard won and easily lost. A data breach, intentional or otherwise, can have catastrophic consequences
- The conditions required to maximize data value: from acquiring the right talent, to data architecture and organizational structure, the right circumstances must be in place for effective data-integration
Read this exclusive whitepaper today

Ian Bradbury
CTO of Financial Services at Fujitsu UK
Even as we move towards a cashless society, ATMs still play an important role in the financial life of Brits across the country, and reduced access might have unpredictable consequences for consume see more
- 08:00 am
PrePay Solutions (PPS), subsidiary of Edenred the world’s leading corporate payments organisation, is supporting Countingup to become the first mobile bank in the UK to offer invoicing and expense tools.
First launched in 2018, the revolutionary PPS-powered mobile app initially allowed small businesses to do banking, bookkeeping and stay on top of their taxes. Building on this comprehensive product offering, the new invoicing and expense tracking tools are tailored to fit the specific needs of the UK’s small businesses.
PrePay Solutions played a key role in the creation of the Countingup’s services and its new additions by creating, operating and managing the infrastructure. The technical platform was designed to streamline accounting services, as well as provide business owners with a snapshot of their financial health.
On a continuous mission to make the running of businesses smoother, Countingup is already popular across the UK. Since launching, it has processed over £100 million transactions and received £8 million in customer deposits for over 8,000 small business customers. The new offering will make Countingup even more appealing to business owners.
Backed by leading venture capital firms, Forward Partners, Frontline Ventures, Jam Jar Investments and partnered with PPS, the company is continuing to develop innovative accounting solutions. As such, plans are already in place to launch to grow the app with additional billing and VAT filing tools, as well as enabling multi-user access – PPS will power the app as it develops.
Ray Brash, CEO at PrePay Solutions commented: “At PrePay Solutions we are always on the lookout to support innovative technology companies that are providing tools to help UK businesses run more smoothly. We are thrilled to power the Countingup app as it provides the UK with streamlined accounting tools for the first time. The company has proved itself to be incredibly forward-thinking and we can’t wait to power their upcoming product offerings.”
Tim Fouracre, CEO and founder at Countingup, commented: “We are delighted to be working with PPS’ team of experts – who have helped strengthen our incredibly comprehensive range of accounting features. Our app enables business owners to use one streamlined software for most of their accounting needs – no longer needing to juggle several methods. We have exciting plans on the horizon and look forward to continuing work with PPS.”








