
Published
- 09:00 am

ION’s WAM solution has been successfully deployed across three regions to optimize EMS’s manganese material flows to its global customers
ION Commodities, a global provider of commodities trading and risk management solutions, announces the successful implementation of ION Commodities WAM Demand Planning and WAM Enterprise Planning solutions at Eramet Marketing Services (EMS).
EMS, a global mining and metallurgy group headquartered in Paris, required an enterprise solution to optimize demand and supply plans and synchronize purchasing, distribution, manufacturing, and delivery to customers. ION’s WAM solution now enables EMS to forecast sales more accurately and minimize delivery costs across its global manganese supply network, while maintaining optimal finished, intermediate, and raw material inventory positions despite market volatility.
ION’s WAM supply chain optimization solution provides a centralized planning system of record. It enables the creation of optimized plans and schedules, provides visibility into global inventories and trades, and generates predictive analytics to guide operations and maximize profitability.
“ION’s WAM solution will improve coordination of our global manganese operations related to ore extraction, transportation, and refining, along with alloy manufacturing and the distribution of finished products to our 1,500 customers worldwide,” said Grégoire Castagna, Value Chain Manager, Eramet.
“We are delighted with the successful implementation of WAM for EMS. This is the latest expansion of ION’s presence in the metals and mining sector globally, providing supply chain management solutions and helping businesses take advantage of new opportunities in changing markets,” said ION Corporates CEO Richard Grossi. “WAM will provide EMS with better visibility of its global manganese operations and performance of its supply chain, enabling it to seamlessly execute its role within Eramet as the vital link between the mining teams, the processing plants, and the customers.”
- 04:00 am
Open Banking Expo, the leading global community of Open Banking and open finance executives responsible for digital transformation across financial services, will bring the Open Banking and open finance industry in Europe and the UK face to face next Thursday, 4 November.
This year’s event has drawn some of the biggest names from across the breadth of financial services, with the speaker line-up including over 80 leaders in banking and fintech.
The day will kick off on the main stage with a forward-looking panel discussion exploring what is required to build a thriving open finance ecosystem, followed by Marion King, Director of Payments, NatWest Group, who will share her vision for what a payments strategy should look like by 2030.
Other highlights include Dr Ruth Wandhöfer on Stage 2 who will explore the future digital ecosystem and dive into topics like blockchain, distributed ledger technology (DLT) and central bank digital currencies (CBDCs) as potential building blocks of the future economy.
Also on Stage 2, sponsored by European fintech Tink, James Shafe, Head of Consumer and Retail Policy Department, the Financial Conduct Authority, will share the learnings from the Call for Input on Open Finance, which was published earlier this year.
On Stage 3, sponsored by London-based fintech Volt, UK Open Banking Lead at Goldman Sachs Winston Pearson will look into the potential of Open Banking to transform corporate treasury.
And on the fourth, which will be the Payments Stage sponsored by Bottomline Technologies, Chris Hemsley, Managing Director, Payment Systems Regulator, will share about the importance of developing digital payments with people and businesses in mind.
The guests will also hear from the newly appointed Open Banking Implementation Entity (OBIE) Chair, Charlotte Crosswell. As part of the closing keynote on the main stage, she will share her vision for OBIE and the future of open banking in the UK and beyond.
In addition to the rich content, Expo attendees will have plenty of opportunities for networking across a number of spaces, including the Networking Lounge hosted by Klarna, a café hosted by Yapily and barista coffee from Oolys. The event will culminate in the After Party hosted by Equifax.
With Token as its headline sponsor, the event promises to be the biggest industry reunion in over 18 months.
Adam Cox, co-founder of Open Banking Expo, said: “We can’t wait to welcome everyone at the Business Design Centre in London next week. We really worked hard to bring the best speakers and content across four event stages as part of this year’s event. The tickets have been selling fast which only shows how much the industry is looking forward to a face-to-face conversation.”
The latest programme is available on the event’s website.
Hundreds of C-level and senior-level delegates from across the financial services sector are expected to attend and exchange ideas and insights on the future of Open Banking, its governance and roadmap in Europe and the UK.
- 03:00 am
The additional funds extend Ondato’s seed round to a total of €5.6M, spurred by 4x growth since January
Compliance-as-a-Service startup Ondato has closed a €3.6M seed extension round led by OTB Ventures, LitCapital and Startup Wise Guys, bringing the total amount raised by Ondato so far to €5.6M. The seed extension sees the addition of experienced institutional investors LitCapital, who will provide strategic support as the startup continues to scale rapidly. The funds will be used to expand the team with a focus on high-calibre hires to support new market expansion, product development and operations.
With the explosion of digital banking and the digitisation of other financial services, customer identification and other aspects of KYC compliance have become unavoidable. However, most financial services companies see customer identification as a burden to overcome and quickly tick off a checklist. On the other hand, a smooth onboarding experience can make all the difference to new and existing customers.
This is where Ondato comes in. The company aims to not only provide the highest standard compliance tools, but help turn compliance into a competitive advantage for its clients. To do so, it offers a multi-functional compliance management suite designed specifically for financial institutions, offering integrated solutions for identity verification, data monitoring, screening, due diligence, risk scoring, and case management, all under a single software as a service (SaaS) model.
“We have grown 4X in the last 10 months and substantially expanded our team size and range of services. The data shows us that there is a need to both deepen and widen the use of KYC services. The additional funds will help us sustain a pace of growth that has beaten our expectations. We are also excited to welcome LitCapital on board to enter our next expansion stage. With their backing as experienced institutional investors, we are well positioned for continued growth and a strong Series A in 2022,” said Liudas Kanapienis, co-founder and CEO of Ondato.
“Ondato has identified a unique opportunity in a booming market and successfully built and marketed a product that goes beyond what any other KYC provider has – a truly comprehensive compliance management software making use of the latest technology. We are impressed with what Liudas and his team achieved during such a short period of time, and we are extremely happy to be able to work alongside them,” commented Šarūnas Šiugžda, Founder and Managing Partner at LitCapital, who is also joining Ondato as a Board Member.
Founded in 2016, Ondato has developed software enabling banking institutions to onboard new clients and manage other compliance functions. The company serves over 200 clients in more than 30 countries operating in fintech, banking, insurance, telecommunications, and other related sectors.
Ondato aims to use the additional backing to further focus on product development and customer acquisition in Europe and the US ahead of a planned Series A in early 2022.
- 09:00 am
Renaissance Insurance handles hundreds of insured events every day, and one of the essential elements of this process is calculating damages to vehicles. Up until now, only experts – Company employees or contractors making independent assessments – were involved in calculating damages. This ensured that the calculations were of high quality, but there were always certain limitations when it came to the speed and cost of making these calculations.
After conducting large-scale and detailed testing, carried out on hundreds cases, the Company decided to begin using an AI service provided by Mains Lab to calculate damages in its commercial operations. The technology is based on computer vision: which parts of the vehicle have suffered damage and the degree of damage are determined; hidden damages and the need to remove or install additional parts for repairs are predicted; catalogue numbers are updated; the vehicle identification number (VIN) is identified; odometer readings and information from registration documents are discerned; the amount of necessary repairs is determined; and a calculation is prepared. The incorporation of this technology will further improve the level of customer service by speeding up the claims process and improving operating efficiency.
“Innovative solutions will have a significant impact on business in the current climate. At the same time, we are changing the essence of the customer experience, as we are reducing the amount time customers have to wait for payment or for their car to be repaired”, says Vladimir Tarasov, Vice President of Renaissance Insurance.
Sergey Khudyakov, one of the co-founders of Mains Lab, said: “Our colleagues from Renaissance Insurance have very stringent requirements when it comes to the quality of the claims process. As our solution was being tested over several months, we got constant feedback from our colleagues, which enabled us to quickly refine the technology for use by the insurance company. I am confident that, if a car owner has an accident, our joint product will make their life a little bit easier.”
- 02:00 am
- UK Finance departments slow to adopt digital transformation despite acknowledging that manual processes lead to critical errors -
Research into UK SME finance and accounting departments has exposed the sheer lack of digital tools currently used, with just one in five (20%) having adopted the use of automated invoice processing and 39% are still using Excel spreadsheets and manual processes.
The research of over 200 UK finance and accounts payable professionals also revealed that over a third (35%) haven’t automated their accounting processes because they use multiple formats for invoices and don’t want multiple software systems.
This reluctance to adopt automation is, despite acknowledging the faults of manual accounting processes, such as being too time consuming (43%), can result in late payments (29%) and even the loss of financial documents in the past (27%). Others recognised the drawbacks of manual processing as an inability to operate efficiently with the shift to remote working (27%) and the reason for making critical human and admin errors (26%).
Francois Lacas, Deputy Chief of Operations at Purchase to Pay software provider, Yooz, says, “UK businesses are facing many tough challenges at the moment as they, like many businesses across the world, begin their recovery from the pandemic. Add in the challenges brought about by Brexit and it becomes clear that they need to get smart when it comes to business and finance operations. You could make a strong argument that the need for streamlined processes and financial automation has never been more critical for business prosperity as it is now.”
The independent research, commissioned by Yooz, also found that a quarter (25%) of UK finance leaders say it takes their business anywhere between one and seven days to process a supplier invoice. According to Government figures there are six million SMEs in the UK, meaning that 1.5 million UK businesses are taking longer than necessary to process supplier invoices.
Lacas continues, “By automating financial processing, not only are you saving financial resources, but your employee resources, too. Your finance team is critical to your business's success. When automating these processes, all of the work is done automatically for your team.”
A further 6% of companies, which equates to 360,000, admitted to taking more than seven days to process supplier invoices. When you consider that SMEs account for three fifths of the UK employment and around half of the UKs annual turnover, can they afford to be reliant on slow invoice processing.
Lacas concludes, “Now is the time for businesses to seize the opportunity to embrace new technology and a better way of working.”
- 05:00 am
A leading US personal finance platform selects Temenos technology to power its Invest, Borrow and Spend products for its hundreds of thousands of clients Temenos (SIX: TEMN), the banking software company, today announced that M1 Finance, the Finance Super App™, has selected The Temenos Banking Cloud. With Temenos, and through collaboration with a third-party bank, M1 will broaden its suite of financial services to include banking, starting with deposits and payments and eventually expanding into lending.
M1’s mission is to empower financial well-being by creating one of the world’s best platforms for long-term money management. The company has created a suite of financial tools enabling clients to Invest, Borrow and Spend. M1 takes the complexity out of investing, making wealth creation easy while promoting healthy financial habits. In July 2021, M1 completed a round of Series E funding that propelled it to unicorn status with a valuation of $1.45 billion.
Economic uncertainty in the face of the global pandemic has led to an increased appetite to build wealth, with ~20% of market activity now coming from retail investors.[1] Over the past year and a half, M1 has more than doubled its client base and quintupled its assets under management to $5 billion. For its next stage of growth, M1 is seeking to redefine financial services and move into the banking industry through collaborative efforts.
To do this, it needed a cloud platform that could connect to M1’s front-end, scale massively, and move quickly as M1’s strategy evolves. Temenos’ open cloud banking platform will serve as the foundation for M1 to launch banking services, while creating hyper-efficient cost structures. Using Temenos Model Bank methodology and the pre-configurations for Temenos Transact and Payments, M1 will be able to quickly roll out new products and features. The increased efficiency, agility, and flexibility will enable M1 to deliver seamless, outstanding client experiences.
Brian Barnes, Founder & CEO, M1 Finance, said: “We believe that our clients should have total choice, control and transparency over how they achieve their personal and financial goals. We are passionate about helping people from all walks of life to grow their wealth and build their financial future. To fulfill this promise, we need technology that is fast, open, and scalable as we continue to grow our products and client base. This partnership will help us build a stronger, faster, more secure technology stack that makes our clients’ experience on M1 even better. Temenos’ open cloud banking platform will enable us to support massive growth and make wealth creation accessible to every American.”
Jacqueline White, President – Americas, Temenos, said: “At Temenos, we have a vision to power a world of banking that opens up opportunities for be people to achieve their ambitions. We are delighted that M1 will use the Temenos Banking Cloud to deliver on its mission to help its clients take control of their financial future and build their wealth. Temenos’ open cloud technology will pave the way for innovation, empowering M1 to create collaborative products that challenge how we think of banking, delivering a seamless experience and banking services that work for its clients wherever they are in their journey.”
- 07:00 am
2.2 billion people around the world have visual impairments
Unique notches on the Touch Card’s short side allow the person to distinguish it between a credit, debit or prepaid card
Mastercard extends its commitment to inclusivity by introducing a new accessible card standard for blind and partially sighted people, called the Touch Card. There are few effective ways for the visually impaired to quickly determine whether they're holding a credit, debit or prepaid card, particularly as more cards move to flat designs without embossed name and numbers. Mastercard is addressing this challenge with a simple yet effective innovation.
“The Touch Card will provide a greater sense of security, inclusivity and independence to the 2.2 billion people around the world with visual impairments,“ says Raja Rajamannar, chief marketing and communications officer. “For the visually impaired, identifying their payment cards is a real struggle. This tactile solution allows consumers to correctly orient the card and know which payment card they are using.”
With the new Touch Card, Mastercard has improved upon a current design standard by introducing a system of notches on the side of the card to help consumers use the right card, the right way, by touch alone. The new Touch Card credit cards have a round notch; debit cards have a broad squarish notch; and prepaid cards have a triangular notch. The standard has been designed to work with point-of-sale terminals and ATMs, ensuring it can be deployed at scale.
Mastercard’s concept has been vetted and endorsed by The Royal National Institute of Blind People (RNIB) in the U.K. and VISIONS/Services for the Blind and Visually Impaired in the U.S. The card was co-designed by IDEMIA, the global leader in Augmented Identity, providing trusted solutions in the physical as well as digital space.
“As the banking industry responds to new trends and developments, it’s critical that any innovation brings progress for everyone, including those with a visual impairment,” says David Clarke, RNIB’s director of services. “We’re very pleased that Mastercard understands how important it is that blind and partially sighted people have equal and independent access to their own finances.“
“Innovation should always be driven by the impulse to include,” adds Rajamannar, who is also the company’s Healthcare president. “With one in seven people experiencing some form of disability, designing these products with accessibility in mind gives them equal opportunity to benefit from the ease and security of a digital world. No one should be left behind.”
Mastercard has been embedding its signature melody at checkout counters worldwide, a signal to everyone – the sight impaired in particular – that their card transaction has gone through successfully.
Mastercard’s launch of the Touch Card underscores its commitment to inclusivity. It follows the introduction of True Name™, designed in support of the transgender and non-binary communities. The company’s commitment as a brand is to not only stand against inequity but to be an agent for change.
- 08:00 am
Soft spot in the digital revolution: Dubai-based startup Stonses launches platform that enables users to preserve memories of loved ones
Earlier this year, Microsoft patented conversational AI technology that can preserve personas of the deceased through chatbots, in an effort that appeals to the softer side of human beings. Stonses, a Dubai-based startup, has similarly launched a blockchain-powered platform, one that will enable users to preserve memories of their loved ones in a digital format. Stonses' platform, which enables its users to create unique digital identities of real-world objects, is based on Verofax's blockchain-powered asset management and NFT platform.
In today's digital era, memories associated with people exist in the physical as well as the digital world. Pictures may contain real-world objects that hold emotional significance, while many people associate key events' with objects like physical locations, family videos, wedding gifts, or even household items, which can carry priceless memories of a person we were close to. However, these memories may be scattered on phones and across locations, some are lost and others are discarded, while memories associated with them are also lost. Stonses aims to bring a permanence to those memories, through digital replicas of real-world objects linked to NFTs created by family friends and colleagues.
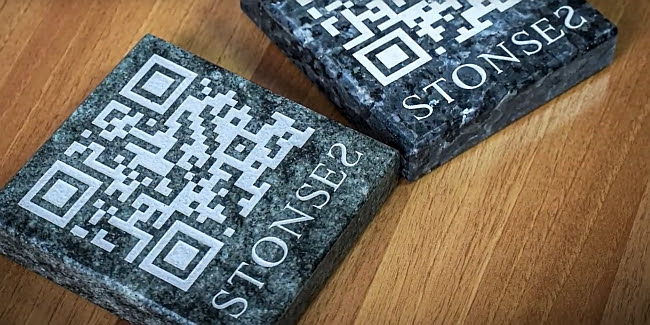
To make this happen, Stonses' memorial platform leverages NFT technology with QR codes as Physical interactions, which the user can attach to any object that reminds them of their loved ones. A digital replica of the object is then built, and a unique identity is assigned to the object. This data is loaded onto an immutable blockchain, which enables the user to preserve the object and its associated memories forever. The user, however, retains complete control over the data, and decides which is made public and what remains private, defining who has the right to create memories and who has only read access. By scanning the QR tag that connects the object to its digital replica, the user can instantly bring it, and the memories associated with that object, back to life. Thus, the QR tag serves as the bridge between a person's memories and objects associated with them, for sharing with the public, amongst close family or a friends network securely, with Blockchain.
Stonses' memorial platform is built on top of Verofax's immutable blockchain application, which brings decentralized trust and verifiability to digital objects. The QR code is a unique identifier that represents the digital object. As smartphone penetration levels go higher each year, such nimble technologies carry the potential for mainstream adoption. The shift from hardcopies to digital copies of images, books, and music is a clear signal that points to the appeal of digital objects over physical ones.
Chief executive officer of Stonses, Miha Balek says "The personalized gifts industry is expected to reach $43.3 bn by 2027 while objects are increasingly associated with people who own, use, or gift them. Digital and physical objects make up digital tokens, protected by Blockchain technology. Stonses' memorial platform is the first to help people preserve and exchange their personal belongings across generations with technology. Expect other functionalities to include treasured assets to be transferred, with ownership based on smart contracts."
Wassim Merheby, CEO of Verofax, adds "When an object is replicated or digitally combined with certified content, its replica is called a digital twin or non-fungible Token. The first NFT project was launched in 2015 on the Ethereum blockchain, but today assets and belongings can be tokenized digitally by making use of blockchain technology, which helps establish ownership and identity and seamless conditional transfer among user wallets.
Verofax's blockchain-based asset management platform, which shoulders Stonses' memorial platform, is also being leveraged for other use-cases across industries. For example, retailers are using Verofax's solution to render digital identities to their products along with information around their origin, composition, and environmental sustainability.
The ability to interface stakeholders securely and enable easy asset transfer and content access opens up new possibilities for organizations like Stonses, which is leveraging the direct-to-consumer interface to consolidate memories and assets of significance value. Stonses business model adds value to our personal lives, value that goes beyond the realm of monetary measures and efficiencies to that of meaningfulness."
- 01:00 am
FIs can now leverage Financial Health KLIs to identify and assist their account holders experiencing a wide variety of financial hardships.
Cuyahoga Falls, OH, Oct. 25, 2021 (GLOBE NEWSWIRE) -- 73% of Americans rank their finances as the number one stress in their life. Segmint®, the global leader in transaction cleansing and analytics for financial institutions (FI), has announced the launch of its Financial Health Key Lifestyle Indicators® (KLIs®) to solve for the significant gap of overall financial health and wellness that has plagued the financial industry. The problem is two-fold: a lack of tools and financial education programs with the right products and services to empower those account holders suffering from financial stress; and the inability to proactively identify those who are in or on their way to financial hardship.
Financial institutions traditionally have not done enough to bridge the gap, and account holders today expect their primary FI to anticipate and solve all of their financial needs. Whether an account holder proactively reaches out for help or not, financial institutions are the experts and need to initiate outreach on all channels with tools, educational programs and advice.
The Segmint Financial Health Indicator KLIs can drive strategic decisions when planning innovative campaigns and products to increase financial wellness in your account holders. The use of data insights derived from recurring financial spend patterns and credit transactions, specifically from these KLIs, can put an FI in a differentiated position to assess account holders’ financial stressors and trigger engagement to provide support and education.
“The Financial Health KLIs will be a game-changer for our credit union. The ability to determine in real-time when one of our members may be experiencing financial stress or hardship allows us to be proactive in our outreach to them. We have a very robust financial coaching program that offers individual financial advice for members, these KLIs allow us to identify who will need that service and when. This not only helps our members but financial coaching generates new product leads for our credit union, a real win-win situation,” said Jon Maroni, Marketing Director at Canopy Credit Union.
Recently The Financial Brand called out FIs and Fintechs alike for “blowing it” when it comes to making any real strides at affecting the financial health of their account holders. Ironically, Segmint went live with their newest set of KLIs to target this issue on the very same day their article was published.
“Together we can have a positive impact and change people's financial stories for the better,” urges Segmint’s co-founder Rob Heiser. “Financial institutions can do more. Up until now, it has been a constant struggle; prior to Segmint, data has been notoriously messy and hard to make sense of. Segmint is here to help make sense of all of the unstructured payment and transaction data and deliver insights which we can prove builds stronger relationships between an FI and its account holders. Every institution has to strive to best serve their customers and members by leveraging this valuable data as it tremendously benefits both the consumer and the banker.”
Financial institutions need to make overall financial health and wellbeing a fundamental principle within their ecosystem, where the results are limitless and have a positive direct impact on account holder relationships and financial stability, revenue, long-term brand loyalty and relevancy.
- 01:00 am
A new report from Mambu and Google Cloud shows AI will power personal customer experiences in the digital financial revolution
Artificial intelligence will deliver personalised experiences and reshape the world of banking as we know it, according to a new report from leading SaaS banking platform Mambu and Google Cloud.
The ‘Bank of the Future’ whitepaper identifies ‘ubiquitous banking’ as the next frontier in the digital financial revolution, and reveals three building blocks that will enable the future of banking:
Customer-centric strategy - products and services built around the customer for the customer, embedding AI technology to hyper-personalise the user experience
Value-based AI use cases - applications anchored on business value (revenue growth, cost saving or risk reduction) and customer value (customer experience or time to market)
Composable technology architecture - flexible, cloud-based core banking software that enables true “plug and play” functionality to respond to changing customer needs, market dynamics or technology trends
Driving this change is a combination of disruptive forces in the market. The report shows that the pandemic has increased consumer demand for always on, personalised digital and mobile-first financial services. Unlike 20 years ago, traditional banks are no longer the go-to for those looking to move or manage their money.
With better access to cloud services and increasing competition from a new wave of fintechs and non-traditional players, incumbent banks are under threat as consumers turn to neo banks and digital challengers in search of a better customer experience and utility-led services.
Eugene Danilkis, CEO at Mambu, said: “The report shows the world that banks were originally created to serve no longer exists. Historically built to last, today banks need to be built to change. If traditional players want to reposition themselves as lifestyle partners, in tune with the modern banking needs of their customers, then they must evolve rapidly - and without fear.
“Key to this will be their embrace of AI technology which has broad ranging applications from fraud prevention and risk management to delivering personalised customer experiences and driving efficiencies through greater automation. But banks must act fast if they want to avoid getting left behind. Only by leveraging the capabilities of AI and cloud technologies will they be able to reimagine the customer experience and tap into new revenue streams in a competitive market.”
“As the financial services industry continues to digitally transform, there is an increased need for solutions that help businesses deliver personalized experiences to customers,” said Joachim Wuest, Director, Financial Services Industry, Google Cloud. “We look forward to partnering with groups like Mambu to bring AI-powered solutions to banking organizations as they move along their digital transformation journeys.”
The report points to changing regulation, such as the introduction of open banking and PSD2, as forces accelerating the disintermediation of traditional banking providers. With dedicated regulation now emerging for fintechs and digital banks in some jurisdictions, it’s a case of adapt or die for incumbent players.
But banks have one asset on their side - data. With around a billion credit card transactions every day, banks have access to one of the largest volumes of customer data of any industry. Using AI, banks can harness this information to unlock unparalleled insights and growth.
McKinsey estimates that AI technologies could deliver up to $1 trillion of additional value each year for the global banking industry, combining a deep understanding of customer needs with the composable cloud architecture to roll out hyper-personalised services at scale.








