
Published
- 07:00 am
hyperexponential, the global leader in pricing decision intelligence (PDI) software, today announced the completion of its $73m Series B funding round led by global technology-focused investment firm Battery Ventures, with participation from leading Silicon Valley investor a16z, and existing Series A investor Highland Europe, which increased its holding.
hyper exponential serves insurance and reinsurance companies in the multi-trillion-dollar global property-casualty insurance industry, which protects individuals and businesses from a wide array of risks. As factors such as climate change, geopolitical unrest, and cyberterrorism have increased the frequency and severity of risks, the industry has pursued next-generation risk pricing methods to augment or supplant traditional pricing models for a changing world.
The platform of choice for the world’s most significant insurers
hyper exponential’s PDI platform, hx Renew, enables insurers to leverage large and alternative datasets, develop and refine rating tools rapidly, employ sophisticated machine learning approaches to price risk, and make data-driven pricing decisions at the portfolio and individual levels. Since the company’s Series A in 2021, hyperexponential has grown sales 10x while staying profitable, serving some of the world’s largest insurers, including Aviva, HDI, and Conduit Re.
This latest round of financing will support Hyperexponential’s expansion into the United States, as it targets opening its New York office this year. It will also enable increased investment in new product capabilities to serve growing client demand in adjacent insurance markets, including the SME insurance sector. The company plans to double its global team to over 200 in the next year.
Sponsoring its Series B investment and joining hyperexponential’s board as a director is Battery Ventures Partner Marcus Ryu, Co-founder, Chairman, and former CEO of Guidewire Software, which has grown into one of the world’s largest Insurtech companies since its 2001 founding. Also joining the company’s board is experienced Andreessen Horowitz General Partner Angela Strange.
Pricing for today’s frontier of risk
The hx Renew platform, named Insurance Insiders’ 2023 ‘Insurtech Product of the Year,’ enables customers like Convex and Conduit Re to sharpen their competitive edge with enhanced agility, efficient risk transfer, and aggregate loss avoidance. In 2023, Aviva’s Global Commercial and Specialty team was able to build 20 models in 9 months, unlock machine learning capabilities, and improve the speed and accuracy of their pricing and underwriting decisions, even as the frequency and severity of risks continue to evolve continuously.
“The insurance industry is at the forefront of a rapidly changing world and must find ways to understand and respond to that change in risk profile,” said Amrit Santhirasenan, hyperexponential CEO and Co-founder. “We’ve focused on building a capital-efficient, independent business that was both high-growth and sustainable from the outset. Although we have more cash on hand than we’ve raised, we wanted to bring on new expertise in our target markets as we continue our growth into new verticals and geographies. We are delighted to have attracted a world-class set of investors who bring an unparalleled combination of experience, expertise, and support to hyperexponential in the next phase of our expansion.”
"I believe hyperexponential is among the most compelling new entrants in insurtech I have seen in over twenty years of serving the P&C insurance industry," said Marcus Ryu. "As former software engineers and actuaries with top-tier commercial insurers, Amrit and Michael each bring a deep practitioner's grasp of the new requirements for risk pricing. hyper exponential is rapidly becoming an indispensable tool for the insurance industry to thrive in a future that is not reliably the same as the past."
Angela Strange, General Partner at a16z says, "Pricing risk is the most critical function of an insurance carrier. Yet, most actuaries still work with cumbersome Excel models and are constrained by legacy software that limits their ability to dynamically incorporate new data and more sophisticated analytical techniques. Amrit and Michael’s actuarial experience helped them design the system the insurance market needed, and Hyperexponential has achieved incredible traction with technical users and executives alike as they’ve completed multiple industry-leading deliveries around the world. hx Renew is rapidly becoming the operating system for pricing risk in the global insurance market. We are thrilled to join forces with the hyperexponential team as they launch in the US and expand beyond specialty lines".
- 05:00 am
Chimoney, a Toronto-based global payment solutions provider on a mission to connect all payment systems in the world, has entered into a new collaboration with Corpay, a FLEETCOR® brand and global leader in business payments – a partnership that is planning for unsurpassed financial inclusion and economic empowerment. This collaboration is poised to reshape the landscape of cross-border transactions and global payouts through the integration of Corpay’s innovative solutions with Chimoney to enhance Chimoney’s service, enabling cash-out to Bank Accounts in more countries to complement Chimoney’s offering of cash-out to Bank Accounts, Mobile Money, Airtime, and Gift Cards.
Through this collaboration, Chimoney’s customers will be able to gain access to and utilize Corpay’s Cross-Border innovative solutions to help Chimoney mitigate foreign exchange exposure risk as it enables businesses to pay anyone in the world using just an email, phone number, and social media username. Additionally, with Corpay’s award-winning trading platform, Chimoney's customers can now effortlessly access payouts to more countries and currencies.
“Corpay is very pleased to announce our commercial partnership with Chimoney. I do not doubt that Chimoney’s customer base can benefit greatly from our specialized service and access to our comprehensive cross-border payments and currency risk management solutions,” said Frank Mannarino, Vice President and head of Channels and alliances, at Corpay Cross-Border Solutions. “The team at Corpay is excited to build long-term business partnerships with customers and power their international payments, help them execute their plans to manage their currency risk, and support their growth internationally.”
Chimoney’s vision for Global Payments is to connect all Payment networks, currencies, and rails globally to enable people everywhere to simply get paid with minimal complexity. By working with partners like Corpay, Chimoney can ensure compliance with local regulations and leverage Partner expertise to help manage foreign exchange risks, drastically reducing foreign exchange and regulatory risks for its users and corporate clients.
“As Chimoney’s mission has always been to unlock economic opportunities globally, this collaboration with Corpay amplifies our vision of creating seamless access to more payout options and countries. With Corpay’s expertise and platform, we are poised to offer our customers access to a more expansive and efficient payout ecosystem. This is not just a partnership; it’s a synergy where innovation meets scale. For businesses and partners, it’s clear: Chimoney is setting new standards in fintech, constantly pushing boundaries, and striving for excellence," added Uchi Uchibeke, Founder and CEO of Chimoney.
- 08:00 am
The U.S. Faster Payments Council (FPC), a membership organization devoted to advancing safe, easy-to-use faster payments in the United States, today published its latest research report, titled The Practicalities of Cross-Border Payments in a Faster Payments World. This new report builds on the FPC’s previous white paper, Cross-Border Faster Payments, released in June 2021, which focused on use cases and user expectations for cross-border faster payments.
Developed by the FPC Cross-Border Payments Work Group, sponsored by Mastercard, the report delves into the history of cross-border payments, examining the evolution from ancient trade routes like the Silk Road to modern-day global financial systems. It explores the challenges faced by financial institutions in correspondent banking relationships, shedding light on regulatory compliance, security concerns, foreign exchange rate risks, and the impact of fintech players entering the field.
The Practicalities of Cross-Border Payments in a Faster Payments World also highlights the challenges faced by fintech companies, providing insights into regulatory compliance, security, foreign exchange rate risks, lack of transparency, high costs, interoperability, data privacy, competition with financial institutions, and liquidity management.
“Addressing the practicalities of cross-border payments in a faster payments world requires collaboration among financial institutions, regulatory bodies, and technology providers,” said Barry Tooker, Principal at TransactionBanker.com and FPC Cross-Border Payments Work Group Chair. “Innovations in financial technology, such as blockchain, real-time payment networks, and standardized messaging formats like ISO 20022, offer opportunities to streamline and improve cross-border payments. Overcoming these challenges is crucial for fostering global economic growth and enabling seamless international transactions.”
The report underscores the increasing pace of change in cross-border payments, mentioning key developments such as SWIFT's gpi, the global rollout of the ISO 20022 standard, the exploration of Distributed Ledger Technologies, the use of APIs, and the rise of Central Bank Digital Currencies.
"In a world of faster payments, understanding the practicalities of cross-border transactions is vital to navigating its complexities and challenges,” said Jonathan Holland, Vice President, Account Management at Mastercard and Vice Chair of the Cross-Border Payments Work Group. “The full ecosystem – from financial institutions to fintechs to payments networks – will continue to collaborate and innovate, leveraging regulation, interoperability and cutting edge technology to further optimize this critical payment process.”
The report emphasizes the transformative impact of new transaction banking initiatives, urging stakeholders to adapt to changing paradigms. It highlights the need for constant review and adaptation to emerging technologies, industry initiatives, mandates, and regulatory directives to ensure a smooth and efficient payment workflow.
"The evolving nature of cross-border payments demands a proactive approach. This report not only identifies challenges but also highlights opportunities for innovation and collaboration, paving the way for more efficient and secure transactions,” said FPC Executive Director Reed Luhtanen. “By working together, the FPC and our members continue to be a driving force in shaping the future of faster payments.”
The FPC prioritizes the inclusion of diverse perspectives in tackling complex topics such as interoperability, identifying real-world solutions that can ease adoption of faster payments, managing security risks and fraud threats, addressing barriers to financial inclusion and cross-border payments, and more, as the organization paves the way toward a future of faster payments for all.
- 08:00 am
A new report by leading providers of IT infrastructure, Softcat, offers a look into the technologies the financial sector is prioritizing over the next 12 months.
The findings form part of a report based on the views of more than 4,000 customers from 2,900 organisations in the UK and Ireland, across 27 industries in both the public and private sectors.
The report, which is produced annually, reveals the financial sector is, for the second year running, prioritizing cybersecurity above all technology areas, with 55 percent of respondents saying it is their focus over the next 12 months.
Digitalization is taking over the financial sector, evidenced this year by the increasing number of bank branches closing, replaced by digital alternatives which store information on cloud-based platforms and data centres.
Digital capabilities safeguard data but also leave it susceptible to sophisticated hackers taking advantage of cyber security weaknesses.
The Information Commissioners Office (ICO) revealed that the largest percentage increase in cyber incidents was in the finance, insurance, and credit sectors, showing an increase of 266 percent in 2023. The fundamental importance of increased investment into cyber security with the likes of zero-trust security and AI threat hunting is apparent.
Devices and End User Computing were the second most important investment priority for the finance sector, with over a third (36%) of respondents planning to invest in this area in 2024. Secure devices and appropriate technology not only prevent cyber breaches but also boost workforce productivity and increase job satisfaction, helping retain valuable staff.
The financial sector reportedly has the fourth-highest average turnover rate of all sectors in the UK (28.2%) and with associated high costs, investing in this area is key.
Furthermore, with continued higher demand for hybrid and remote working, investment in collaboration and communication technology supports and improves efficiency and productivity regardless of location. Rising generative AI will feed into this, enhancing workforce capabilities through productivity apps, but only if digital workspaces are updated and AI-ready.
This is also reflective of the third investment priority for 2024 – Data (31%).
Investment in appropriate and updated technologies and devices fosters efficient data management, including data strategy, governance, analytics, and security.
At the heart of this, lies the numerous applications and data silos that must be integrated to achieve desired business outcomes and improve employee and customer experiences. Investing in a data backbone strategy will help to identify and mitigate risks, troubleshoot problems quickly, and allow for better managerial decision-making.
Finally, with e-waste reportedly the fastest-growing solid waste stream in the world, the tech industry at large is aware of the impact it has on the environment. With this in mind, the financial sector is prioritizing tech sustainability in 2024, with 64 percent of respondents citing it as a key initiative for the year ahead.
Meanwhile, the financial sector has highlighted the top business challenges they’re expecting over the next 12 months.
Half of all respondents in this sector cited People-related challenges above all others, closely followed by Commercial Risk (40%) and Technology Experience (33%).
Again, digital transformation and the rapid emergence of generative AI across the sector reflect the relevance of these top three challenges. The heightened dependence of customers, employees, and businesses on digital technologies will continue to grow and so will commercial risk.
It is no surprise that commercial risk takes second place as a top challenge for the industry when, in 2022 the typical cost of cyber-attacks stood at $5.97 million globally. This is the highest cost of cybercrime for all sectors, with attackers seeking access to confidential transactional data, and user account information to steal money.
Training of customers and employees alike is imperative in mitigating risks associated with a lack of experience in using technology which renders users more exposed to risk.
Richard Wyn Griffith, Chief Commercial Officer, commented on the findings:
"As we continue to navigate the ever-changing landscape of technology, it is essential that we remain vigilant and adaptable. The past year has seen global unrest, but it has also presented us with countless technological opportunities for growth and innovation. By taking a measured and strategic approach, we can effectively manage the risks associated with emerging technology, while also seizing the opportunities that it presents. We must remain proactive in our efforts to safeguard against cyber threats, integrate AI into our operations, and build digital resilience.
“Only by embracing change and remaining steadfast in our commitment to progress can we hope to thrive in this new age of digital transformation. I look forward to continuing to work with our customers towards a brighter future!"
- 02:00 am
Policy Expert, the UK’s leading personal lines insurtech, has announced the expansion of its leadership team with the creation of seven new roles to help accelerate its growth plans and deliver practical innovations in products and customer service.
The expansion follows a significant year of growth, with Policy Expert ranking first for new policy sales across many price comparison websites while maintaining market-leading renewal rates of c.90%¹. The business has grown new policy sales by 66% and renewals by 97% over the last three years, underpinning a 110% rise in gross written premiums and increasing its customer base to more than 1.4m policyholders2.
Effective from January 2024, Policy Expert’s new senior appointments bring together a wealth of talent and experience as part of an expanded executive team, including:
- Linda Crichton as Chief Customer Officer, who will oversee the day-to-day operations of Policy Expert’s contact centers in Motherwell and Milton Keynes.
- Alex Bearpark as Chief Insurance Risk Officer, who will be responsible for the team’s insurance risk and reserving functions.
- Antony Green as Chief Product & Technology Officer, who will lead on technology, cloud solutions, and product delivery initiatives.
- Christine Minetou as Chief Pricing Officer, who will guide the pricing strategy across key products.
- Audrey McDade as Chief Compliance Officer, who will be responsible for the compliance and corporate risk functions across the business.
- Millie Nash as Chief People Officer, who will oversee recruitment, payroll, learning & development initiatives, and internal communications.
- Gary Barker as Managing Director of Trinity, will lead on claims.
The seven new appointments will join existing executive team members Steve Hardy, Executive Chair; Adam Powell, Chief Operating Officer; Kevin Chidwick, Chief Financial Officer; and David Prior, Chief Underwriting Officer.
Policy Expert has grown consistently to employ over 850 staff across its London, Milton Keynes, and Motherwell offices, welcoming 85 new starters in the last six months alone. The business now supports 1.4 million customers across the nation and has been rated the number one provider for home insurance on Reviewcentre.com since 2013.
Policy Expert was also recently recognized as an ‘outstanding’ business in the Best Companies accreditation scheme, ranking among the insurance sector’s top ten employers in 2023 and among the UK’s 100 best large companies to work for.
The bolstering of the executive team will support Policy Expert's growth ambitions for the year ahead. Its strategy is supported by strong digital distribution relationships, best-in-class data science capabilities, its vertically integrated claims model, and tech-led customer experience which results in market-leading renewal rates.
Steve Hardy, Executive Chair at Policy Expert, said: “We are delighted to announce the expansion of Policy Expert's executive team, with the promotion of seven talented individuals from across our business to help drive forwards the next stage of our growth plans.
“This exciting change will ensure our key business strategies are shaped by input and support from across every aspect of Policy Expert. Our expanded team will help us to operate as a single, unified business as we continue to grow our proposition and market share.
“I couldn’t be happier with the extensive experience and strategic acumen around the table of our new leadership team. Their collective input will help to ensure we keep innovating and putting customers’ needs first throughout 2024 as we build on our position as the UK’s leading personal lines insurtech.”
- 05:00 am
Scratch Financial, a fintech company that provides modern payment solutions for veterinary care, is thrilled to announce its partnership with Blue Rabbit, a leading veterinary online pharmacy. This strategic alliance will enable veterinary practices to utilize Scratch Checkout for Blue Rabbit's online payment processing and integrated reporting suite to help streamline flow of funds, reduce transaction costs, and enable unmatched operational efficiency.
The partnership between Blue Rabbit and Scratch brings substantial benefits to veterinarians and their clients including:
Streamlined Payment Processing: A faster, more secure payment experience when clients purchase pet medications, diets, and supplements through their veterinarian's online pharmacy platform powered by Blue Rabbit. Veterinary practices using Blue Rabbit can spend less time on accounting-related tasks and reduce transaction-related expenses.
Enhanced Data and Analytics: With integrated payment data from Scratch and access to real-time, comprehensive analytics, Blue Rabbit can increase operational efficiency for their customers and enable timely month-end reconciliation.
Enhanced Payment Options: Clients will enjoy extensive payment options, making it easier to afford essential medications and treatments for their beloved pets and horses.
Exceptional Customer Support: Blue Rabbit and Scratch are committed to outstanding customer service. This partnership ensures that clients can access top-tier support when they need it most.
Ben Shaw, President of Blue Rabbit, expressed his enthusiasm about this collaboration. He stated, "Scratch is an excellent payment solutions partner for Blue Rabbit that enables significant advantages to our veterinary partners. Our team is committed to providing veterinarians with best-in-class technology to improve health and financial outcomes within their hospitals; this partnership advances that cause with a partner who shares our dedication to customer care and the veterinary industry."
Scratch's CEO, John Keatley added, "We are excited to work with Blue Rabbit, a company that shares our commitment to the veterinarian and to increasing accessibility to animal wellness. Together, we'll transform the way pet and horse owners work with their veterinarians to access vital medications for their animals."
This partnership signifies a significant step forward in the world of animal health, creating an ecosystem that prioritizes seamless, PIMS-connected solutions for veterinarians, and convenient, world-class commerce for pet and horse owners.
- 05:00 am
Backbase, the global leader in Engagement Banking, has agreed with Danske Bank, a leading Nordic bank based in Copenhagen, Denmark.
This agreement provides Danske Bank with access to the Backbase Engagement Banking Platform, which will progressively be implemented across digital channels in the coming years. This will enable Danske Bank to offer its customers a continuously improved digital customer experience, as the enhanced flexibility allows it to tailor its business operations around the customer journeys.
Frans Woelders, Chief Operating Officer at Danske Bank, highlights: “This engagement is testament to our customer focus and our commitment to ensuring the best digital banking experience for the future. A new platform that works across the web, mobile apps and our adviser tools is one of the ambitions in Danske Bank’s Forward ’28 strategy, and the agreement with Backbase is the next step towards achieving that ambition.”
The Engagement Banking Platform plays a pivotal role in achieving:
- Modernization and simplification of the existing IT landscape by reducing the number of silo-ed channel applications.
- Mobile-first engagement model: Establishing a customer-centric approach, seamlessly guiding customers between automated and expert advice.
- Unified platform: Consolidating data, business logic, and workflows into a single, customer-centric platform for efficient journey orchestration, benefiting both customers and bank employees.
- Agility and freedom: Enhancing flexibility to swiftly implement business capabilities and adapt to evolving market dynamics.
Christian Bornfeld, Head of Personal Customers and Financial Crime Risk and Prevention at Danske Bank, says: “This platform will allow us to take our interaction with customers though our digital solutions to the next level and to introduce enhancements at greater speed than ever before. It will thus enable us to provide market-leading convenience and personalisation for our customers with great insights, increased proactivity and easy access to assistance and advice.”
Jouk Pleiter, Founder and CEO of Backbase, shares, “We are thrilled to announce the engagement with Danske Bank, a visionary collaboration set to redefine the future of banking. Together, we will execute a bank-wide, digital transformation program and elevate Danske Bank's customer experience to new heights.”
- 02:00 am
Fenergo, the leading provider of digital solutions for client lifecycle management (CLM), know your customer (KYC) and transaction monitoring, today released its annual findings on global financial institution enforcement actions, which reveal that the value of penalties imposed on firms surged 57% in 2023.
Penalties for failing to comply with anti-money laundering (AML), KYC, environmental, social, and governance (ESG), sanctions, and customer due diligence (CDD) regulations totaled $6.6bn in 2023, up considerably from $4.2bn in 2022 and $5.4bn in 2021. The highest value fine at $4.3 billion was issued to the world’s largest cryptocurrency exchange, Binance, in relation to AML failings. Binance was ordered to pay the fine to resolve investigations by the US Department of Treasury’s Financial Crimes Enforcement Network (FinCEN), Office of Foreign Assets Control (OFAC), and the Commodity Futures Trading Commission (CFTC).
The Cayman Islands, where Binance is headquartered, has subsequently seen the single largest regional increase in fines received from global regulators, from just over $3m in 2022 to more than $4.5bn in 2023. Among the most punitive jurisdictions with the highest penalty totals were the US, which saw an increase of 69% to $5.1bn, the second highest year on record, and China, up from $55m to $1.4bn in 2023. Regulators in the United Kingdom were more lenient, handing out penalties to FIs totaling $25.26m, down 86% from 2023.
Crypto and payments firms have driven the biggest uptick in fines this year, representing 69% and 21% of global penalties, respectively. According to Fenergo’s analysis, 2023 marks the first year when crypto and payments firms surpassed traditional financial institutions with regard to the value and severity of financial penalties received for AML breaches.
Broadly speaking, the most significant increase in enforcement actions relates to KYC and CDD, rising to a staggering $219m over the last 12 months, up from $2.3 million. Following a similar trajectory, ESG fines have increased by 246% to reach a record high of $19m in 2023.
Commenting on the findings, Rory Doyle, head of financial crime policy at Fenergo, said: “Regulators have clearly had their foot on the accelerator this year, demonstrated by the huge enforcement crackdown on virtual currency providers. These findings spotlight a need for more robust frameworks for AML within newer, digital-first providers. That said, firms of all sizes must ensure they are well prepared from a financial crime perspective as regulators prioritize AML/counter financing of terrorism (CFT) in 2024.
“The challenges facing financial institutions this year include the need to plug the growing educational gap and the ongoing shortage of qualified financial crime professionals to conduct effective client due diligence. With more work and fewer resources, firms must look to leverage cutting-edge technology to create a centralized financial crime ecosystem – including machine learning and artificial intelligence – to reduce the growing skills gap and, ultimately, mitigate the risk of further enforcement action over the coming 12 months.”

Nikhil Menon
QA Engineer at Baton Systems
Anybody who has worked in software development can faithfully attest to the fact that quality assurance (QA) testing, and the functional testing cycles that are require see more
- 06:00 am
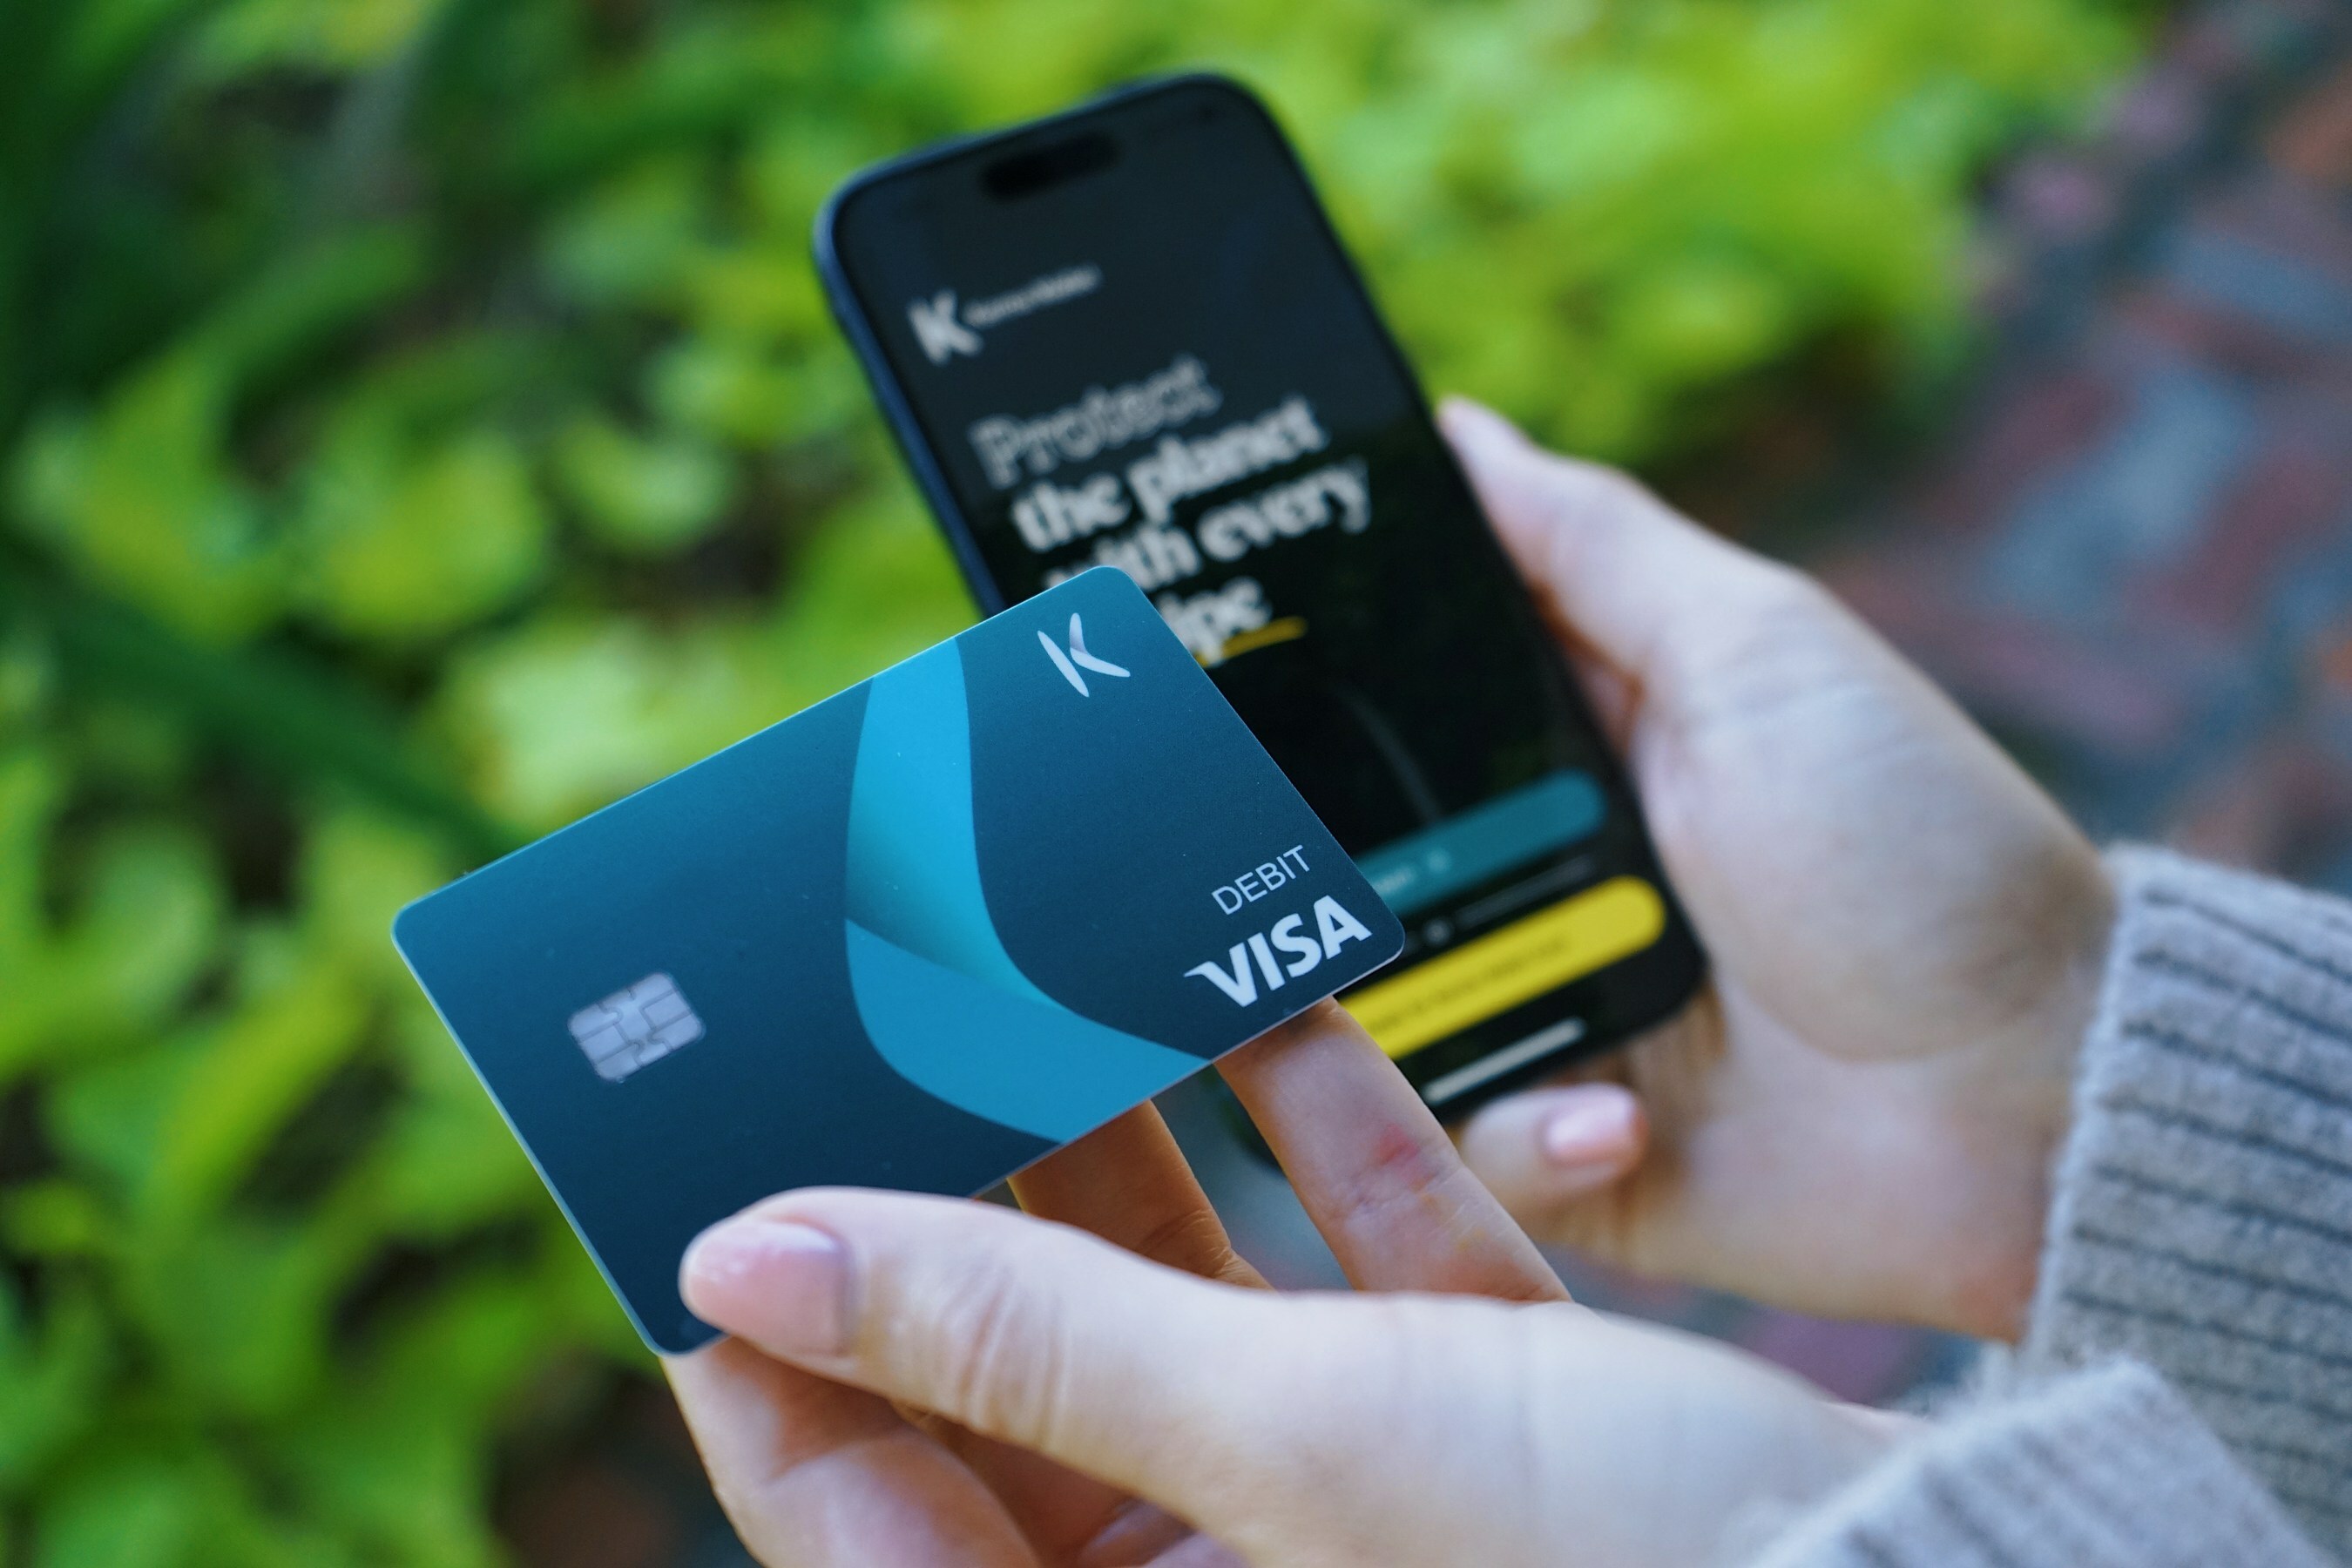
In a bold move to fuse financial technology with environmental stewardship, Karma Wallet announces today the launch of their Karma Wallet Card, a groundbreaking new spending tool that redefines the power of purchase. Accompanied by a robust $2M+ funding injection from socially conscious investors, including the innovative Tweener Fund, this launch heralds a new era of impact-driven, conscious consumerism.
Designed to disrupt the fintech status quo, Karma Wallet offers an easy mechanism for consumers to understand the true impact of their spending habits. The Karma Wallet reloadable prepaid debit card is the first financial product to provide real-time insights into the social and environmental impact of every transaction. Karma Wallet's growing community now has the unparalleled ability to turn their daily and recurring expenses into direct action, earn cashback rewards, and automatically support reforestation efforts and local food security initiatives on select purchases.
"There is a big gap between intention and action," Karma Wallet CEO and co-founder Jayant Khadilkar told Sustainable Brands™ in 2022. "Through the Karma Wallet Card, we're turning everyday transactions into opportunities for profound action."
The Karma Wallet companion app comes with a dashboard that provides an unparalleled view into the socioeconomic impact of each purchase, and access to comprehensive impact evaluations of 15,000+ brands. This proprietary ecosystem showcases where, and more importantly how, cardholders can make purchasing decisions that reflect their ethos, and the card allows members to put that directly into action.
"Our members are change-makers; participating in a global effort to use money as a tool for change," explains Kedar Karkare, PhD, Karma Wallet's co-founder. "Our mission is to enlighten, engage, and empower consumers to be the change they want to see in the world, one purchase at a time."
With the $2M+ capital poised to propel the Karma Wallet card into the marketplace, the team's vision is clear: to catalyze a shift towards mindful spending, educate consumers, and shape a future where every dollar spent supports a more sustainable and equitable world. Their recent inclusion on Inc.'s Best in Business 2023 list underlines Karma Wallet's ascension in the fintech space, reflecting a trajectory that is as impactful as it is inspiring.








