
Published
- 07:00 am
Citi Treasury and Trade Solutions has forged a partnership with Vietnam-based intermediary payment service provider Payoo to facilitate last-mile consumer-to-business collections for corporate clients in the country.
Debopama Sen, Singapore and Asean head, Citi Treasury and Trade Solutions, says: "This is in line with our strategy to leverage the potential of the thriving fintech ecosystem in Singapore and Asean to enhance our client value propositions."
The partnership was announced at the sidelines of the bank's inaugural Asean FinTech Day which commenced in Singapore today, where a total of eight startups are presenting their propositions to a judging panel of senior Citi executives. Selected finalists will work in partnership with Citi to commercialise and launch market-ready services in the next six to nine months.
The inaugural event in Singapore follows from previous Treasury and Trade Solutions FinTech Days held in other markets including North America, the United Kingdom and India.
“Citi is actively working with FinTechs around the world to create new services and capabilities on our platforms for the benefit of our clients,” says Manish Kohli, global head of payments and receivables, Citi Treasury and Trade Solutions. “These events play an important role in allowing us to engage with the fintech ecosystem in order to co-create the best solutions for our clients in the digital economy.”
- 02:00 am
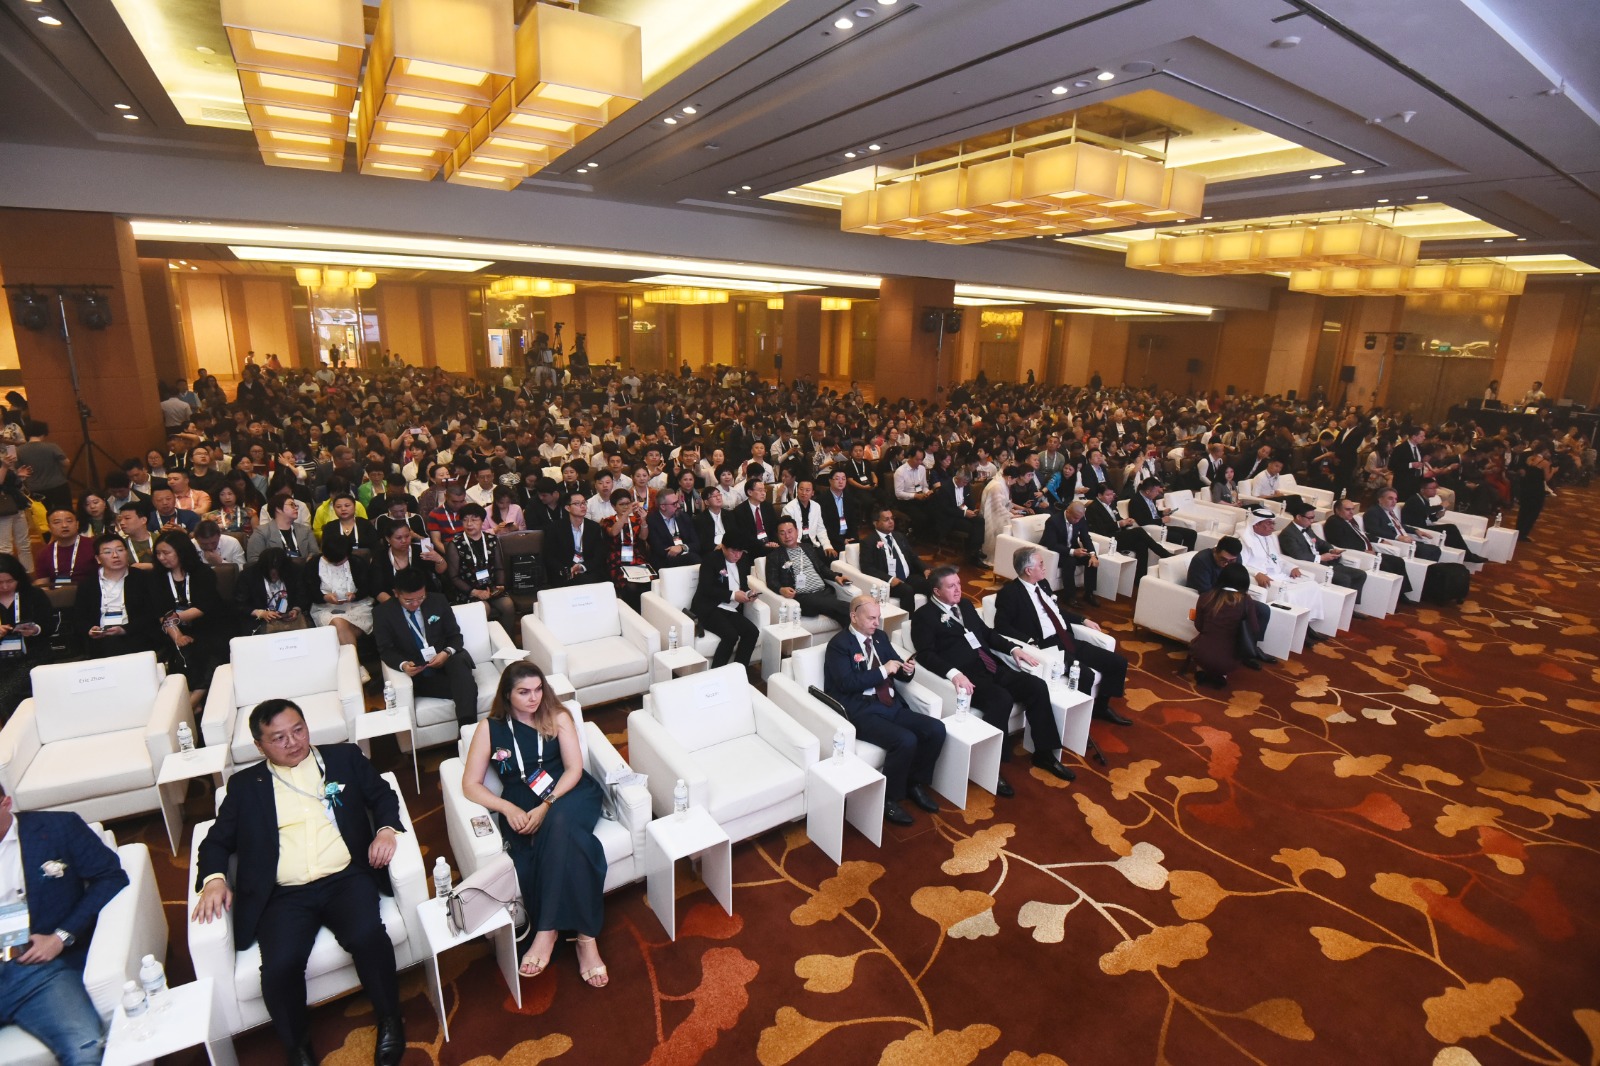
On April 23-24 more than 3000 attendees from 70 countries gathered in the world’s blockchain capital — Singapore. Top crypto companies (Binance, Huobi, Listing.Help, crypto messenger ELVN and others), world famous experts (Tim Draper, Roger Ver, Alex Reinhardt and others), mining giants (Bitmain, Btc.com), representatives of key cryptocurrencies (Litecoin, Dash, Cardano, Neo and others) gave talks about the present and future of blockchain and cryptocurrencies at the 3rd Global forum in Asia.
Speakers discussed the current IEO boom, blockchain hacking and other crypto and regulation trends. In particular, Alex Reinhardt, the founder and CEO of the ELVN crypto-messenger, proposed new rules for ICO in his speech. The main idea is the availability of a finished project with tested monetization and a well-developed community. Companies and investors made dozens of contracts in meeting rooms, expo and VIP areas. Bitcoin also supported the positive wave from the blockchain community and grew by 5% during the event.
One of the forum’s highlights was a StartUp Pitch — where various blockchain projects from Italy to China presented their blockchain and crypto ideas. The winner chosen by the jury of private investors and fund’s founders was a blockchain based marketing platform Bloomyt.
The next Blockchain Life forum will be held on October 30-31 in Moscow, Russia. The ticket sales start on May 20th at the official website blockchain-life.com.
- 03:00 am
Turnkey open banking platform provider, Token.io, today announces its selection by Sberbank Croatia to deliver PSD2 compliance and open banking capabilities.
Sberbank Croatia is a subsidiary of Sberbank, a tier one European bank in terms of assets. The bank is now integrating TokenOSTM into its banking infrastructure to establish PSD2 compliance and enable the systems flexibility required for it to develop new value-added open banking services, such as bank direct payments and account aggregation.
The news extends Token’s relationship with Sberbank which began in 2018 when Token announced a partnership with Sberbank Slovenia, and is further evidence of Token’s traction in a region that initially favoured solutions from central European providers.
Csaba Soos, CEO, Sberbank Croatia, comments: “The development of digital technology is one of Sberbank’s key strategic objectives and our partnership with Token demonstrates that progress is well underway at Sberbank Croatia. By cooperating with Token, we can offer an improved user experience and a larger portfolio of value-added services for both our corporate and retail customers.”
Steve Kirsch, Founder and CEO, Token adds: “As the winner of the 2018 Central and Eastern Europe Transaction Banking Award, Sberbank has already demonstrated its commitment to digital transformation. Our turnkey, cost-effective open banking solution is enabling Sberbank Croatia to comply with the PSD2 regulation while remaining focused on achieving its strategic goals and growth through innovative new services.”
Token offers the industry's simplest and most secure transaction-based PSD2 API, which, being cloud-based, gives Sberbank both flexibility and scalability when initiating and managing transactions. Now, Sberbank Croatia can be accessed by any regulated TPP in Europe. The bank gains crypto-based security and programmable money technology together with the operational support, consent management, monitoring and reporting needed to succeed. Compared to alternative open banking solutions available, Token is on average 70% less expensive to implement.
For further information about Token.io, and how its open banking infrastructure enables PSD2 compliance and new revenue streams for banks visit: www.token.io.
Visit Token, proud sponsor of the Fintech Finance Around the World Payments Race, at Money 20/20 Europe in Amsterdam 3-5th June on stand H10. Contact the team at press@token.io to arrange a meeting.
- 08:00 am
The Western Union Company’s global digital money-moving capabilities are making significant headway across the Middle East, with seven countries now offering online services, connecting customers to their families and loved ones around the world digitally with the choice to pay for transactions online or in person.
The United Arab Emirates (UAE) was enhanced with the latest generation of Western Union’s omni-channel platform, joining Bahrain, Jordan, Kuwait, Lebanon, Oman and Qatar, as a part of Western Union’s deep commitment to keeping the Middle East at the forefront of the digital revolution.
In the UAE, the company launched the Western Union® mobile app and relaunched the Westernunion.com website. Customers in the UAE now have the choice to pay for transactions online or within the app via direct transfers from their bank accounts set up in the UAE.
Currently, Western Union offers digital service via WU.com in over 60 countries, plus territories, with mobile apps in 35 countries; moreover, its entire network is a combination of retail Agent locations in more than 200 countries and territories, account payout in nearly 100 countries, and wallet payout in a dozen countries.
The Middle East is a vital and rising economic hub bringing people together from across Europe, Africa and Asia and lifting them toward prosperity. International migrants working and living across the region represent a large part of the population and collectively send billions of remittances back home. In the UAE, 88 percent of the population are international migrants, followed by Qatar at 75 percent, Kuwait 72 percent, Bahrain 51 percent, Oman 41 percent, Jordan 40 percent and Lebanon 34 percent, according to the World Bank1.
“Our commitment to the Middle East is a step forward to a more prosperous and globally connected future. Our digital services support a globally-integrated living without leaving anyone behind. We use cutting-edge technology to simplify money transfer. Our systems automatically handle complexities from compliance to volatile currency exchanges so users can transfer money 24/7 to nearly every country across the world, with the touch of a few buttons,” said Western Union President and CEO, Hikmet Ersek, during the launch ceremony in Dubai.
“Our systems are also designed to allow customers at any level of financial experience to use any channel they like, be it digital or cash, online or offline,” he said.
The UAE launch is aligned with the country’s vision, one that is staying on the edge of innovation to make a better life for all its people. Digital tools mean, at their essence, more ways to reach more people and more opportunities for all. The more the UAE fulfills its ambitious plans for economic transformation, the greater will be the opportunities to interact with the world. More workers from overseas, more tourists visiting its shores, more students going abroad to study all.
As one of the world’s most innovative nations, the UAE is striving forward with an ambitious agenda of growth and dynamism. According to the Global Competitiveness Report 2018 by the World Economic Forum, the UAE is ranked first in the world for mobile broadband subscription rate, and second in the mobile subscription index - which highlight both the country’s high level of commitment to digital development and its fast rate of mobile adoption.
Western Union has been providing money-transfer services in the UAE for over 20 years and has more than 900 retail agent locations in the country. Customers still have the choice to access these locations to send money transfers in person, reflecting the company’s commitment to providing choice and options to connect to families and friends around the world.
- 09:00 am
Esme Loans, the standalone digital lending platform for SMEs and scale up businesses has today announced that it has now lent over £50million to UK businesses.
The lender has seen a continued period of strong growth in the run up to today’s announcement, following an uplift in lending of 337% between 2017 and 2018.
Esme was borne out of an ‘innovation cell’ within NatWest, in response to the emergence of innovative, direct P2P lending platforms across the market. The platform was developed with the aim of simplifying and speeding up the lending process for UK SMEs.
Richard Kerton, CEO, Esme Loans said: “We’re delighted to be able to support UK entrepreneurs and small businesses. We have achieved great momentum since launch just over two years ago, and we are now lending over three times more than we were this time last year. Our customers tell us they love the speed and ease of our platform, and we are continuing to invest in our technology to ensure that we’re offering a seamless, intuitive experience that provides customers with the funding they need.”
As part of its plans to continue this growth, Esme Loans recently announced it had enlisted Microsoft to build a data warehouse and AI-assisted chatbot to help improve its customer experience; in January, NatWest also announced that it was beginning to offer the product directly to its Business Banking customers for the first time.
- 06:00 am
Investment app, tickr, is today launching its crowdfunding campaign on leading investment platform Seedrs. Funds raised will be used to accelerate user acquisition, while building several new features including a visual newsfeed giving users an interactive overview of the companies in their portfolio and the work they are doing to make an impact on the world.
tickr’s user statistics demonstrate the scale of appetite for disruption in the investment market; 40% of users are women, while 90% of users are between the ages of 25 and 39, and 65% are first-time investors entirely.
The campaign kicks off at a time of rapid development for tickr, which marked its formal launch into the market in December 2018 on iOS, with Android following in February 2019. Initial funding of almost £1 million came from a range of investors including Dutch VC firm SLJ Investment Partners B.V in summer 2018, who said “the technology has the power to be an insightful force for good within the financial services industry, and appeal to a whole new generation of investors.”
tickr was recently named as one of Tech Nation’s 2019 10 rising stars and one of the world’s most innovative companies by WEALTHTECH 100.
The tickr team has expanded to 11 full-time members, with offices in London and Liverpool.
Commenting, tickr co-founder Tom McGillycuddy said: “Millennials are twice as likely to invest in a portfolio that reflects their values and beliefs, but it’s still the wide held view that investing into companies doing good and promoting change in the world is difficult or even impossible. tickr was built to smash this perception by providing a simple and forward-thinking way to invest in truly transformative companies combating social and environmental injustices, while potentially earning strong returns on their cash.
“We’ve been amazed with the uptake so far and we’re confident this crowdfunding campaign will take us one step further in realising our ambitions.”
For further information on the Seedrs campaign, please visit: www.seedrs.com/tickr
- 04:00 am
The journey from unbundling to rebundling and back has been a formidable one. Emerging technologies and the pace of innovation are driving changes throughout the banking industry at an unprecedented rate. From Asia to Europe, U.S. to Africa, and Australia to the Middle East, consumers are not only increasingly adopting digital – most are demanding it. While the movement toward our ability to bank anywhere is inevitable, the path towards transformation varies from one region to the next – and very different models have evolved within each geography. While some challenger banks are trying to go at it alone, as in the case of Starling and Monzo, both of which leverage technology and data to provide digital-only offerings focused on changing consumer needs, incumbent banks are grappling with the right way to evolve: some choose to stand up a whole new separate digital bank to appeal to new demographics (as in the case of Standard Chartered in Hong Kong), while others choose to rebuild and rebrand. The challenge of the latter is obvious: the digital experience is dependent on the ability to update/upgrade the legacy core system. Regardless of which path to take, the fact remains that going digital extends beyond moving transactions from analog to internet to mobile as part of some surface level technology refresh. Becoming digital is a complete transformation that requires a change to the bank’s DNA.
This is the new normal of transformative business model evolution within financial services. As opposed to the “move fast and break things” culture of Silicon Valley – innovation – to be effective and sustainable – must be thoughtful and disciplined. This new mindset needs to be embedded in the culture of the organization, with steadfast commitment from the top down to those with boots on the ground. Bringing new products and services to the marketplace will require willingness to trial by error, tolerance to accept failure, and openness to learn. “How open are we?” becomes not only a question of technical capabilities but also a question of culture and one of survival.
How deep is our technical bench?
While it might seem trivial, banks of the future will be increasingly run by technology. With more consumers adopting the digital products and services from leading big tech companies such as Apple and Amazon, they have come to expect the same seamless experience with banking as well. In the new digital era where people are spending more time than ever on their mobile devices, where retail foot traffic has dropped, where customers no longer visit bank branches, consumers prefer to bank at the comfort of their home or as they go about their day, when they want it, and how they want it. Mobile banking quickly became a table stake instead of nice-to-have, and the financial experiences expected from our applications have moved from reporting the past to predicting the future . To compete, financial institutions must reimagine banking itself within the context of our daily lives, our routines, our needs, our desires, and their impact on our future .
Looking at corporate technology budgets may help to shed some light on the direction where some of the banks are transforming – and whether they are spending to survive, or spending to evolve. For example, J.P. Morgan’s technology budget will grow to US $11.5 billion, much of which is slated for strategic investments, such as exploring quantum computing and developing new retail products. They are also opening a FinTech campus in Palo Alto in 2020, which further demonstrates their commitment to learning from and leveraging the technology platforms that influence much of their customers activities. Meanwhile, Bank of America’s technology budget is said to be US $10 billion, of which, a third will be slated for “new initiative investment spend.” Banks are not taking threats to their business model lightly. Their spending habits demonstrate that.
Open banking and the rise of the super app
Until recently, a consumer's financial data was centrally held within their financial institution. But this too has started to change with the implementation of various Open Banking initiatives that have evolved through the past decade and launched within recent years across the globe. It has become apparent that the future of banking will be driven by open business models and APIs. A quick look at what has transpired gives us a glimpse of where banking is headed.

Since the Open Banking Implementation Entity (OBIE) has rolled out two of the four releases as part of its roadmap, over twenty million API calls for data are being made every month. In the past month, the greatest beneficiaries of account switching have been banks like HSBC, Santander, and Nationwide, along with FinTechs like Monzo, Starling, and Revolut.
In the U.S., though regulatory changes are likely far off, it is inevitable that a more open model will emerge as big tech players like Google, Apple, Amazon, and Facebook dabble in payments and other activities, as in the case of Apple’s new Apple Card initiative, in partnership with Goldman Sachs. While it might be not be as avant-garde as some bank-insiders would like, Apple is putting its stamp in the payment space by declaring: “Created by Apple, not a bank” in its launch campaign. Much to banker’s chagrin, this will likely resonate with consumers more than they’d like.
Meanwhile, the emergence of super app models in the East by tech giants such as Alibaba and Tencent has presented consumers with a new way of consuming banking services, most notably in the payments area. Challenger banks such as MYbank and WeBank (backed by Alibaba and Tencent respectively) have grown substantially the past few years. At the same time, Alibaba’s affiliate Ant Financial has been expanding rapidly outside of its home market, China, by pursuing a strategy of serving the enormous market of Chinese tourists and are accustomed to the AliPay platform. The super app is connected with more than 200 institutions, including over 100 banks, 60 insurers, and 40 wealth management companies and security brokerages.
It is still far too early to judge whether the great unbundling efforts have been successful or not. Thousands of fintech startups have taken market share in key revenue areas and banks partnering and investing in them has not slowed down the march and impact of the fintech ecosystem. The move toward open banking and large-scale efforts by dominant technology platforms will only exacerbate the issues banks face. Technology will continue to enable new value propositions that were never expected. This will work to re-establish customer intimacy and trust by acting as a personal CFO for customers across every walk of life. Winners will be those that can create longer term savings and wealth, optimize spending, and build more proactive and personalized insights that extend beyond traditional financial services. Rebundling acts as an opportunity for us to reimagine – not to build on the past, but to seed future business models.
In a world where Chinese citizens with Chinese bank accounts can conduct their whole life on Alipay and WeChat super apps while outsiders pay cash; where 47% of American consumers are still writing checks; where people in Africa can pay and obtain microloans on their mobile phones in an instant – the answer to the age-old question to the promised land: “Are we there yet?” is unfortunately “No, not yet.” As Chris Skinner wrote in his book Digital Human: “The new world is one of transient relationships, shorter-term commitments and everything online all the time. However, the financial system is built for lifetime relationships, long-term engagement, and everything over the counter.” If the industry is to thrive in a new environment with competition from global technology firms, we must leverage the scale and trust of incumbent banks, agility and focus of fintech startups.
It is time to embrace open banking business models or banks will cease to exist.
***
Join us at Money20/20 Europe this June in Amsterdam, as we dive further into the game-changing stories and trends, driving forward the global Financial Services, Payments and FinTech community. Find out more about the Money20/20 Agenda and Stories by clicking on the links below.
- 01:00 am

The 2019 Islamic Finance Awards, presented by World Finance Magazine, has announced that Temenos (SIX: TEMN) has won the ‘Best Islamic Banking & Finance Technology Provider’, for its breakthrough digital front office product, Temenos Infinity, and next generation core banking system, Temenos T24 Transact. For the second consecutive year, Temenos was recognized after demonstrating remarkable contributions to Shari’ah-compliant banking, finance and investing across the region. The World Finance Islamic Finance Awards bring together key players in the Islamic finance industry, and recognize the most successful operators in the field from around the globe.
Shari’ah-compliant financial assets are forecasted to reach $3.8trn by 2023, up from $200bn in 2003. As the industry matures, the 2019 World Finance Islamic Finance Awards shine a light on the companies that are pushing its boundaries. The 2019 World Finance Islamic Finance Awards recognize the institutions that are setting the agenda on the international stage.
Nominated by World Finance magazine readers and website users, Temenos Infinity and Temenos T24 Transact, Temenos’ pre-integrated, open, digital banking offering, provide exceptional features for Shari’ah compliance. This winning combination brings together the richest packaged functionality with the most innovative cloud-native technology, allowing banks to implement faster and more cost-effectively. Temenos was able to demonstrate outstanding product and service delivery, growth, market presence and governance. These were the main criteria in the evaluation by the judging panel.
During the evaluation process, Temenos was commended by the World Finance Awards committee for the remarkable feedback received from subscribers regarding the solution’s flexibility in supporting both fully-fledged Islamic banks, as well as conventional banks with Islamic windows. Temenos’ products were identified as the leading solution for retail, commercial, investment and wealth management banking operations. Shari’ah-compliant features include Murabaha financing, diminishing Musharaka, Qard Hasan, Bai Al Salam, Istisna’a and parallel, and financing Ijara, Tawaruq, Itsisna’a and many other Islamic finance aspects.
Jean-Paul Mergeai, Managing Director Temenos Middle East & Africa commented: "Temenos is delighted to once again receive the ‘Best Islamic Banking & Finance Technology Provider’ award from World Finance in recognition of our historical and continuous investment in Islamic finance. For over 20 years, Temenos has been supporting the Islamic finance community with flexible, scalable and innovative Shari'ah compliant solutions that have been specifically designed around the customer journey across any business line. Our close collaboration with Islamic sector has been rewarded with recent signings including Al Rajhi, the world’s largest Islamic bank, and Palestine Islamic Bank, the largest Islamic finance institution in Palestine. We look forward to continuing to empower Islamic banks with open, flexible and agile technology, enabling them to reap the benefits of end-to-end digitalization with Temenos Infinity and Temenos T24 Transact cloud native and cloud agnostic solutions."
Temenos’ winning combination of Temenos Infinity and Temenos T24 Transact not only enhances efficiency with automation and continuous deployment, but also offers differentiated customer service and solutions. Temenos was once again praised by industry peers for its remarkable features, including an Islamic Treasury module, Islamic Portfolio Management platform, Islamic Retail Banking platform, Islamic Product Builder.
- 09:00 am

Klarna Bank AB (publ) has released its annual financial report for 2018 (link), revealing that Klarna’s alternative payment methods and checkout services continue to resonate strongly with consumers, merchants and partners across all 14 core markets. With an average of 1 million transactions a day on the platform, Klarna’s total global sales volumes rose by 36% YOY in 2018 to 29bn USD. The rise in volume follows an equally impressive 31% lift in revenue to 627m USD in 2018.
Welcoming 25,398 new merchants globally in 2018 - growth of almost 25% compared to 2017 - Klarna now provides payment services to over 130,000 retailers in a wide range of verticals across markets. This includes the likes of IKEA, H&M and its brands (Cos, & Other Stories, Monki, Weekday, Arket), Ticketmaster Europe and Sonos. These names add to Klarna’s existing global roster of several of the world’s best-known brands such as Adidas, Zara, Arcadia Group, SAS and Turkish Airlines.
Klarna’s consumer base has also expanded rapidly, with Klarna welcoming almost 26 million new consumers in 2018. Klarna users are highly engaged and loyal, and as their preference for Klarna’s flexible payment options continues to grow, many markets are seeing up to 70% of consumers making repeat transactions during the year.
Luke Griffiths, UK General Manager for Klarna says, “2018 has been a phenomenal year for us. Klarna has led the market in establishing an entirely new category withPay later, that has proved hugely popular with today’s savvy consumers expecting more flexible, personalised and intuitive ways to shop. As a result, in response to demand from customers, we’ve seen a significant rise in the number of retailers adopting Klarna solutions in the last 12 months. This includes some massive global brands like IKEA and H&M joining the family, with the pipeline ahead just as strong.
“At the same time, to turbocharge future growth, Klarna made a strategic decision at the start of 2018 to significantly increase investments in people, systems and products in order to further strengthen capabilities and support future business plans. And with more and more consumers using and loving our offering, we feel very optimistic that this trajectory will continue. ”
The time is now for Pay later in the UK
The UK has seen rapid growth as both new and existing Klarna payment options generated strong demand amongst retailers and consumers. The biggest success story isPay later, which lets shoppers buy now and pay for goods up to 30 days later - completely interest and fee free.
In the last quarter of 2018, 25,000 new UK consumers each week decided to Pay later with Klarna. On average, a Klarna Pay later user in the UK does 8.6 transactions per year - showing strong affinity for this unique customer-centric payment option. Overall, 4.4 million Klarna users across payment options in the UK market. Increasingly, shoppers are proactively asking retailers to onboard Klarna as their preferred payment option using the hashtag #iwantklarna.
This is driving strong demand amongst merchants, which has led to significant growth in Klarna’s UK merchant base. New retailers during 2018 include In The Style, Missguided, Swoon, Moss Bros, Beauty Bay and Gymshark, alongside Klarna favourites like ASOS, Topshop, Schuh and JD Sports. In all, Klarna UK currently has over 3,500 active UK retailers.
During 2018, Klarna launched a short-term instalments product that allows shoppers to fund purchases in three equal interest-free payments. The popularity of this offering has soared with merchants since its launch, with Arcadia’s brands including Topshop, Topman, Miss Selfridge, Wallis and Burton among the first to go live in November 2018. After adopting this product, retailers see on average a 55% increase in AOV and a 44% increase in conversion.
Klarna’s acquisition of Close Brothers Retail Finance has significantly strengthened its position in the UK market for longer-term instalment credit, and has enabled expansion of the consumer offering into new verticals, with Klarna now working with Samsung Electronics, GAME, Mothercare and Cotswold Outdoor via the acquisition.
Klarna has been supporting up-and-coming UK entrepreneurs through its ‘Smoooth Stores’ competition. Launched to discover and develop top retail talent across the UK, the competition saw entries received from all over the UK, and over 5,000 votes cast by the public. Won by Simon Bourne of The Hand Dyed Shoe Co, the prize includes £10,000 alongside mentoring from senior Klarna executives, and free use of Klarna’s Pay later service for 12 months.
Griffiths concluded: “The UK has significantly contributed to Klarna’s global growth with new merchants and heightened consumer usage, which have increased our UK footprint dramatically. Our relentless focus on customer experience, combined with a diverse payments portfolio, have differentiated us in the market and are clearly resonating with shoppers who want financial flexibility, convenience and choice. This winning formula will support our continued success through 2019 and beyond.”
- 05:00 am

Synectics Solutions, the Stoke-on-Trent based Fintech, predictive analytics and data services company, has been honoured with the prestigious Queen’s Award for Enterprise for Innovation.
The award was made for its outstanding successes in innovation, including the application of technology to save the UK taxpayer hundreds of millions annually from potential fraud.
The Queen's Awards, which are the highest official UK accolade for British businesses, aim to promote excellence and drive economic growth.
The Innovation category awards companies that go above and beyond in their area of expertise, and is designed for those offering unique innovations. Winners of this category must also show outstanding commercial success.
The name Synectics is based on the noun, meaning a problem-solving technique which seeks to promote creative thinking, typically among small groups of people of diverse expertise. This problem-solving, people first, creative mentality has propelled Synectics Solutions to be recognised as a world-leading pioneer in data driven software solutions that prevent financial crime and mitigate risk.
Synectics Solutions’ Managing Director Carol Shanahan said: “To win an award of this calibre is a fantastic achievement, contributed to by every one of our 360 employees. Of the many awards we have won over the past few years, this is the pinnacle of our work to date.
“Kevin and I started this business 27 years ago, with a core purpose to be a people centred company that always delivers the highest level of innovation and service. We are extremely honoured and proud that this approach, supported by the unique culture that we all embody at Synectics, has led us to win the Queen’s Award for Innovation.
“Our innovative technologies make a unique contribution to our UK, European and North American customers. These innovations now prevent £150 million annually in potential fraud losses for the UK government through our work with the Cabinet Office for the National Fraud Initiative, and even bigger savings have been made through our collaborative work in the private sector. Here, our advanced technology and ability to bring organisations together for a common purpose helps identify organised criminal gangs, prevents low level frauds, and makes predictions to block financial crime.”
Business Secretary Greg Clark said: “These prestigious awards help shine a light on all that is great about UK business today. I am extremely impressed to see such a wealth of talent and innovation from across the UK being recognised by Her Majesty The Queen.
“These awards recognise the innovative products and services being provided by British businesses that are in demand across the world, as well as the sheer determination and hard work that comes with starting and running a business.
“Many of these winners are small businesses - the backbone of our economy – and we are backing them to grow, increase their productivity and create more jobs and opportunity across the UK through our modern Industrial Strategy.”
Ruth Smeeth MP, Member of Parliament for Stoke-on-Trent North added: “I'm absolutely thrilled that the work of Carol and Kevin Shanahan and Synectics Solutions is being recognised. The Queen’s Awards is an incredible achievement for any company and is especially important for my constituency given the high-quality jobs and growth that Synectics Solutions brings to the town of Burslem.
“This achievement also represents the far wider contribution that Synectics Solutions makes to the community. The Synectics team have put so much time and energy into supporting the local community.
“I know from my own work with Carol and Kevin just how committed they and the whole Synectics family are to helping the local area. Whether it's their work with the local football club or supporting the Fit and Fed project delivering holiday clubs for children across Stoke-on-Trent, Carol is community champion in the truest sense. This recognition is richly deserved.”








