
Published

Germanas Kavalskis
Chief Communications Officer at Penki Kontinentai Group
Do you want to take a strong position in the field of financial services, to be successful, innovative, and attractive to investors? Become a FinTech. see more
- 04:00 am
Open your wallet and take out a coin or banknote and the Queen’s portrait offers a symbol of permanence and security – but are the days of cash numbered?
A growing number of people now never use cash preferring to use cards, electronic transfers or their smartphones to make purchases. And, according to a new research from ThoughtWorks, three in five adults (59%) think Britain will be a cashless society by 2030.
When quizzed about which monarch’s image will be the last to appear on a British banknote, astonishingly nearly 1 in 10 (9%) that foresaw a cashless Britain thought that Queen Elizabeth II would be the last, while half (49%) thought that cash will have disappeared by the time Prince William reaches the throne.
Phil Hingley, Director of Financial Services at ThoughtWorks UK commented: “This might be an amusing view of the way we pay for services but the serious message is that banks and consumers need to be prepared for the biggest change in currency since the first coin was struck from precious metal around 3,000 years BC and paper money appeared for the first time in the 11th century. The need for coins and paper banknotes representing value is fast disappearing. Whose portrait appears on Britain’s last banknote may be open to speculation. But that it will happen is beyond doubt.”
“Cashless transactions are rocketing and the UK has by far the largest number of payments made by card, phone or electronically in Europe, amounting to annual revenue of some €106 trillion per year. Some retail sectors – such as transport – are already almost entirely cashless and I see other sectors rapidly catching up. The question is, when will cash disappear from our pockets?”
The research took a tongue in cheek look at which monarch respondents thought would be the last to see their portrait on Britain’s coins and notes – a question that gives a sense of timescale until British becomes a cashless society.
Of the 59% who believe that cash will disappear, 9% believe that Britain will become fully cashless during our current Queen Elizabeth’s reign. Eight out of ten (12%) think Prince Charles will be the last when he becomes King while half (49%) thought that cash will have disappeared by the time Prince William reaches the throne.
Assuming that the monarchy remains, a fifth (20%), believe that Prince George of Cambridge who is third in the line of succession will be the last to grace British banknotes.
Asked whether they expect cash to disappear by 2030, Those aged 18-24 were most likely to predict a cashless Britain by 2030 (72%, compared to 51% of over 55s).
ThoughtWorks' report also asked which aspects of everyday personal banking would cease to exist by 2030. The majority of respondents thought the days were numbered for bank statements by post (64%), cheques (64%) and postal letters from a bank (45%). Respondents also predicted bank branches would change, 29% predicting that paying-in counters would be extinct by 2030, whilst 24% could imagine staff-less branches (24%). Overall, 23% of adults thought high street bank branches would be a thing of the history books by 2030.
Phil Hingley, Director of Financial Services at ThoughtWorks UK adds: “Consumer life in 2030 Britain will be very different with the advent of new tech. With coins extinct and paper currency on its last legs, consumers will be making instant payments from their mobile and wearable devices. Artificial intelligence will guide our buying decisions, restocking our shelves and giving answers to financial questions. Biometrics will diversify and expand how we inter-react: financial services products won’t sit outside our everyday lives, they will become integral to the lifestyle decisions we make.
“In this new cashless age, there will be a greater need for data security and safety. Whilst many predict the decline of the high street banks in the digital age, we predict the high street bank branch has an important role to play in tomorrow’s cashless society, but its role and purpose will change and the challenge for banks today is to reimagine the services they will provide in an age where cash has gone and the consumer’s top priority centres on the need for reassurance and safety on how their data is used and how payments are verified.”
- 06:00 am
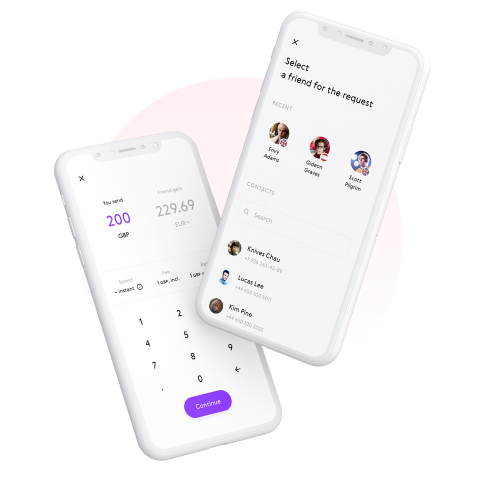
The launch of Paysend Link app is another innovation from payments disrupter Paysend, which is set to support a new way to send and receive money.
The new app builds on the services Paysend already offers, and will allow users to pay anyone in the world with just their mobile number.
Ronald Millar, CEO of PaySend, said: “We are constantly looking for ways to simplify and improve customer experience and make it even easier for the sender to initiate a transaction. Now all they have to do is provide a recipient’s phone number and click send.
"Forget about asking for bank details! Forget about double checking those details over and over again!”
With Paysend Link the recipient will see the incoming transfer and be able to direct it to any Visa, MasterCard, UnionPay card or a bank account (coming soon) of their choice, and start shopping or withdraw cash at any ATM worldwide.
Ronald added: “Besides being super convenient for the sender, Paysend Link also puts recipient’s worries at ease – they don’t have to send any personal information to a sender, only provide their phone number. Their personal information is entered directly into our secure platform.
"This sets a new standard when it comes to security and safety of customer data and financial information shared across borders. What’s more – it’s a recipient who decides where they want to direct the incoming transfer to – their bank account, debit or credit card.”
The service is available in the Google Play store and the Apple store.
The business, which has the only global card-to-card money transfer network, is trusted by over 700,000 customers around the world and currently operates in over 70 countries worldwide.

Jo Howes
Commercial Director at digital banking software provider at CREALOGIX
“Facebook’s announcement that it is to further extend its payment services should not see more
- 07:00 am

Version 3.1.2 of the Open Banking Standard enables enhanced features and functionality, extending beyond basic compliance with PSD2 and RTS regulation.
The Open Banking Implementation Entity (OBIE) is pleased to announce the publication of the latest Open Banking Standard, version 3.1.2 – including updates to the Customer Experience Guidelines (CEGs) and the Operational Guidelines (OGs). Both Guidelines include a number of minor changes and clarifications which have been made in consultation with participants in the ecosystem, and also include updated versions of the checklists.
This latest version helps banks deliver features and functionality that will enable them to move beyond basic compliance with PSD2 and RTS.
This update includes the following enhanced functionality:
- Proposition P2 (Two-way notification of revocation) to allow ASPSPs to notify AISPs in real-time via a web-hook whenever a customer revokes access to their account.
- Proposition P8 (Trusted beneficiary exemptions under SCA) to allow ASPSPs to accept a payment initiation without Strong Customer Authentication for PISP payments to a trusted beneficiary.
- Proposition P9 (Status of payment) to allow ASPSPs to provide more detailed and meaningful payment status back to the PISP, beyond just initiation.
- Proposition P22 (Corporate Accounts) to cater for accounts where more than one person needs to authorise account access.
Please see links below to the latest version of each component of the Open Banking Standard:
- Read/Write API Specifications v3.1.2
- Dynamic Client Registration Specification v3.2.0
- Customer Experience Guidelines v1.3.0
- Operational Guidelines v1.1.0
Propositions P2 and P8 are included in the published roadmap as part of Release 4, originally planned for implementation by September 2019. However, implementation timelines for Release 4 have not yet been confirmed, and further updates will be provided via the Open Banking Testing Working Group.
- 06:00 am
Cross River Bank (“Cross River”), a leading innovator and provider of banking services for financial technology companies, today announced that it has entered into a partnership agreement with RS2 Software, a global payments processing and technology provider. Together, Cross River and RS2 will provide merchants with a seamless, global payment experience for processing credit and debit card transactions, as well as digital banking for their workers and consumers.
“Cross River and RS2 understand that technology innovators demand regulated, secure payment solutions that address dynamic, ongoing changes in the marketplace,” said Phil Goldfeder, SVP, Public Affairs at Cross River. “In today’s global economy, payment needs are fast-evolving with merchants gravitating towards payment providers who offer broader multifaceted services in one place. We are confident that our best-in-class, compliant fintech banking services – combined with RS2’s industry-leading processing solution– will enable workers and merchants to succeed in the partner-driven marketplace.”
Under their agreement, Cross River and RS2 will work together to improve payment processing and enable push and pull transaction capabilities. The partnership will allow both physical and virtual merchants to receive settlement funds faster than waiting for traditional settlement periods. Fintech companies will also benefit from Cross River’s robust regulatory compliant platform that will enable companies to focus on innovating beyond legacy systems to create efficient card processing and banking capabilities and enable users to receive funds faster.
“RS2 embraces the complex elements of payments – multiple channels, payment types, countries and currencies – and transforms them into opportunity, growth, and innovation,” said Daniela Mielke, CEO of RS2 Software North America. “Cross River is an ideal, like-minded partner as they view the transformation of banking as a catalyst for offering breakthrough products and services, as well as unique payment capabilities that drive superior payments, thereby allowing businesses to optimize customer experiences and minimize the time, effort, and costs associated with managing their payment practices.”
- 08:00 am
Global payments provider Klarna has today announced that all its alternative payment options are available both in-store as well as online.
Klarna’s alternative payment options include:
- Shoppers can pay later, up to 30 days after delivery of goods
- Shoppers can pay for purchases in 3 equal instalments collected monthly
- For higher-ticket items, consumers can use Klarna’s consumer finance in 6-36 month payment plans
With the majority of retail transactions in the UK still taking place in-store, Klarna has made the move into physical retail to support the needs of multi-channel clients.
Klarna’s solutions will work with any connected smartphone. Customers can pay via their phone at the till by either scanning a QR code on the retailers’ screen or being sent an SMS or email with a payment link. They will then be able to fill out their information and select a payment method. Klarna makes a real-time approval decision, offering a smooth and seamless payments process for merchants and consumers choosing the high street over a screen.
Having access to deferred payments in-store means consumers can boost their purchase power right when they need it at the point of sale, take their items home the same day and repay how and when suits them.
In addition, for Klarna’s consumer finance service, the number of steps in the credit application process are greatly reduced compared to competitor offerings, while still remaining accurate and secure — with an average completion time of just one minute. This convenience and fast checkout experience increases conversion and sales for the merchant.
Luke Griffiths, General Manager at Klarna UK, commented: “Shoppers today want more control over their buying experience. Our mission is to make payments as seamless and stress-free as possible. We’re now bringing more payment flexibility to the in-store environment, so shoppers can move smoothly through the purchase journey, whether they choose to shop online or on the high street.”
- 07:00 am

If long term certainty was ever guaranteed that time is over. Today’s leading businesses face a disruption that cannot be ignored if they are to exceed expectations and navigate through the fog of uncertainty. Proactive and insightful, the most effective finance organisations of the future will be capable of driving the business forward and holding them accountable to business results all at a fraction of the cost of today’s finance organisations.
Finance in a digital world utilizes disruptive technology innovation, data and talent by using a new digital toolkit. The world of digital finance will be guided by a new breed of professionals that identify trends proactively and are equipped to rapidly address issues as they are identified and communicate the results of those efforts in a way that builds confidence in business leaders and shareholders by bringing actionable insights to the forefront on financial and transactional data. This is possible through predictive analytics layered on top of the data model. Transaction data is quickly stored virtually in the cloud and served up in near real-time via in-memory computing by using robotic process automation, blockchain and machine learning to do transaction processing, efficiency improves, control improves, accuracy improves, reducing the cost to serve and increasing margins helping finance run like the best production factory.
To thrive in this disruptive world of uncertainty finance organizations must leverage a new digital toolkit which can elevate the business to new heights, exceeding the expectations and improving the bottom line: finance in a digital world, lifting the fog of uncertainty.
Cognitive computing tools help identify what’s driving company’s performance and potential improvement scenarios and then model the financial impact these decisions could have on the business leading to optimize decision making and more efficient operations that support top line growth.
To know more visit - https://www.oec2019.com/
- 01:00 am
Lexmark, a global imaging solutions leader, announced that Thomas Valjak will join the company as Vice President Channel, EMEA, effective today. With almost 25 years of experience inbusiness management, channel and end-user sales, Valjak will help accelerate the company’s channel growth across the region of EMEA.
“The appointment of Thomas signifies our commitment to the EMEA channel and we’re thrilled to have such a recognised industry leader join our organization,” said Sammy Kinlaw, Vice President, Worldwide Channel and OEM Sales, Lexmark. “Thomas’ experience will be vital in helping us deliver our programmes and go-to-market strategy for the diverse network of partners we have across the region.”
Valjak joins Lexmark from HP, where he spent the last 24 years in different regional business leadership, sales and channel roles. Most recently, he served as Vice President and Head of HP’s Large-Format Printing business for EMEA where he was responsible for managing all aspects of its channel-driven business for customers in architecture, engineering and construction, commercial printers, sign makers and industrial manufacturers.
"I appreciate the challenges and inherent opportunities that exist in the EMEA channel and I look forward to bringing this insight to my new role,” said Valjak. “Lexmark is well positioned to capitalise on this huge market opportunity with its leadership, technology innovation and commitment to service excellence.”
- 06:00 am

Ideal Prediction, the independent trading analysis and data science company for capital markets, today announced the addition of Natural Language Processing (NLP) to its automated analytics services.
By incorporating NLP with machine learning, Ideal Prediction’s service empowers clients to create and visualize new analytical graphs in real-time with no coding knowledge.
Prior to NLP, all potential cases required programming, offering only a prescriptive set of limited analytics. By adding NLP, Ideal Prediction enables clients to visualize and analyze calculations beyond those available in an out-of-the-box user interface (UI). NLP provides a flexible structure, with which clients can define for themselves what they want to visualize, creating a fully self-customisable monitoring service.
“Analyzing data using NLP and machine learning is incredibly difficult to achieve, because of the almost limitless combination of words and analytical outputs, but it is incredibly powerful,” said John Crouch, Founder and CEO of Ideal Prediction. “Clients are really pleased with this new functionality, as they are able to immediately create bespoke analytical visualizations, simply and easily, with no development queue.”
Ideal Prediction announced the launch of Scope in February 2019. The service automatically monitors order and trade activity, evidencing that humans and algorithms adhere to governance and risk controls, specifically in line with the principles of the FX Global Code (FXGC).








