Published
- 09:00 am
Eventus, a leading global provider of state-of-the-art, at-scale trade surveillance software across all lines of defense, today announced that the firm has won the award for Best Market & Trade Surveillance Solution in the Digital Assets category in the Regulation Asia Awards for Excellence 2023. The awards were announced at a ceremony in Singapore last night.
The recognition for the firm’s Validus platform represents the second consecutive win in the category for Eventus and its third award in three years from Regulation Asia, which honored the company for Best Solution – Market Abuse & Surveillance in the 2021 awards. Eventus has now garnered nine awards specifically for its leadership in the Asia-Pacific (APAC) region in the past three years.
Eventus CEO Travis Schwab said: “We’re incredibly honored to receive an award from Regulation Asia for the third consecutive year – particularly given its rigorous evaluation process. We continue to see strong traction over the past year both globally and in APAC, signing our first clients in Japan and Taiwan, new clients in Australia, as well as several digital asset exchanges in Singapore and Hong Kong.”
Nearly half of the digital asset exchanges that have deployed Validus are in the APAC region. Schwab said the firm’s expertise in digital assets has been of particular importance in Asia, where regulators in separate jurisdictions are coming to different conclusions on how they will hold digital asset markets accountable. “Our regulatory experts closely track these developments to ensure Validus remains the premier solution for meeting the highest standards of surveillance in the asset class,” he said.
The Regulation Asia Awards for Excellence recognize financial institutions, technology companies, legal and consulting firms, exchanges and other players that help ensure the highest regulatory compliance standards are upheld in the financial industry. The research-based awards program includes an “intense selection process” over two months, conducted by Regulation Asia’s editorial team and a panel of 32 outside experts as advisors. The independent panel of judges includes subject matter experts from banks, associations, law firms, consulting firms and academia.
Regulation Asia is the leading source of actionable intelligence for APAC markets, with over 12,000 subscribers, including regulatory bodies, exchanges, banks, asset managers and service providers.
- 01:00 am

With only two weeks to go until the Park Christmas Savings season hits the peak for savers to start getting ready for Christmas 2024, PayPoint today announces that more than 1,500 members of the Federation of Independent Retailers (the Fed) have signed up to become PayPoint Park Super Agents, boosting their earning potential by over £1,000 per year.
Park Christmas Savings, part of the PayPoint Group, is the UK’s biggest Christmas savings club, helping over 350,000 families to spread the cost of Christmas, by allowing them to manage their household budgets better through the rising costs of living and boost their spending power through regular offers and discounts. Customers can access a wide range of gift cards and vouchers from over 140 of the biggest online and High St brands, including Argos, Primark, and B&M.
Every retailer that signs up as a PayPoint Park Super Agent receives access to an extensive support package, including training, digital and in-store POS, personalized saver communications, and a national £2.5m advertising campaign driving awareness which kicks off in December. By recruiting savers in their local area ahead of the festive period, retailers can earn over £1,000 a year in commission. This includes £10 for every new customer sign-up, 3% of all savings, and £5 for every customer that uses the scheme again next year.
Nick Wiles, CEO, PayPoint said: “Despite only launching Park Christmas Savings Super Agent proposition earlier this year, it’s great to see retailers’ continued enthusiasm for the programme. In addition to providing additional opportunities for retailers to earn, the service plays an important role in helping families budget ahead of the festive period and beyond, ensuring they can still have a memorable Christmas despite the current cost of living challenges.”
Muntazir Dipoti, National President, the Fed said: “Fed members are dedicated to continually improving their customers’ experience and supporting their local communities, which is why the Park Christmas Savings service is proving so popular. We’re proud to continue to work with PayPoint to offer this exclusive opportunity for our members and would encourage all our retailers to take advantage of the scheme and put their names forward to become a Park Super Agent.
PayPoint retailer Stephen Tate, Addisons News Agency (Stockton), said: “It’s never too early to start planning for Christmas, whether you’re a retailer or a customer. Since signing up to be a PayPoint Park Savings Super Agent, I’ve already seen significant demand from the local community who have taken proactive steps to begin saving for next year.”
“Key to this has been the POS and training support provided by PayPoint. The bespoke leaflets and posters have helped increase uptake and boosted the commission retailers receive.”
As a Fed member, new retailers who sign up to be a PayPoint Park Super Agent before 30 November 2023 will be entitled to a discount of 50% off PayPoint service fees on their EPoS Core package for the first six months.
- 04:00 am
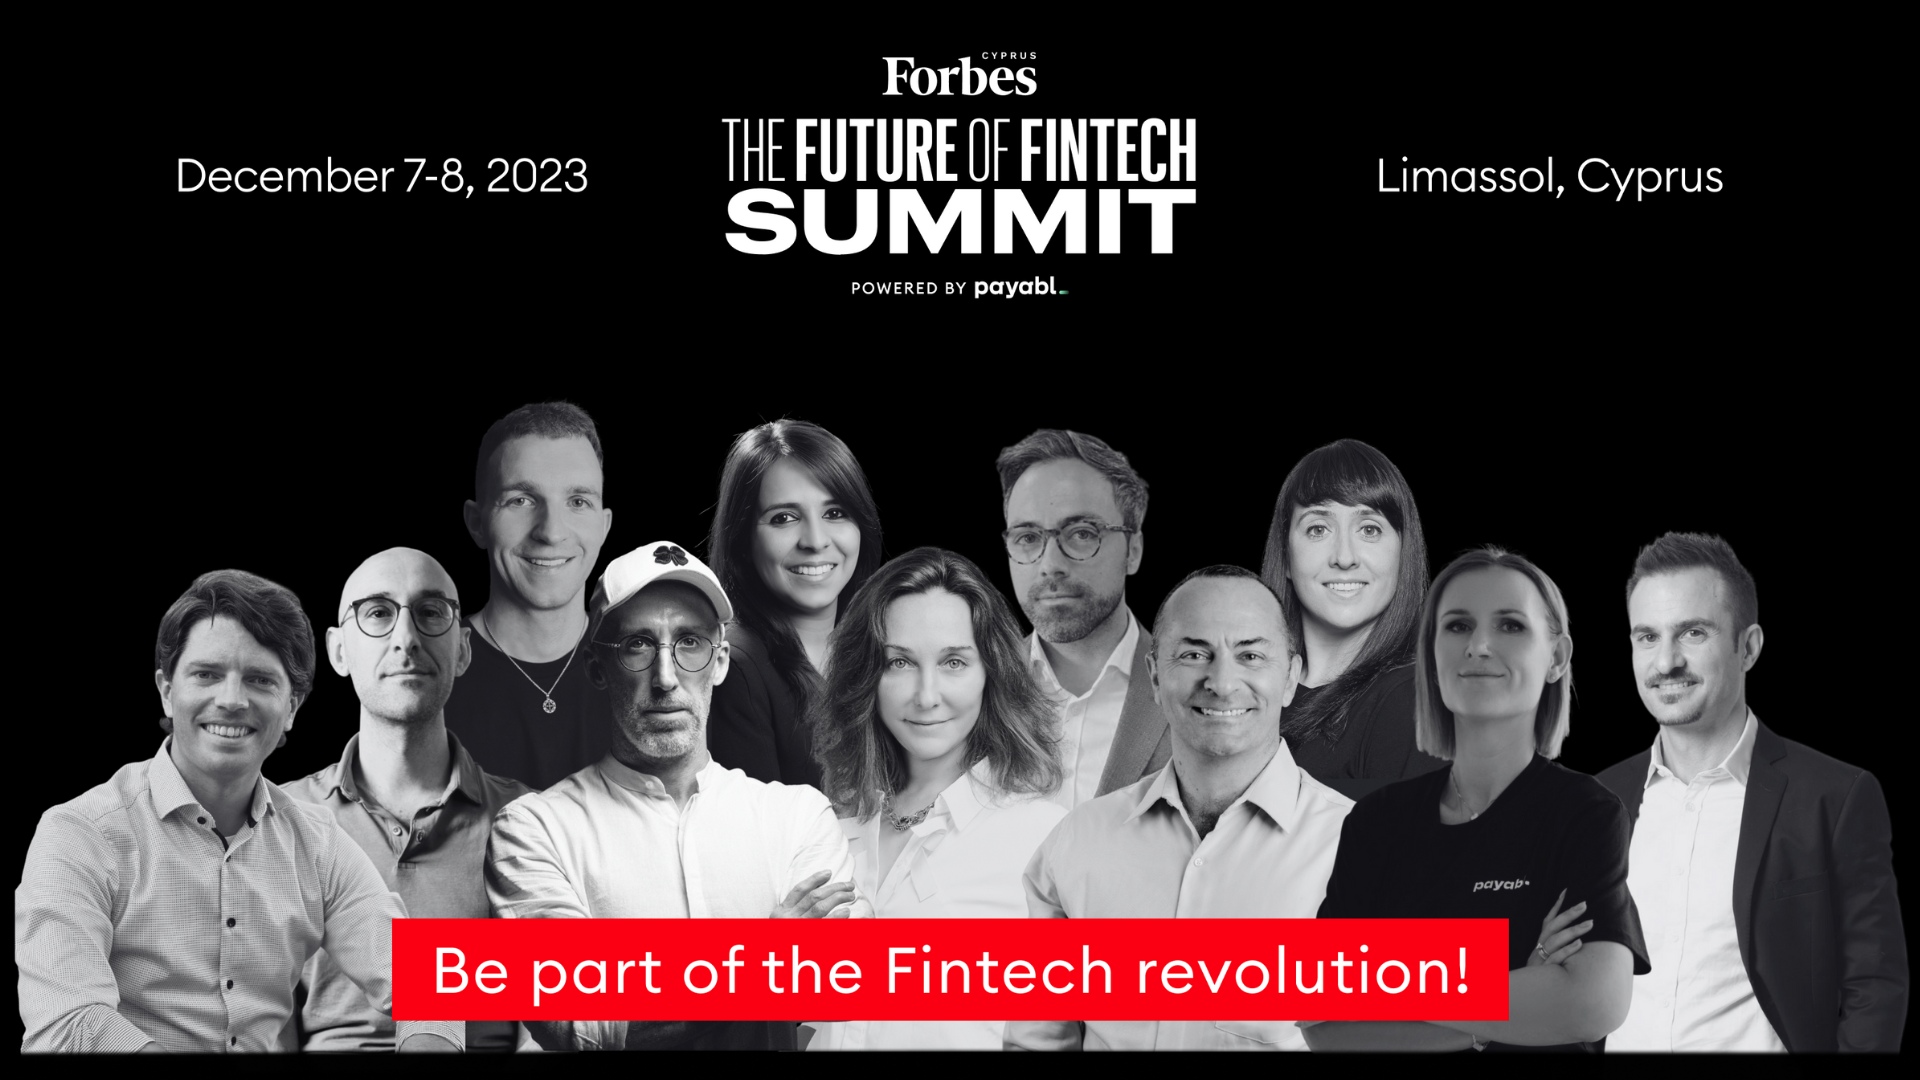
Forbes Cyprus is thrilled to announce the latest additions to the distinguished lineup of speakers for The Future of Fintech Summit, a premier global offline event powered by payabl. on December 7-8. This summit promises to be a gathering of some of the brightest minds and innovators in the fintech industry, providing a unique platform for thought leadership, networking, and collaboration.
The summit will feature talks and discussions from industry leaders, visionaries, and disruptors who have shaped the landscape of finance and technology. These speakers bring a wealth of knowledge and experience, offering insights into the latest trends, challenges, and opportunities in the ever-evolving world of fintech.
Confirmed speakers include:
Georg Hauer, fintech advisor, board member and investor, former General Manager at N26
Sarah Finegan, the investor at Antler, co-host of the podcast series “At the Cap Table”
Uri Poliavich, CEO of Soft2Bet, with over 13 years of complex industry experience
Umang Sota, the Head of Product at Checkout.com with a decade of experience driving innovation in Fintech
Andreas Vlachos, the Growth Manager in Greece and Cyprus at Binance
Pedro Batista, a Fintech Chief Executive Officer with 10+ years of experience working for Fortune 500 banking firms
Mila Khrapchenko, Co-CEO and Co-founder of Ameetee
Taner Akcok, the Head of API Banking at Deutsche Bank and an advisor at Boston Consulting Group Digital Ventures
Alexander Konovalov, Co-founder & Co-CEO of vidby, Ukrainian-born serial tech entrepreneur
Beny Rubinstein, advisor, strategy & innovation – Israeli Ecosystem Development
Simone Paul Tamussin, VP of Global Product Management & Development at Mastercard
Ugnė Buračienė, Group CEO at payabl., Country Ambassador for Cyprus at European Women Payments Network
Alejandro Repetto, an Argentine future thinker, technology entrepreneur, consultant, and professor
David Gyori, CEO at Banking Reports, top 10 global thought leader in fintech
Alex Mifsud, Co-founder and CEO of WEAVR.IO with 15+ years of experience
Meaghan Johnson, a researcher with 10+ years in the digital banking space, Fintech contributor at Forbes
Ben Goldin, an expert in digital banking and fintech with over two decades of experience, founder and CEO of PLUMERY
And many more!
As a special incentive for early attendees, Forbes Cyprus is offering a 15% Early Bird Discount on all tickets purchased before November 30, 2023. Don't miss this exclusive opportunity to secure your spot at The Future of Fintech Summit at a reduced rate. Simply use the promo code NOV15 during checkout. Act fast, as there are less than 50 tickets available at this discounted price.
To learn more about the event, explore the agenda, and secure your spot, visit the official Summit website: https://www.fintechexpo.eu/.
- 08:00 am
- A greater pivot to tech solutions from legacy debate is needed.
- The regulatory obsession with efficiency is premature.
- A roadblock of incentives means some things will never change.
- Technology needs to reposition and redefine the correspondent bank role.
- ‘High Risk’ classification needs an overhaul – via the ID Authentication Key.
- The convergence of XB and domestic will yield many easy wins.
- Liquidity optimisation – hidden gold?
- Economic reset is a double-edged sword.
- Crypto, CBDCs, Blockchain: not THE answer but a component.
- A central bank consortium would speed change.
Gary Palmer, CEO, Payall, said: “Every country, city and even remote villages, are touched by globalisation. The way we work, receive medical care, communicate, shop, pay and travel have all changed dramatically from technological transformations. Overall, just about every part of our lives are radically different than just a few years ago and unrecognisable from 50 years ago. Not so in cross-border payments. The question we must keep trying to answer is can money move at the speed of data globally? This whitepaper, completed through industry survey and interviews with leading experts, challenges the status quo with provocative questions, relevant research, news ideas and ultimately suggests that tech and new paradigms will transform the complex, high-risk and manual mess we call cross-border payments.”
Tony Craddock, Director General of The Payments Association, commented: “Payments continues to grow at a phenomenal rate and, within this, cross-border still represents a huge opportunity. This vital piece of research is key in illustrating how technology will be the key driver for the industry to reduce the amount of friction, so people keep more of their money and receive it faster.”
- 07:00 am
Redpin Holdings Limited - owner of leading global digital international payment services to private clients and SMEs Currencies Direct and TorFX – launches as it implements a new strategy to become the market leader in embedded software and payments for residential property.
The new strategy follows an earlier £140 million strategic investment from Blackstone Tactical Opportunities (“Blackstone”). Redpin plans to continue investing in its existing international payment network and services as well as grow through select acquisitions of property technology companies globally.
Arnaud Loiseau, formerly international CEO of WorldRemit (now Zepz) and Vice President at King, has been appointed as CEO of the new group to drive the new strategy, talent acquisition and M&A transactions.
Arnaud Loiseau, CEO of Redpin, said: “The residential property sector is home to life’s most important payments but also the most frighteningly complex and fragmented ecosystem in the world. Change is long overdue, and Redpin plans to connect the dots for consumers and businesses across the ecosystem – from legal service firms, title companies and estate agents to property managers – by providing a seamless SAAS* and international payment experience”.
“I am excited to scale a business that can make a real change in a huge market ripe for disruption and partner with world class private equity investors and the brightest minds and companies across fintech and proptech.”
Qasim Abbas, Senior Managing Director at Blackstone, said: “Today’s announcement marks an exciting next chapter for Redpin as it sets out to transform international payments and vertical software for the residential property market, an industry that has historically been underserved. With our backing, alongside that of Palamon and Corsair, we look forward to seeing what Arnaud and the team will achieve in attracting some of the world’s top software and technology talent, and proptech companies seeking to bring innovation to the industry.”
Ali Rahmatollahi, Partner at Palamon, and Raja Hadji-Touma, Partner at Corsair commented: ”We are delighted to have Blackstone alongside us at this pivotal moment in the company’s history as Arnaud and team leverage Redpin’s incredible market position and growth profile built over the past 8 years to transform the residential property sector. We are confident that Redpin is well-positioned to become a category-defining company and are pleased to be supporting the team in reaching its global ambitions.”
New strategy
A scale-up with significant backing and established consumer-facing brands garnering industry-leading Trustpilot scores, Redpin operates a global payment network that securely serves customers and SMEs in over 235 territories across over 1,800 currency pairs, transacting more than $12.6 billion in the last financial year.
Headquartered in London, the company employs over 800 colleagues operating across the UK, EU, USA, South Africa, Australia, New Zealand and India.
Through acquisitions, new partnerships and new product development, Redpin plans to scale its offering beyond its existing international payment and industry-leading customer service to include best-of-breed vertical software services to legal service firms, title companies, property managers, escrow and estate agents. The total addressable market for the residential property sector has flows of $4.5 trillion per annum, of which $180 billion are in foreign exchange alone, according to Redpin analysis.
New leadership and backing
Arnaud Loiseau has been appointed to lead the new Redpin Group as CEO and executive board member. Arnaud joined from Worldremit (now Zepz), a leading digital international money transfer group, where he was CEO, International. There, he led the non-US P&L of the business, had global ownership for product, marketing, business development, payment and pricing functions and was part of the executive management team that led the $292M Series E and acquisition of Sendwave in 2021. Prior to this, Arnaud was Vice President at King - the developer of Candy Crush and issuer of $7Bn IPO on NYSE before its subsequent sale to Activision - holding various senior roles in new product, corporate development, strategy and publishing.
Arnaud also gained extensive M&A and Corporate Development experience at UBS Investment Bank, Bertelsmann and Reuters and holds an MBA from Harvard Business School and MEng from Ecole Polytechnique in France.
In line with Redpin’s ambitions, Arnaud will lead M&A transactions and scale product and technology talent to create a new category leader in payments and vertical software for the property industry and beyond.
The launch of Redpin follows a £140 million strategic investment from funds managed by Blackstone Tactical Opportunities, which was made in partnership with existing investors Palamon Capital Partners, a pan-European growth investor, and Corsair, a leading private equity firm targeting services, software, and payments investments in the financial services market.
- 02:00 am
New research by FICO suggests that Authorised Push Payment fraud — when someone is tricked into sending money from their bank account to a fraudster — is not being taken seriously by UK consumers. The new data also suggests one of the most vulnerable sections of society — the 65+ age group — is the least worried by this form of financial fraud.
The latest UK Finance Report shows a 22% rise in cases of APP fraud, yet new FICO research reveals that 31% of consumers surveyed rank it as the type of fraud they feel the least threatened by. Despite this, nearly 40% of respondents rank people being tricked into sending money to a fraudster — a description of APP fraud — as the type of fraud that they believe has the highest losses.
It seems there is a disconnect between consumers’ understanding of potential financial losses through APP fraud and their perception of the threat to themselves. The implications for older people are concerning, while people of any age can be victims, certain frauds such as pension investment scams target this age group.

James Roche, a principal fraud consultant at FICO, believes the lack of consumer awareness of the risks of APP fraud needs to be addressed through effective customer communication. Financial service providers should also continue to focus on innovation and real-time prevention measures.
“Despite the work carried out by payment service providers to address vulnerabilities in their fraud prevention systems, our research strongly indicates that more needs to be done to communicate the real and present danger of APP fraud to customers,” said James Roche.
“Consumers understand that APP fraud is costly, but it appears they think it is a crime that won’t happen to them. Recent moves by the regulator such as increasing the pressure on banks to re-imburse victims, may also be reducing caution. When people are reasonably sure that they will be paid back any losses to fraud, they might be less likely to ask if they really should be making the payment.
“Payment service providers must up their game and get the message out to their customers that, despite the introduction of steps like Confirmation of Payee, fraudsters adapt and grow and APP fraud should still be a huge concern. Financial institutions also need to make better use of AI and machine learning tools to prevent incidences in the first place.”
- 02:00 am
Appian is proud to announce the winners of its 2023 International Partner Awards at the Appian Europe conference in London. These prestigious awards recognise partners who have demonstrated exceptional dedication, innovation, and excellence in leveraging the Appian Platform to deliver transformational business value to clients through end-to-end process automation.
"These exceptional partners have successfully delivered excellent business outcomes with our European customers by implementing process automation with the Appian Platform,” said Christopher O'Connell, Vice President of Partners & Alliances. “This year’s winners have showcased unwavering commitment, innovation, and transformative power by partnering with Appian. We're proud to recognize their achievements at the 2023 Appian International Partner Awards. Their dedication and passion for excellence exemplify the values we hold dear at Appian, and we look forward to further collaboration in the journey of innovation and transformation."
The winners are as follows:
Delivery Award - EY
EY Italy is the proud recipient of the Delivery Award, which acknowledges their unwavering commitment to excellence and project delivery for an Italian energy customer. EY Italy's innovative project management, attention to detail, and seamless integration of the customer's unique needs into the solution led to transformative outcomes. Their deep understanding of Appian's capabilities and passion for delivering exceptional value has accelerated project timelines and enhanced the overall quality of deliverables.
Innovation Award - KPMG UK
KPMG's end-to-end Customer Due Diligence (CDD) service reduces the average case handling time and improves the first-time resolution of cases, allowing global banking institutions to focus back on the core parts of their business. KPMG leverages the Appian Platform to implement continuous improvements and customer data insights throughout the lifetime of the engagement. KPMG ensures a customised and rapid implementation of the CDD service, tailored to each client’s specific business needs. KPMG has built over 5,000 reusable Appian objects and with their onshore/offshore Appian delivery capability has reduced end-to-end platform build time by 40%.
Growth Award - Minsait, an Indra Company
Minsait receives the Growth Award for their remarkable expansion of the Appian practice. In the past year, they increased the number of globally certified practitioners by over 25%. Minsait's commitment to education is evident through its internal training practice, which has successfully educated more than 200 students, and its collaboration with local universities to certify 100 additional consultants in 2024. To support their growth, Minsait has established a Centre of Excellence, extending their expertise across Europe, LATAM, and the Philippines.
Transformation Award - PwC Spain
PwC is the recipient of the Transformation Award for their remarkable project at one of the top 10 insurance companies in Europe. PwC's comprehensive transformation involved decommissioning the customer's legacy platform and migrating all applications (which serve over 25,000 users) to the Appian Platform. This transformation enables the customer to handle complex workflows, develop new applications, and adapt to future business needs with agility.
Partner of the Year for EMEA Channel Sales - VASS
VASS is recognised as the Partner of the Year for EMEA Channel Sales in acknowledgement of their outstanding contributions to Appian's growth and success in the region. As a leading provider of transformative digital solutions and consulting in 22 countries on 4 continents, VASS has achieved the highest annual contract value (ACV) in the region through close partnership and collaboration as an Appian reseller.
These awards represent the exceptional work of our partners in harnessing Appian's capabilities to drive innovation and transformation for clients across Europe. Appian is proud to work with partners who share our commitment to excellence, and we look forward to continuing to build on these successful collaborations in the future.
Congratulations to all the winners of the 2023 Appian Europe Partner Awards. If you would like to find a local partner or become one, please do visit our website to learn about the Appian Partner Program.
- 09:00 am
TrueLayer, Europe’s largest open banking payments network, has appointed Sebastian Vetter as Country Manager to lead the company’s push in Germany as the market matures for open banking payments.
Before joining, Sebastian was at Payoneer where he led the go-to-market activities for SMEs in Germany, Austria and Switzerland, with a focus on import/export businesses in manufacturing and ecommerce, marketplace sellers and professional service providers.
Prior to this, Sebastian was at Mangopay for over 6 years. He first established the DACH region in 2016, where he and his team grew transaction volumes from €10 million to over €500 million in just 3 years. He then went on to help launch local offices in the Netherlands, Nordics and Poland, overseeing the further growth, localisation and alignment of these markets under a new North-Eastern EU region.
This news comes off the back of exponential growth for TrueLayer in Germany, with total payments volumes doubling year on year since 2021. TrueLayer has also recently stated that their Payouts product has reached a 99.3% success rate in the country, along with a coverage of over 93% for instant payments.
Sebastian joins at a very exciting time for EU payments, with regulatory changes afoot in PSD3. At the same time, a commercial space is emerging via the SEPA Payment Account Access scheme, which will bring open banking-based A2A payments to European ecommerce.
Sebastian Vetter, Country Manager Germany, at TrueLayer, said:
“It’s truly a perfect time to join TrueLayer given their strong momentum in transaction volume and conversion growth and an increasing appetite for open banking/finance services within Germany and Europe as a whole. We have experienced a significant shift in the banking sector’s perception and adoption of open banking over the last few years, and consumers are becoming more and more aware of the benefits they will be able to reap from it.
I am thrilled to start working alongside an incredibly talented international team to deliver innovative value for both consumers and merchants on a path to a more secure, standardised and open future of payments.”
Commenting, Max Emilson, Chief Commercial Officer, at TrueLayer, said:
“I’m extremely excited to welcome Sebastian to the TrueLayer team. His track record of seriously scaling commercials in the region, while at the same time localising payment product offerings is unmatched. With the way things are shaping up for open banking payments in Germany, this is going to be invaluable for us as we continue to grow adoption in the region!”
- 04:00 am
nCino, Inc., a pioneer in cloud banking for the global financial services industry, today announced a strategic partnership with OneSavings Bank (OSB) to provide the institution with a cloud-based single platform that will help streamline traditional banking processes such as underwriting and loan origination. The partnership will support OSB as it further innovates its mortgage and lending operations via technology investments while maintaining a high level of customer service and regulatory compliance.
OSB, part of OSB Group, is a leading specialist mortgage lender, primarily focused on carefully selected sub-segments of the mortgage market such as Buy to Let; Residential, including Help to Buy and shared ownership; complex commercial and semi-commercial; development finance; bridging; and asset finance.
The UK mortgage industry is facing several challenges, including evolving customer demands and rapid changes in regulations. To add to this, many providers have outdated legacy IT systems that hinder their ability to adapt quickly when faced with shifting economic conditions or changing interest rates. This leaves many lenders without the flexibility or agility they need to handle new demands.
OSB are taking an active leadership position in the UK lending market by implementing the nCino platform to enhance the efficiency of its lending processes. Through the partnership with nCino, OSB will gain a fully configurable, single-platform solution that will create agility in its lending practices and provide flexibility to continuously monitor the economic environment, pivot at speed and adjust itself accordingly while providing a superior experience for its customers and brokers.
“Our goal is to be recognised as the UK’s number one choice of specialist bank through our commitment to exceptional service, strong relationships and competitive propositions, helping customers, colleagues and communities prosper. I’m looking forward to the journey ahead of us with nCino and the added flexibility and agility we will gain by implementing the platform,” said Matthew Baillie, Group Chief Transformation Officer at OSB Group.
"nCino will enable OSB to further streamline its lending processes and drive efficiency while maintaining focus on providing outstanding customer service,” said Thomas Chaplin, Head of Mortgage Product, EMEA at nCino. “By leveraging the power of a single platform, nCino can help mortgage providers, borrowers, and brokers alike to benefit from enhanced efficiency and transparency throughout the entire lending process. The exciting partnership between nCino and OSB are just the latest example of this tech-driven revolution that is modernising the mortgage industry in the UK and we’re incredibly proud to be partnered on this initiative.”
- 05:00 am
Juniper Research unveiled today the 10 trends that are set to radically impact the fintech and payments landscape in 2024, included within its latest whitepaper.
The whitepaper found that the fintech market is undergoing a rapid shift, with the rise of new technologies, such as Open Finance, generative AI, and A2A (Account-to-Account) payments having a major impact on business models. This is combined with unprecedented competition to be ‘top of wallet’ for customers, making the market more competitive and uncertain than ever.
Top 10 Fintech & Payments Trends 2024
The trends are as follows:
- A2A Payments to Challenge Cards in eCommerce and for Funding Wallets
- CBDC Use Cases to Emerge in Practice
- Generative AI in Banking to Transform Spending Insights
- Digital Identity Adoption to Be Catalysed by Digital Wallet Integration
- AML Tools to Better Leverage AI as Alternative Payments Complicate Compliance
- Sustainable Fintech Solutions to Emerge, as ESG Compliance Tops Agenda
- FedNow to Fail to Match Instant Payments Success, but VAS to Flourish
- Mobile Financial Services to Accelerate Transition to Banking Tech Services
- Biometric In-store Payments to Surge, as Checkout Innovation Rises
- B2B BNPL to Provide Critical Financing for SMEs
Juniper Research's VP of Fintech Market Research, Nick Maynard, commented: “The fintech and payments market is undergoing fundamental changes, with new payment methods and different business models threatening to completely uproot existing operations. Stakeholders must fundamentally reassess the viability of their offerings, and build ambitious roadmaps for future developments, or they will be left behind by more agile competitors.”