
Published
- 08:00 am

GTreasury, a treasury and risk management platform provider, today announced that Yinson Holdings Berhad (“Yinson”) has been named the Best Treasury Transformation Project in the 2022 Adam Smith Awards Asia. Judged and awarded by Treasury Today, the annual Adam Smith Awards acknowledge exceptional corporate treasury achievement across several categories. The awards remained extremely competitive, with 416 organizations submitting nominations.
Yinson’s successful treasury transformation included the adoption and deployment of GTreasury’s modern, SaaS-based treasury management system. GTreasury’s solution enabled Yinson’s treasury team to achieve best practices across cash management, payments, risk management, and hedge accounting. The extensible, API-driven solution also empowered Yinson to easily connect to its internal and external systems much more efficiently than via legacy—and much more manual—processes.
“Yinson is a great example of how a smart treasury transformation strategy can have a quick and extensive impact across an entire organization,” said Robin Heller, Chief Customer Officer at GTreasury. “The team at Yinson identified treasury functions and capabilities that were ripe for broader process automation, faster connectivity into business-critical financial data, and complete real-time visibility into cash and liquidity positions. We commend Yinson on its well-earned Adam Smith Award, and are proud to have played a role in Yinson’s treasury digitalization story.”
“It’s an honour to earn Treasury Today’s recognition in such an important category,” said Ong Ken Yong, Yinson’s Head of Corporate Treasury. “The capabilities and efficiency of our treasury operation are critical to our success, and to how quickly we can adapt to meet ever-changing market forces. We look forward to continued collaboration with GTreasury, and thank Treasury Today for naming us the best treasury transformation project of the year.”
Yinson joins Keurig Dr Pepper (KDP) and Micro Focus as GTreasury customers who have earned distinction from Treasury Today in 2022. KDP and Microfocus earned Adam Smith Awards in the United States for their GTreasury implementations around FX and cashless netting, respectively.
- 04:00 am

As the threat landscape continues to evolve and become more mature, cyber security has become more important for businesses in every sector but for financial services organisations establishing the right cyber security posture is paramount with businesses in the sector falling victim to cyber security incidents approximately 300 times more than other industries.
This is just one of the statistics uncovered in the latest whitepaper from cyber security and cloud experts Yobah Limited. The report ‘Cyber Security Solutions That Just Add Up’ explores the importance of cyber security for financial services business, the 5 key threats facing the industry and how to create a solid defence.
Bringing together specialist financial services and fintech expertise and cyber security knowledge the paper provides practical guidance for addressing threats including phishing, ransomware and crypto-jacking and the importance of deploying cyber security defences such as zero trust and identity-led security.
For an industry which handles high volumes of sensitive data, financial services are an extremely attractive target for cybercrime and falling victim to an attack could lead to unrecoverable reputational, financial and legal damage.
Speaking on the whitepaper, Yobah CEO and Principle Security Consultant Paul Sanders said:
“It is essential that financial services organisations establish the right protections to defend their businesses from the negative consequences of an attack. In this guide, we highlight the risks but critically we address how to remove them and arm businesses with the knowledge and support they need to tackle financial services targeted cyber threats head-on”
Yobah is a cyber security and cloud specialist delivering comprehensive security solutions specifically designed to defend the financial services industry, seamlessly protecting systems, applications and networks.
To read the whitepaper please visit https://content.yobah.co.uk/looking-to-fortify-your-cyber-security-defences
- 03:00 am
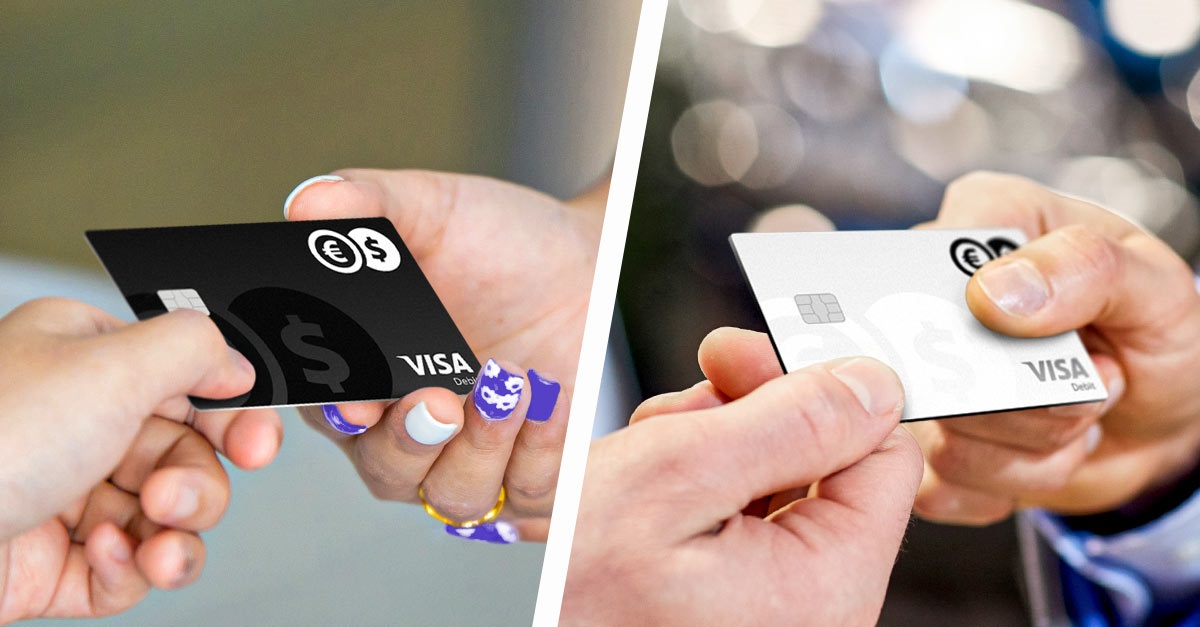
The fintech Conotoxia launches a multi-currency card 2.0. The new product makes it possible to share cards with, for example, family members or company employees.
Users of the global fintech Conotoxia can now order and share their cards with others. Owners of the multi-currency 2.0 card can easily pass the card on to others in the mobile app or web panel and top up the account. After a free, swift registration, other people can use the new product as they wish.
This novelty from fintech allows the card to be used by the family (e.g. children, husband or wife and senior members) or business associates. The owner of the plastic version of the card, i.e. the person ordering it, has a preview of the account on their profile. Therefore, they can share the balance (e.g. with their spouse) or control expenses and set limits, which is essential, for example, in the case of pocket money for a child.
"We have been observing very strong interest in our multi-currency cards. Customers recognise their advantages and their superiority over bank debit cards. The multi-currency card 2.0 and its new functionality can mean significant savings for families and businesses, as well as, for example, an interesting gift for those travelling abroad or shopping in international shops", says Piotr Kicinski, Vice-President of Conotoxia.
Conotoxia provides multi-currency cards in virtual and physical form with the delivery option not only by post but also by courier and - as the Polish-based fintech was the first to offer on the market - to parcel lockers. Residents of almost all European countries can order them. Cardholders gain access to free accounts in the euro and 19 other currencies and can pay in more than 160 currencies. They can pay contactless with their smartphone, watch and wristband, thanks to Apple Pay, Google Pay, Fitbit Pay and Garmin Pay. The fintech offers the Conotoxia mobile app for iOS and Android to handle cards, among other things.

Brad Hyett
CEO at phos
Future proofing payment offerings for customers has been a priority for retailers and merchants alike over the Christmas period, and as we embrace a new year. see more
- 05:00 am

Clarity AI – the leading global sustainability tech platform – announced today that Klarna, the global leader in the generational shift away from credit cards, is using Clarity AI’s data and capabilities to promote environmentally conscious brands to 150 million shoppers.
“We are thrilled to empower over 150 million shoppers with the information they need to make more sustainable choices when they shop”, said Angel Agudo, Head of Product and member of the Board of Directors of Clarity AI. “With more than 2 million daily transactions processed by Klarna, this initiative can have a significant collective effect, showcasing the scale and potential that Clarity AI can power and unleash as we make our sustainability metrics accessible to consumers.”
Sustainability is becoming a major concern for shoppers. Yet, so far, much of the attention in the market has been focused on the fashion industry. In order to shed light on a new category, Klarna will initially feature ways to shop consciously – powered by Clarity AI’s capabilities – to those shopping for electronics across thousands of brands in 22 countries around the world. As a whole, the technology industry is expected to produce around 14% of global emissions by 2040, up from around 3% today. As well as the energy demand from the usage of electronic devices, their production and disposal have a significant environmental impact. Producing these devices equals or exceeds the carbon cost of using them.
According to the Q3 2022 Klarna Shopping Pulse, 62% of US shoppers say that sustainability when shopping for electronics is important to them (e.g., that the product is made of more sustainable materials or the brand is taking active steps towards climate change). Also, the study showed that over two-thirds of Americans think it’s important that the brands they buy actively combat climate change and use recycled or sustainable materials in their products, and moreover, 24% of Americans actively seek out brands that are ethical and sustainable.
After consumers make a purchase in the electronics category, new Clarity AI-powered information on the brand’s environmental efforts will be displayed in the form of brand badges, bringing together brand level sustainability data in one simple overview. This information provides consumers with a simple and reliable way to identify brands that are proactively addressing climate change, helping consumers shop more consciously. The brand badges indicate whether a company has lower greenhouse gas emissions than similar businesses, whether they derive a higher proportion of its energy from renewable sources, has climate change policies and a roadmap to positively impact climate change, and whether or not a company is transparent in its reporting of climate-related information.
“In 2021, Klarna introduced the CO2e emissions tracker, which brought to life one of the largest awareness efforts on carbon footprints ever made. Now, we are taking it one step further by providing Klarna’s more than 150 million shoppers with reliable and transparent metrics for electronics brands, helping shoppers to not only understand the impact of their purchases but also to make more environmentally conscious decisions going forward. Together, Klarna and Clarity AI are empowering consumers to ‘vote with their wallet’ for a more sustainable world,” said Salah Said, Head of Sustainability at Klarna. “We were looking for a partner that not only provides clear and independent data, but also offers a seamless technical integration. As a digital-native tech company, Clarity AI was a natural choice for us. We speak the same language; it’s a great match.”
- 08:00 am

Worldline, a global leader in payments services, has announced a new service to help satisfy rapidly increasing customer demand in the travel sector for ‘Buy Now Pay Later’ (BNPL) payments. The company has partnered with leading travel payment provider Fly Now Pay Later and the joint offering is available through Worldline’s existing TravelHub payment solution.
BNPL is an instalment payment solution which allows consumers to make purchases and pay for them over a period of time. Industry data indicates that 68% of travellers will spend more than usual on their travel plans and 49% will buy ancillary services when BNPL is available [source: Amadeus]. Consumers are able to enjoy the convenience of lower upfront costs, reduced or zero interest charges and more available travel cash – giving them a much smoother user experience.
Merchants benefit from a higher conversion rate, improved average order value, and an increase in direct bookings by offering BNPL at checkout. The service also helps reduce fraud as travel providers receive their total payment upfront from the BNPL provider. The service is available for merchants who are connected to TravelHub, Worldline’s payment technology specific to travel merchants offering over 150 payment methods and currencies, multi-acquiring, tokenisation and a range of fraud prevention services, available through a single integration with single reporting and settlement. Established TravelHub merchants can make use of the service straight away, through a simple two-step process, by adding a button to their checkout page and signing a contract with Fly Now Pay Later.
Damien Cramer, Global Head of Airlines and Travel at Worldline: “We’re excited to ensure that travel merchants can now benefit from the growing popularity of the Buy Now Pay Later phenomenon. Ultimately, through this service, merchants are well placed to gain additional customers attracted by the ability to spread a load of their holiday expenditure, while still enjoying the security of receiving a single up-front payment from the BNPL provider.”
Jasper Dykes, founder and CEO at Fly Now Pay Later: “As a dedicated team of travellers committed to making paying for travel simpler and fairer, we are delighted to announce the partnership with Worldline as a highly respected pioneer in secure payments and trusted transactions. We’re all about making sure that travel payments work for everyone, so welcome the opportunity to work with merchants to help their customers spread out the cost of a hotel, flight or holiday.”
- 04:00 am

Mphasis, an Information Technology (IT) solutions provider specializing in cloud and cognitive services, announces that it has signed a partnership with Be Informed, a digital transformation platform for the intelligent automation of knowledge work and complex decision-making.
Mphasis and Be Informed will combine their capabilities to deliver high-end decision-support solutions in regulatory and policy encoding to public and private sector organizations in highly regulated industries, focusing on banking, insurance, travel, logistics, and healthcare. Under the terms of the agreement, Mphasis will provide domain-specific knowledge to enhance the partnership’s software, adding machine-learning capabilities to the combined offerings and helping with the effective implementation of solutions for clients.
With vast amounts of frequently evolving laws and regulations, it is challenging for organizations to keep track of all changes and ensure compliance. In 2020, companies across 190 countries had an average of 257 regulatory alerts per day, and this number is multiplying, given the large pipeline of further regulatory changes for industries to navigate. For instance, following the UK’s exit from the EU, the UK Government has suggested a gradual transition from retained EU law in financial services to requirements more tailored to the UK market. Today’s ecosystem depends on lawyers to interpret regulations, but with many hundreds of interconnected documents required to deliver a complete picture, there was a gap in the market for a solution to streamline and optimize the process.
The partnership will introduce new standards for legal knowledge representation and develop tools, methodologies, and automation capabilities to support the analysis and interpretation of regulations, policies, and contracts. Designed to work together, the tools will include a library comprising legal documents, regulations and policies pulled from numerous sources and standardized; a workbench platform to automate the process of interpreting and validating them and help identify any policy gaps; and a compliance engine for implementing these explicit interpretations of contracts, regulations and policies as rules. The cost and efficiency of compliance will improve dramatically as the policy workbench gains acceptance.
The partnership will initially focus on:
- Contracts as data: encoding contracts into explicit interpretations to help organizations radically reduce the cost of managing and servicing their portfolio of contracts
- Regulations and policies as data: encoding regulations and policies into explicit interpretations that can be implemented in business processes and applications to increase efficiency, agility and transparency of business processes and reduce life-cycle costs for applications
Based in the Netherlands, UK and the US, Be Informed chose to work with Mphasis due to its deep domain expertise across financial services, logistics and other highly regulated industries across the UK, Europe and globally. Mphasis specializes in delivering tailored next-generation solutions to organizations looking to automate knowledge-intensive regulatory and policy encoding work and comply with complex regulations. The Mphasis NextAngles platform, which will be implemented as part of the partnership, is built on the same semantics-based technology as Be Informed and can deliver massively scalable compliance solutions.
"The relationship between a government and its regulated entities has increasingly become entangled in a maze of rules that no one understands anymore. Understanding this challenge and with the vision to support the knowledge workers, we have been working with our partners and leading researchers to solve this problem since the early days of Be Informed. That we can continue this journey together with Mphasis makes us very excited and proud. Together we will work on a solution that improves regulations, reduces administrative burden, increases citizen participation, and lowers the cost of compliance." said René Louter, Chief Executive Officer, Be Informed.
“We are pleased to partner with Be Informed to create a new type of policy ‘metaverse’ intended to add significant value to the capabilities of highly regulated public and private sector clients in how they monitor - and adhere to - policy changes,” said Srikumar Ramanathan, Chief Solutions Officer, Mphasis. “Mphasis has a strong track record of working with many financial institutions to implement new regulations and addressing consent orders by applying cutting-edge digital technologies, which gives us an edge in understanding exactly what it takes to encode regulations and policies. Our vision is aligned with Be Informed, and together we are bringing our complementary strengths to develop innovative solutions to help organizations in highly regulated domains reduce costs and increase efficiency while delivering superior customer service and ensuring compliance.”
For some of the offerings being brought forward by the partnership, Mphasis and Be Informed will work with the Leibniz Center for Law, a collaboration between independent research organization TNO (Organization for Applied Scientific Research) and the University of Amsterdam, which applies computer science and artificial intelligence to the field of law.
- 04:00 am

DPA SmartCloud IFSC Private Limited, a wholly owned subsidiary of Decimal Point Analytics (DPA), has become India’s first ever fintech start-up to be authorised as a ‘Fintech Entity’ by the International Financial Services Centres Authority (IFSCA),the omnibus regulator of the financial SEZ at Gift City, Gujarat.
The authorization will enable DPA SmartCloud to offer AI-ML-driven solutions, products, andend-to-end data management services on the Cloud.DPA SmartCloud will serve a wide range of financial services firms globally and provide them access to better quality services at a lower cost, along with benefits that come as part of aCloud solution.
Speaking on the development Mr. Shailesh Dhuri, CEO of Decimal Point Analytics, said, “With this authorization, we are all set to launch an extensive bouquet of AI-ML driven products and services over the Cloud that match the requirements of our BFSI client base across the USA and Europe. The offerings from DPA SmartCloud will help us to expand into newer markets and cater to a diverse client-base, who in-turn, will benefit by leveraging our AI-ML driven solutions, all housed under one roof, to make strategic business decisions.”
DPA SmartCloud would be an integrated Software as a Service (SaaS) platform, which would host several AI-ML-based data management and analytics solutions and products over the Cloud. AI, ML and Cloud have been the buzzwords going around for a few years now and organizations across the world are exploring ways to implement such solutions to gain even the slightest competitive advantage. Some of the most common challenges faced by BFSIs and particularly Asset Managers are managing large amount of data, ingestingand integrating data from several sources, cleaning and validating the data, structuring of unstructured data to generate insights and training and deploying AI models to ensure accurate results. DPA SmartCloudwould provide Asset Managers access to a comprehensive data management platform with automated data ingestion, data standardization, advanced quality check measures, and more. The cost and implementation time dimension of AI platforms are constant worry for asset managers looking for alpha edge.
Mr. Dhuri further added, “Financial services firms require fast, reliable, and cost-effective data analytics products and data management services to convert data to business value. Cloud-based AI-ML solutions are the need of the hour to address the needs of these firms. However, developing thesesolutions is a costly affair due tohigh infrastructure setup costs along withthe availability of talented and experienced personnel needed to develop them. DPA SmartCloud would allow financial services firms to implement customized AI-ML-based solutions based on their specific requirements at a fraction of the cost and time needed to set up an inhouse system. This, we believe, is a win-win for all stakeholders.”
Mr. Dhuri further added, “The Gujarat International Finance Tec-City (GIFT City) is India’s first International Financial Services Centre (IFSC) and IFSCA is the unified regulator tasked with regulating financial products as well as financial institutions in GIFT City. IFSC will be the country’s portal to the world catering to institutions and individuals outside the Indian jurisdiction, dealing with finance flows, financial products, and services across borders.The vision encompassed in IFSC is to play a pivotal role in international finance across the globe, and Decimal Point Analytics believes that DPA Smart Cloud will be one of the key enablers to give the technological edge to the IFSC.”
- 01:00 am

Securities brokerage CGS-CIMB Singapore has switched on its connection to the private market exchange ADDX, giving all individual accredited investors on its platform access to ADDX’s offerings.
Through the partnership, CGS-CIMB was able to expand its shelf of private market products considerably. The brokerage can now distribute to its high-net-worth clients a full suite of deals on ADDX, including private equity, private credit, venture capital, hedge funds, real estate, fixed-income products like bonds and commercial papers, as well as structured products. Previously, CGS-CIMB was more focused on the public markets.
The partnership is part of a new service called ADDX Advantage that was rolled out earlier this year to serve wealth managers, which includes private banks, brokerages and external asset managers. By end-2023, ADDX aims to onboard as many as 10 wealth managers.
Wealth managers using the service get an instant plug-in to ADDX, which has listed more than 50 deals to date. They avoid having to originate and negotiate deals with each issuer or fund manager separately, which can be a time-consuming process.
The use of blockchain and smart contracts by ADDX enables the fractionalisation of investments down to as low as US$5,000, from the US$1 million typically required when going direct to issuers. Blockchain technology also enables secondary trading, which is not available through traditional channels. The lower barriers to entry and exit enable wealth managers to help end-clients manage risk by spreading capital across a more diverse variety of products and the added ability to rebalance portfolios regularly.
ADDX Advantage enables the performance of lifecycle management of securities on behalf of wealth managers, covering actions such as subscriptions, dividend payments, redemptions and secondary trading. As a sub-custody partner, ADDX also allows wealth managers to retain custody of their clients’ assets.
At the launch of ADDX Advantage in April 2022, CGS-CIMB was among the first to sign up for the service. Since then, the two companies have completed steps essential for the service to go live, including onboarding end-investors.
Wealth managers can choose either to enable end-investors to manage their own holdings on ADDX or to have their relationship managers create and manage sub-accounts for them. The platform is designed to adapt to wealth managers with different business models and regulatory requirements. The relationship managers will then execute trades and perform fund transfers on behalf of clients, ensuring a more seamless experience for investors.
CGS-CIMB Managing Director and Group Head, Strategic Innovation Elgin Ting stated: “As part of our mission to provide clients with an extensive suite of financial services, CGS-CIMB is always scouting for new offerings that can add value to our investors' portfolios. Through our partnership with ADDX, CGS-CIMB’s high-net-worth investors now have access to private markets and opportunities that were historically accessible only to institutional players. We are excited to see the technology and innovation ADDX is bringing to the financial markets and look forward to working with them.”
ADDX CEO Oi-Yee Choo said: “Returns from a classic 60/40 portfolio mix of public stocks and bonds are at an all-time low. Against this backdrop, we have observed growth in investor awareness and appetite for private market products over the past two years. Globally, private market assets under management are forecast to nearly double, from US$9.3 trillion in 2021 to US$18.3 trillion in 2027. Individual investor allocation to these alternative assets is likely to rise faster than allocation by institutional investors because technology is democratising access for individuals. Our solution for wealth managers provides maximum flexibility, fulfilling the different needs wealth managers have, while empowering them to help their end-clients build diversified private market portfolios. Serving wealth managers will be a key pillar of growth for us in 2023. Our priority is to optimise the user experience for wealth managers, as well as to increase the breadth and depth of offerings on ADDX.”
- 01:00 am

Financial habit-forming platform, Updraft, announces today its latest investment round, raising another £108 million in equity and debt to power its ambitious growth strategy and deliver savings to its fast-growing user base of 300k members.
The senior debt funding round of £100 million was led by NatWest, with Hampshire Trust Bank also joining to create a £160m senior debt facility for the business.
LC Nueva and Auluk Investment led equity funding of £8 million. Several other prominent investors in this round included David Callard, Majlis Investments, and Faber Capital.
Updraft combines smart algorithms, open banking and credit reference data to build a complete picture of a person’s financial profile. It then gives bespoke recommendations to establish practical and beneficial finance habits and effective routes to pay off borrowings.
This latest raise will support the business in the growth of its team and customer base, as well as investment into new features and products. With Updraft Credit lending already at £120 million, the business has just launched a phased rollout of its latest initiative to help members; Updraft Payce – a reusable limit to turn credit card purchases into cheaper, faster, flexible payoff plans.
In addition to the recently closed investment rounds, Updraft has been busy acquiring experienced talent. Recent hires include Suzanne Yeow, who joins as Chief Marketing Officer from HSBC, Cath Ready as Chief Compliance and Operational Risk Officer from New Day, and Ashish Saksena, who joins as Chief Financial Officer with previous investment banking experience at Barclays.
The fintech has already set its sights on its next funding round as it plans to open its Series B soon. With the newly available debt capital and an ambition to build a £1 billion business over the next five years, the company remains laser-focused on its mission to help more people in the UK and to expand into new markets.
Aseem Munshi, CEO and Founder of Updraft, commented: “We are thrilled to close this latest round of funding, where our debt and equity partners have demonstrated their belief in Updraft’s team and our mission, particularly in the current macroeconomic environment. It is a testament to what Updraft is trying to do; provide real solutions to customers to help them find their financial freedom. We have big ambitions planned for 2023, and this recent fundraiser puts us in a great position to help even more people.”
Rob Lamont, Director, Financial Institutions, NatWest, commented: “As a leading bank for financial capability, NatWest is pleased to be supporting a business that improves financial outcomes for consumers in the UK, and Updraft does just this. Supplementing succinct user and lending growth strategies with the use of best-in-class risk models that outperform bureau-based credit risk models, we are confident with Updraft’s growth momentum. They are, thus far, on track against all key measures where growth in new users, new lending, balance sheet, revenue, write-offs, and overall net margin are all to plan.”
Paul Maurici, Managing Director, Wholesale, HTB, commented: “Financial wellness has become more important than ever. So, we are delighted to support Updraft’s mission to help people better understand their finances and reduce their most expensive, sticky debt. HTB aims to help innovative, responsible lenders grow and serve their customer base. We are excited to work with such an experienced management team and look forward to being part of Updraft’s growth story.”
Sohil Chand, Founding Partner & CIO of LC Nueva AIF, commented: “We are excited by Updraft’s vision, energy, commitment and depth of the team, and the traction they are poised to gain in helping users manage their finances better by reducing expensive debts. LC Nueva AIF is committed to partnering with Updraft to help them achieve their vision. Our first-hand experience with Updraft and the value its market-leading financial solution to re-invent unsecured lending delivers, drove our decision to invest.”
Kieren Auluk, Executive Director, Auluk Investments, commented: “The market is large and growing with expensive balances like credit card, overdraft and BNPL now hitting above the £50B mark in the UK. There is a compelling case for a solution which helps people reduce high-interest revolving debt and sets them on a path to financial freedom. Updraft is meeting a real market need, delivered through a best-in-class platform encompassing technology, customer centricity, and data. Updraft’s explosive growth speaks for itself, and we are delighted to lead their Series A funding.”








