
Published
- 02:00 am

trueDigital Holdings, LLC, a global provider of financial infrastructure technologies and products for the digital economy, is collaborating with Kaiko and Inca Digital Securities (Inca) to expand distribution of its over-the-counter (OTC) reference rates for Bitcoin and Ether to investors worldwide.
Through the strategic partnership, Kaiko, a provider of institutional-grade cryptocurrency market data, and Inca, a digital asset analytics, consulting and technology firm, will now offer these OTC reference rates to their customers, including asset managers and institutions. Additionally, Inca will use this data to power new analytics. The aim is to provide users with institutional-grade pricing data that helps elevate the quality of trading and risk management.
trueDigital’s OTC reference rates provide a trusted source of pricing for the trading and valuation of digital assets. Rates are derived from the bid and offer prices of 12 institutional market-maker partners and are verified to ensure the executability and integrity of prices, safeguarding against market manipulation. While data from retail crypto exchanges is often inconsistent, trueDigital’s rates provides a more accurate picture of institutional pricing and liquidity as a trusted benchmark.
“These relationships are another meaningful step in the creation of an institutional-grade infrastructure for digital asset trading. trueDigital, Kaiko and Inca are all dedicated to giving institutions the data and tools to make investment decisions with the same clarity and confidence that they would with any other asset class,” said Nick Goodrich, Director of Business Development at trueDigital. “We’re excited by the potential for these and future strategic partnerships, especially those with major financial data providers, to help broaden the global reach of our reference rates.”
Kaiko and Inca join a growing list of strategic partners for trueDigital. Since its launch in July 2018, trueDigital’s OTC reference rates have generated over 17 million price points. Asset managers and other firms currently use trueDigital rates for pricing, NAV calculations and are designed to support regulated index-based products.
Ambre Soubiran, CEO of Kaiko, said “Kaiko is proud to be working with trueDigital to distribute OTC data through our market data distribution channels. Kaiko’s mission is to build the data distribution infrastructure for institutional involvement in the cryptoassets industry. Our partnership with trueDigital will further this mission while also promoting much-needed data transparency.
- 01:00 am
The Asian Banker Annual Excellence in Retail Financial Services Awards Ceremony and Dinner 2019 took place at the Conrad Dubai. Over 200 senior bankers from 40 banks across Asia Pacific, Middle East and Africa gathered to recognise institutional best practices and outstanding achievements in 2018.
Taiwan’s CTCB Bank emerged as Best Retail Bank for the Asia Pacific region, Emirates NDB was awarded Best Retail Bank in the Middle East. Other winners include Standard Chartered Bank, Greater China and North Asia, for Best Regional Retail Business in Asia Pacific and UOB was awarded Best SME Bank in Asia Pacific.
CTBC Bank’s commitment to digital transformation drove expansion of its retail franchise
CTBC Bank operates the largest private commercial franchise in Taiwan having the lead market position in credit card, mortgages, SME and wealth management. It is also actively expanding overseas and operates a comprehensive and profitable overseas network with over 260 service outlets in 14 countries and territories that include separate subsidiaries in Japan, US, Canada, Philippines and Indonesia, and posted over $1.4 billion in its global retail banking revenue in 2018.
The bank accelerated the digital transformation of its services and implemented major digital technology initiatives to bring operational processes and customer satisfaction to the next level. It is also developing innovative digital services for unique customer experiences. It strengthened its big data analytics platform and rolled out new data-driven services to better meet customer needs.
It expanded its mobile digital services through its collaboration with social platform LINE to offer social media related financial services. Leveraging advancements in financial technology, the bank launched a new suite of digital financial services ranging from investment and insurance to loans and personal financial management. For these market leading initiatives, CTBC Bank emerged as Best Retail Bank in Asia Pacific.
UOB’s strong business helps SMEs to adapt and thrive in the digital economy
Implementing a data-driven strategy to cater to the financing needs of SMEs, UOB has leveraged advanced data analytics and its strong ecosystem network to launch unsecured funding for growing businesses, and growing its footprint in Singapore and the region. This resulted in an annual revenue growth of over 80% for its SME business. The bank improved customer experience by introducing a mobile internet banking platform, which enables SMEs to manage currency volatility and track industry developments. UOB additionally allows SMEs to automate business processes, providing them with customised digital investment portfolios, and matching them with technology service providers to integrate digital solutions.
For initiatives leveraging its ecosystem network and data to meet the evolving needs of SMEs, UOB was awarded Best SME Bank in Asia Pacific at the Excellence in Retail Financial Services Awards Programme 2019.
About The Asian Banker
The Asian Banker is the region’s most authoritative provider of strategic business intelligence to the financial services community. The Singapore-based company has offices in Singapore, Malaysia, Manila, Hong Kong, Beijing, and Dubai, as well as representatives in London, New York, and San Francisco. It has a business model that revolves around three core business lines: publications, research services and forums. The company’s website is www.theasianbanker.com
About the International Excellence in Retail Financial Services Awards
The International Excellence in Retail Financial Services programme is one of the most rigorous, prestigious and transparent awards programme for consumer financial services in the world. Covering all of the Asia Pacific, the Middle East and West Africa, the programme was instituted in 2001 to recognise the pursuit of excellence amongst retail financial institutions. The programme evaluates more than 300 banks and non-bank retail financial services players in more than 42 countries, via a rigorous audit-based approach.
- 06:00 am

Finastra has launched Fusion Digital Front Office, an innovative tablet-based banking platform that enables community banks and credit unions to take services directly to the consumer, outside of the branch. The solution provides a simple gateway to manage account origination, sales and service, and transaction processing from any remote location.
“It’s no longer enough just to serve customers or members when they walk into your offices,” said Vincent Pugliese, SVP and General Manager, US Retail & Lending, Finastra. “Community banks and credit unions need to be able to serve them where they are. Imagine being able to take business with you to a home, business, or even a baseball game. Fusion Digital Front Office untethers financial institutions’ ability to service accountholders, open new accounts, and provide personal, relationship-building opportunities.”
Taking business to the accountholder is a new and modern way of banking. Fusion Digital Front Office enables business development employees to go mobile and service accountholders where they are, at any time of the day. It is highly configurable, easy to use and intuitive, so employees require minimal training. It also offers a single, digital platform to drive a consistent user experience across channels for both employees and accountholders, resulting in more personalized and robust opportunities for revenue generation.
Partners 1st Federal Credit Union and Vons Federal Credit Union are the first clients to pilot Fusion Digital Front Office ahead of general availability.
“While mobile banking capabilities are a must-have for modern financial institutions, our members continue to expect a highly personal level of service,” said Carla Bienz, President and Chief Executive Officer, Partners 1st Federal Credit Union. “With Finastra’s Digital Front Office, we are able to offer an additional way to interact with our members that combines mobility with a face-to-face interaction with our staff. The user interface allows us to quickly and efficiently provide the products and services that a member needs, without requiring lengthy workflows.”
“Vons Federal Credit Union is committed to serving our customers on their terms and on their turf,” said Jay Lassiter, Vice President, Payments Service Marketing, Vons Federal Credit Union. “Fusion Digital Front Office will allow us to bring the branch to our members, wherever they may be.”
“Bringing the bank to the customer using a single digital platform is a natural and necessary evolution of customer engagement given customers’ rapidly changing expectations,” said Bob Meara, Senior Analyst, Celent. “The future of banking is digital. Technology is enabling financial institutions to optimize the customer experience, whether self-service or in-person, improving engagement and strengthening relationships.”
Fusion Digital Front Office, deployed in the cloud on Microsoft Azure, is device-agnostic, scalable, responsive, and built on a modern platform. It also integrates with other third-party solutions and Finastra solutions (Fusion Analytics, Fusion Mortgagebot, Fusion DecisionPro, Fusion uOpen, and more). The ability to integrate easily with other solutions ensures that data flows smoothly in and out of the application. Users gain real-time transaction productivity via a single-sign on.
- 05:00 am

Surecomp®, the leading global provider of trade finance solutions for banks and corporates, announced today the successful upgrade of allNETT®, a SWIFT compliant web based front-end trade finance system for The Bank of Ayudhya Public Company Limited (Krungsri Group). The bank will now be running allNETT 6.3 alongside Surecomp’s back-office trade finance solution; together they will provide Krungsri a seamless, end-to-end processing of their trade finance operations.
Established in 1945 and headquartered in Bangkok, Krungsri ranks among the top five banks in Thailand in terms of assets, loans, and deposits. “Today’s news is another milestone in our longstanding relationship with Surecomp”, said K.Yingluk Kongkasai, Executive Vice President Head of Transaction Banking Group at Krungsri. “Following a smooth and timely implementation, we are proud that allNETT is up and running.It is crossover to a user-friendly interface that is faster, simpler and more efficient. We strongly believe that it will enable our clients to receive reminders, alerts, generate full reporting and give them access to an improved transactions screen with more relevant features to facilitate their trades”
The successful implementation of allNETT has provided Krungsri with a next generation front-end – integrating with their existing Surecomp back-end trade finance solution. With modernized dashboards and processing features, allNETT and Surecomp’s back-office solution have developed reputations as the industry standards for their respective fields. Their platforms were designed to deliver increased efficiency for users through automation which saves time and eradicates human error. allNETT offers a vehicle for hassle-free, paperless and immediate correspondence between banks; together with Sureocomp back-office solutions, they provide a fully integrated end-to-end trade services solution with outstanding processing capabilities.
“We commend Krungsrifor their decision to boost their trade finance operations with the most cutting-edge technology on the market”, said Yaron Hupert, Surecomp’s Senior Vice President of Global Account Management. “We are confident that through the allNETT/back-office combo, Krungsristrengthens its position as a powerhouse bank with an utmost efficient operation.” Hupert continued to say that the Krungsri project serves as a model for mutual success and that Surecomp is excited to continue working closely with them on future projects for years to come.
- 09:00 am
Mastercard today introduced a vision for digital identity in today’s increasingly connected world. A new paper, Restoring Trust in a Digital World, presents a detailed framework of how digital identity will work, starting with the individual sitting at the heart of every digital interaction.
Guiding this model are Mastercard’s Principles of Digital Identity that will underpin the system. These principles focus on data rights and ownership, confidentiality, consent, transparency, security and inclusion. They amount to a fundamental individual right: “I own my identity and I control my identity data.”
“The big question for digital interactions in a hyper-connected age is: how do you trust someone you don’t know, can’t see and isn’t present in person?” said Ajay Bhalla, president of Cyber & Intelligence Solutions for Mastercard. “This is an area we’ve been exploring for some time, in discussion with a range of different groups. It’s with this insight that we imagine a world where a person’s identity and the devices operating on their behalf can be verified immediately, safely and securely, where access is gained without passwords and data is exchanged only with consent.”
Mastercard’s model embodies privacy-by-design and does not aggregate identity data. It will enable digital interactions to occur with minimal data exchanged and only when needed, and will safeguard data and the use of data effectively such that the users are in control, with a person’s identity securely bound to their smartphone.
Access to a digital identity will unlock new and enhanced experiences for people as they interact with businesses, service providers and their communities online, introducing a more efficient online shopping experience, a more seamless process for opening a bank account or filing taxes, and streamlining use of e-mail, social media and entertainment platforms. It will also reduce the risk of fraud and identity theft.
Ajay Bhalla said: “Digital identity requires a collective effort. Building on our strategic partnership with Microsoft and working with a range of industry players, we are committed to facilitating the network and helping define the rules and governance. Together, we have a real opportunity to transform digital engagement so that it is convenient and doesn’t compromise on security.”
- 07:00 am

A Credit Card Designed for iPhone


Easy-to-Understand Spending

Apple Card is designed to help customers lead a healthier financial life, which starts with a better understanding of their spending.
Receive Daily Cash
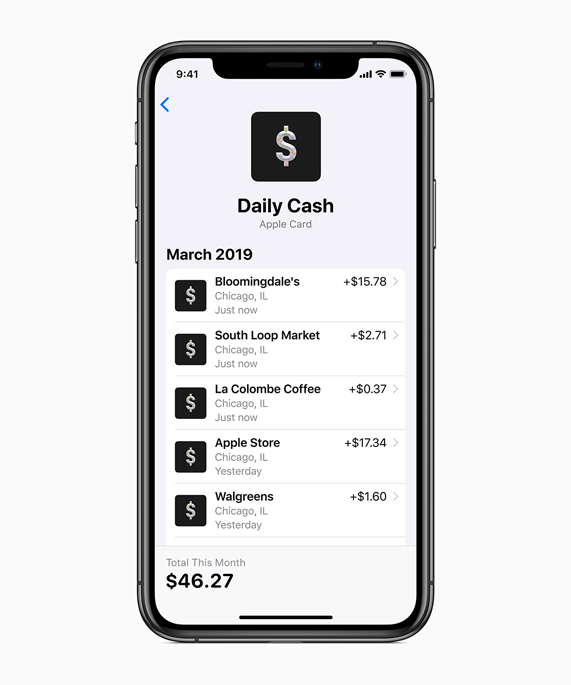
Apple Card offers a more compelling rewards program than other credit cards with Daily Cash, which gives back a percentage of every purchase as cash on customers’ Apple Cash card each day.
No Fees and Lower Interest
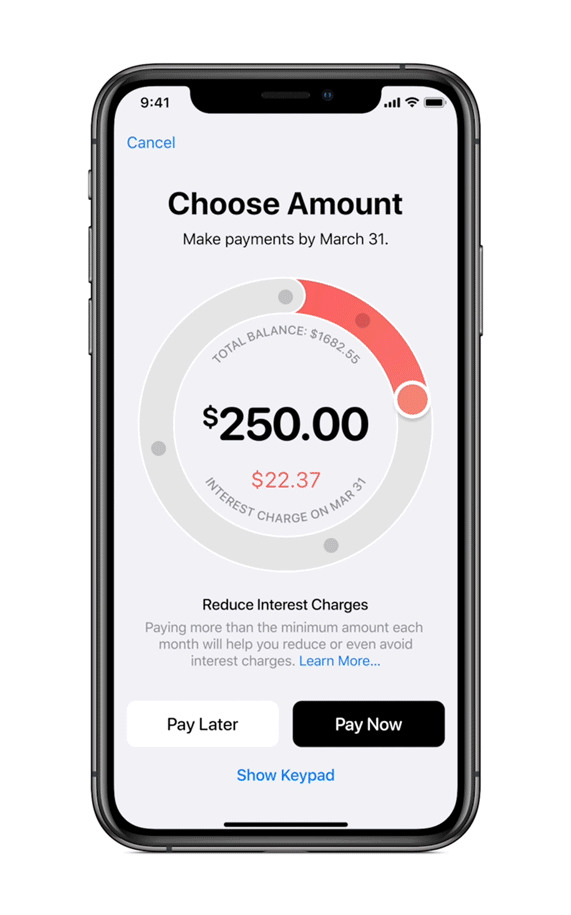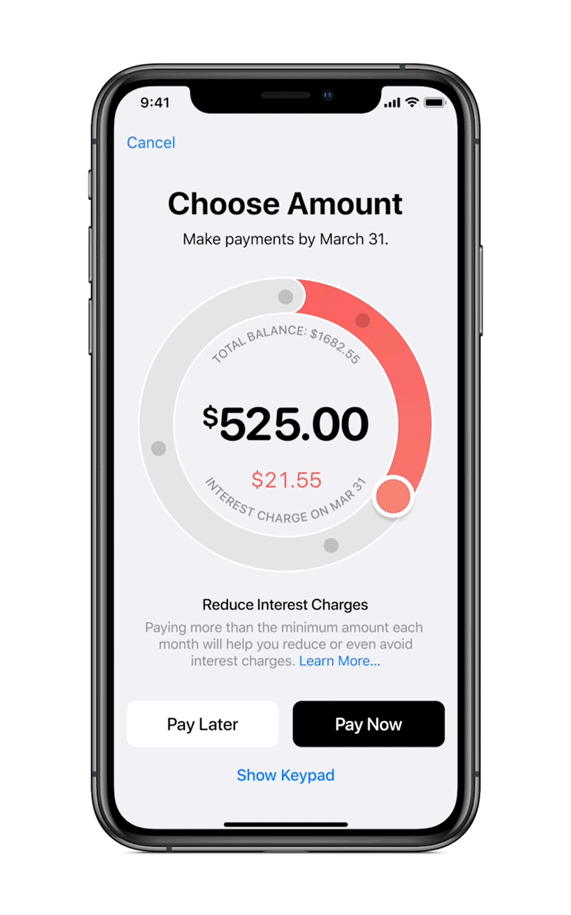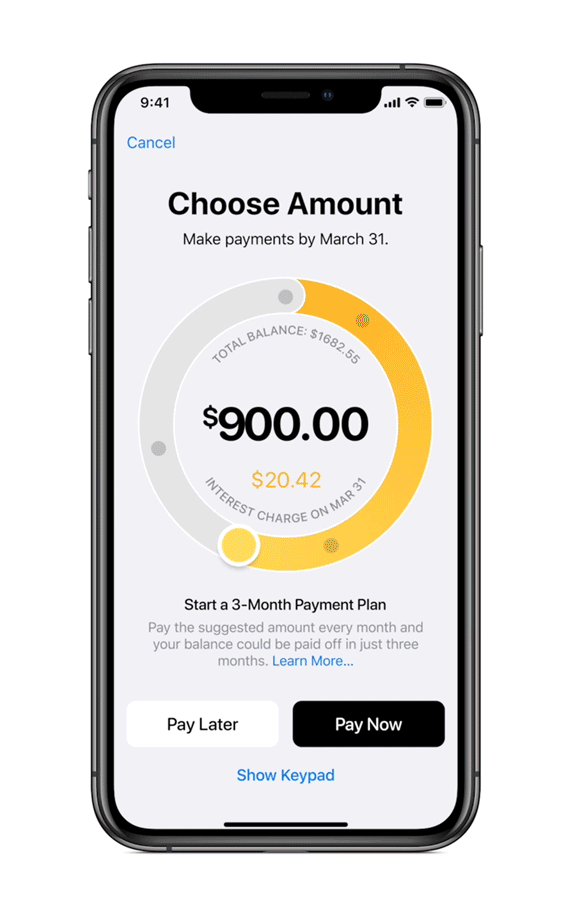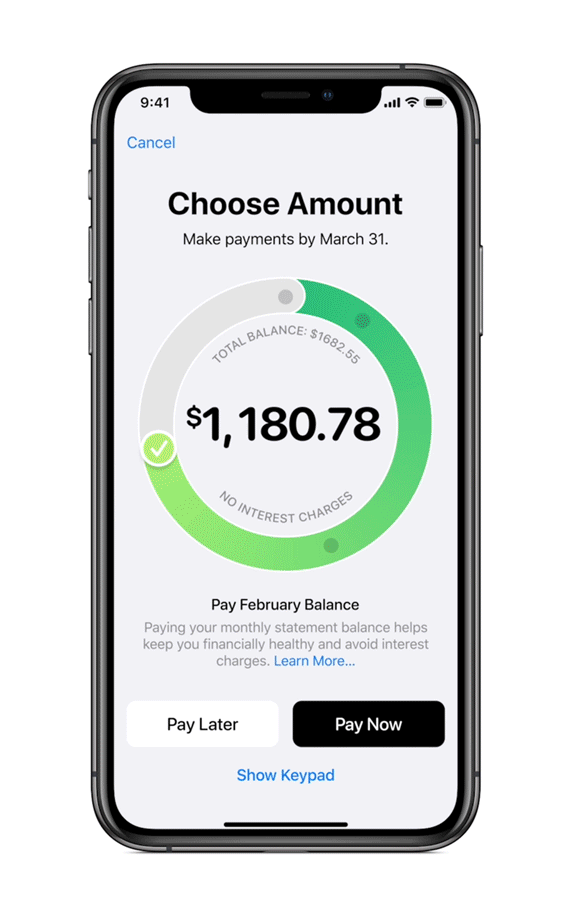
Apple Card is the first credit card to encourage customers to pay less interest and offers transparency to help them understand how much it will cost if they want to pay over time.
A New Level of Privacy and Security
Goldman Sachs and Mastercard
A Beautiful Titanium Card
- 08:00 am
The international payments startup has raised a new round of $100m USD investment led by DST Global, becoming a fintech unicorn
Airwallex, an international payments fintech that specialises in low-cost, seamless cross-border payments, has today confirmed its unicorn status following successful series C funding of $100m USD, leading to a valuation at more than $1bn USD.
- Series C is led by DST Global, a leading investment firm, which has backed internet giants Facebook, Airbnb and Spotify and fintech leaders Nubank and Robinhood
- The new capital will be used to expand Airwallex’s suite of international collection and payment products and to support global expansion into the US, UK / Europe and Southeast Asia.
- Airwallex is committed to empower not only marketplaces and merchants, but also small & medium enterprises (SMEs) to grow their businesses
Top-tier investor DST Global led the Series C fundraising round, which closed at $100m USD. Alongside new investor DST Global, existing participants from Airwallex’s previous rounds returned for the Series C fundraising, including Sequoia Capital China, Tencent, Hillhouse Capital, Gobi Partners, Horizons Ventures and Square Peg Capital. The new funding round brings the total amount of external funds raised to over $200m USD. Just three years after it was founded, Airwallex is now valued at over $1bn USD, confirming its position as a newly minted fintech unicorn.
The investment will support Airwallex’s plans to accelerate product development and grow its business operations internationally, as well as fuel its aggressive customer acquisition strategy in Australia, the UK and the US, with new offices opened in Europe and North America.
Airwallex has picked London as the location of its European headquarters, and will kickstart its UK operations immediately. Led by James Butland, VP - European Growth at Airwallex, the fintech has built a local team across Sales, Compliance, Marketing and Partnerships to build the European client base.
Founded in Melbourne (Australia) in 2015, Airwallex has grown from an emerging start-up to a global challenger in the cross-border payment space. Airwallex offers an end-to-end solution for businesses to make payments and move money programmatically on a global scale, supporting a client base of internet titans including JD.com, Tencent and Ctrip, and large financial service companies including MasterCard.
In the UK, after being granted an EMI license by the FCA in November 2018, Airwallex will target SMEs and online marketplaces that are looking towards international expansion.
The latest government figures reveal that in 2017, 232,000 UK businesses, representing nearly one-in-ten UK SMEs (9.8%), were exporting overseas. Airwallex will aim to support these SMEs and their payment needs by allowing them to instantly create Global Accounts with local bank details, access interbank exchange rates and send money through local and international clearing networks to more than 130 countries.
Commenting on the latest series funding, James Butland said: “The quality of investors in Airwallex is testament to the solutions we have developed; the likes of DST Global have invested in tech success stories such as Facebook, Alibaba and Twitter, and it matches our ambition. We want to enable businesses in every market we operate in to scale globally, and participate more easily in global markets, by providing a platform that delivers efficient payment processing through some of the world’s busiest trading corridors.
“Our platforms, which have experienced huge growth in Australia and Asia, will help free businesses from many of the traditional barriers that have made international transactions and growth so difficult. Our journey has only just begun in the UK and London; but we know the market is strong - we can already see huge potential for our services.”
Tom Stafford, Managing Partner of DST Global comments: “Cross-border ecommerce continues to grow strongly, driven both by consumer purchasing as well as business-to-business transactions. This growing industry needs a technology-focused payments network that is reliable, cost-effective and provides data transparency. Airwallex has built such a network and we are excited to partner with Jack and the team as they continue to grow their business”.
- 01:00 am
Guardicore, a leader in internal data centre and cloud security, today announced the launch of its Guardicore Threat Intelligence community resource. Developed by the Guardicore Labs research team, Guardicore Threat Intelligence is a freely available public resource for identifying and investigating malicious IP addresses and domains. With an easy to understand dashboard, Guardicore Threat Intelligence rates top attackers, top attacked ports and top malicious domains, giving security teams the insight they need to research and understand attacks and mitigate risks.
“Based on our deployment and technology Guardicore has a unique view of the most recent threats that are targeting servers in the cloud and in data centres. As a company we believe in giving back to the community and contributing where we can to the benefit of all. Thus, the Guardicore Labs research team has made its data and research available for the public,” said Pavel Gurvich, Co-founder and CEO, Guardicore. “With the launch of Guardicore Threat Intelligence, the cyber security community now has the opportunity to benefit from the same insights leveraged by Guardicore to protect its customers. Busy security teams can now benefit from a trusted, freely available resource that allows them to keep track of potential threats and enjoy unique analysis specific to data centre attacks.”
Guardicore Threat Intelligence Features
Guardicore Threat Intelligence is currently the only publicly available community resource to focus exclusively on data centre attacks. Specifically, it includes data not available in other public feeds, including the role of IP addresses in specific attacks and detailed attack flow, providing context for attacks on Internet-facing servers with a single aggregated view. Security analysts, threat hunters, and incident response or forensics teams can leverage Guardicore Threat Intelligence as an aggregated source to verify threats, understand attack patterns, and update IoCs quickly, eliminating the need to check multiple feeds and accelerating the time to response. Ultimately, Guardicore Threat Intelligence can help defenders anticipate future attacks and mitigate risks. Guardicore sources data from its Guardicore Global Sensors Network (GGSN), which streams early threat information to Guardicore Labs’ team for new attack identification and analysis.
Availability & Contributions
Guardicore Threat Intelligence is freely available now at https://threatintelligence.guardicore.com. Contributions are welcome. Guardicore Labs invites the cybersecurity community to contribute to its Threat Intelligence knowledge base by submitting data, asking questions and collaborating with Guardicore researchers on additional findings.
Guardicore Labs
Guardicore Labs is a global research team, consisting of hackers, cybersecurity researchers and industry experts. Its mission is to deliver cutting-edge cyber security research, lead and participate in academic research and provide analysis, insights and response methodologies to the latest cyber threats. Guardicore Labs helps Guardicore customers and the security community to continually enhance their security posture and protect critical business applications and infrastructure.
Creators of Infection Monkey, a popular open-source network resiliency test tool, Guardicore Labs’ high-profile threat discoveries include the Hexmen multiple attack campaigns targeting database services, the Bondnet botnet used to mine different cryptocurrencies, Operation Prowli, a traffic manipulation and cryptocurrency mining campaign, and Butter, a brute force SSH attack on Linux machines that leaves a backdoor to deliver a Samba payload. To learn more visit Guardicore Labs.
- 03:00 am
The deployment of Consumer Device Cardholder Verification Method (CDCVM) solutions across the payments ecosystem is increasing. EMVCo is therefore working to promote confidence and consistency by identifying and addressing specific security, functional and performance needs for CDCVM.
With traditional Cardholder Verification Methods (CVM), consumer authentication is performed on the merchant system (a PIN entered into a merchant device, for example). The growing use of mobile devices for payment transactions has enabled consumer authentication to be performed specifically on the consumer’s own device, via passcodes, passwords and patterns, as well as through biometrics such as fingerprint, iris, voice and facial recognition. This type of authentication on a consumer device is known as CDCVM. Additionally, when multiple payment applications on the device share the same CDCVM and the associated result, it is referred to as Shared CDCVM.
As CDCVM is very different to traditional CVM, EMVCo has developed a dedicated process to evaluate the security of CDCVM solutions and has defined industry best-practices to address functional and performance considerations:
· EMV® CDCVM Security Requirements and Security Evaluation Process – to help promote protection from fraud across the consumer and wider payments ecosystem, it is imperative that solution assets (such as a user’s biometric or password) be adequately secured. Also, the delivery of results must not be manipulated, falsified or exploited, and the solution must not be maliciously abused, disabled or bypassed. To support these objectives, EMVCo has published CDCVM Security Requirements and has established a Security Evaluation Process to help ensure CDCVM solutions maintain certain minimum levels of security, including mechanisms and protections designed to withstand known attacks.
· EMV CDCVM Best Practices – EMVCo has defined guidelines for functional and performance behaviours to promote a consistent user experience and global interoperability.
In particular, EMVCo has been collaborating with the FIDO Alliance since 2016. As part of this collaboration, EMVCo shared a number of CDCVM use-cases for payment which the FIDO Alliance took into account when incorporating User Verification Caching into the FIDO specification. EMVCo continues to liaise with the FIDO Alliance to ensure that the FIDO Alliance Biometric Certification programme covers the EMVCo high-level performance objectives. CDCVM solution providers are encouraged to evaluate the performance of their solutions using the FIDO Alliance Biometric Certification programme.
To stay informed of the latest EMVCo developments and receive advanced access to EMV Specifications and related documents, join the EMVCo Associates Programme or become a Subscriber.
To learn more about CDCVM, please read the Q&A that is available for download from the EMVCo website.
- 04:00 am
Simplicity, security and ubiquity sit at the very core of some of the most progressive innovations of our generation. These innovations have challenged the notion of, “that’s how it was always done” to lead to transformational “can’t live without” products and services that have made our day to day experiences better, faster and more convenient. Just 10 years ago, you couldn’t have imagined a world where your car ride or your morning coffee could be customized and delivered to you with the tap of your finger. At Mastercard, we’ve worked with a number of payment and technology partners and have been behind a number of these types of innovations such as: development of token services; immersive shopping; Mastercard Track – a global trade platform and financial tool for gig workers.
We believe consumers want more of this type of thinking – intuitive, thoughtful and creative solutions to enhance their transactions. People are looking to newer technologies to have an impact on their lives. In the past year alone, new-technology mentions on social media increased 30 percent.
And today, we’re proud to introduce yet another first. Together with Apple, one of the great consumer brands in the world and Goldman Sachs, a prestigious institution in the financial services industry, we’re launching the first ever Mastercard Digital-First card. The technology behind it and the product itself is the first of its kind. Unlike the way in which cards have been traditionally issued, this Digital-First card will literally arrive in your digital wallet first before it arrives in your mailbox (optional). Using revolutionary security features like TouchID or FaceID, it takes seconds to authenticate and is ready for the cardholder to tap, swipe and check out – instantly. According to a recent study, 68 percent of those who have loaded a debit or credit card to a mobile wallet indicated they expect to make 50 percent or more of their in-store purchases using a digital wallet within two years.
A card like this is not only convenient but it’s also the pathway to opening up new ways to pay for things that you didn’t think possible. Imagine tapping your way through a toll booth or a take-out window or imagine tapping your way onto the metro instead of using proprietary cards or tickets. In fact, we’re already integrating this technology to a number of transit systems around the country including Los Angeles, Boston, and Denver. And new transit solutions are expected to be live in more than 20 markets in the United States including New York City within the next few years.
At the core of both these announcements is our token services and M Chip technologies that help store the card on a digital device without exposing important details and also enable fast contactless payments – making the commuter experiences fast, simple and secure. Mastercard brought token services to Apple Pay in 2014 and late last year announced its strategy to enable token services on all cards by 2020.
These are just a few of the examples of how we’re connecting the dots, thinking creatively, enhancing transactions and creating frictionless user experiences that never compromise on security, simplicity and ubiquity.








