
Published
- 07:00 am
NICE Actimize, a NICE (Nasdaq: NICE) business and the leader in Autonomous Financial Crime Management, has been chosen by Rakuten Securities Inc., a major online brokerage operating throughout Japan and across Asia, to implement an innovative anti-money laundering compliance platform to protect and support its investor clients and meet regulatory requirements. Rakuten Securities will utilize industry-leading solutions from NICE Actimize’s Autonomous Anti-Money Laundering portfolio, initially rolling out the CDD-X Customer Due Diligence platform. This will be followed by Suspicious Activity Monitoring and Watch List Filtering solutions at a later date to help improve operational efficiencies and reduce costs.
An integral part of its Autonomous Anti-Money Laundering suite, NICE Actimize’s CDD-X Customer Due Diligence platform modernizes KYC/CDD programs with advanced analytics. Providing more accurate detection and customer risk scoring to reduce compliance risk, NICE Actimize’s CDD-X provides significant reductions in operational costs and offers key features beneficial for an online brokerage operation.
NICE Actimize’s CDD-X Customer Due Diligence solution also offers embedded automation capabilities that streamline tasks related to ultimate beneficial ownership (UBO), adverse media, data flow with customer relationship management (CRM) systems, and more. By enabling a curated set of pre-built connectors, CDD-X also leverages third party risk factors to increase the accuracy of customer risk ratings during onboarding and ongoing monitoring to provide more intelligence to analysts. Additionally, pre-built connectors make integration simple where data acquisition and aggregation has traditionally been difficult.
“As many financial institutions worldwide pursue a more data-driven, advanced approach towards anti-money laundering initiatives, we are confident that the capabilities of these new solutions will bring great value to both our operations and the customers we serve,” said Keisuke Ichihara, Director and Executive Officer, Rakuten Securities Inc. “NICE Actimize’s deep experience, accumulated through strong relationships with financial institutions, will help us achieve our objectives as part of our renewed anti-money laundering strategy.”
“NICE Actimize is excited to provide our advanced anti-money laundering solutions to Rakuten Securities,
the online brokerage market leader in Japan and the greater Asia-Pacific,” said Craig Costigan, CEO, NICE Actimize. “As the AML regulatory landscape evolves and the criminals become more sophisticated, compliance teams need a solid AML program that meets these changing requirements, while reducing costs and improving operational efficiency. We look forward to providing Rakuten robust solutions that will help them address these challenges while staying ahead of market and regulatory changes.”
In addition, NICE Actimize’s Suspicious Activity Monitoring solution combines cutting-edge technology with human-expertise to ensure accurate alert detection, increased team productivity and lowered compliance program costs. Lastly, NICE Actimize’s Watch List Filtering capability, with its consistent, global sanctions screening and high-quality alerts, increases operational efficiency, reduces compliance costs, and assists in meeting regulatory requirements.
For additional information on NICE Actimize’s Autonomous anti-money laundering solutions, including CDD-X please click here.
- 08:00 am
UK-based FinTech firm Paysend has called for an industry-wide acceleration of innovation across FinTech and payments in response to the global coronavirus situation. Sweeping disruption to the daily financial habits of consumers has created a number of problems that Paysend sees as necessary to be solved by emerging FinTech innovators with the provision of simple, accessible and low-cost solutions.
“Given the huge changes in consumer behavior and consumption patterns, and lockdown measures changing -potentially permanently - the way that people interact with their finances needs to change fast,” Alberto Macciani, CMO of Paysend said. “It’s no surprise that there will never be a return to the previous way of living given the monumental events that have shaken the world in the past six months. For example, many surveys conducted recently show a clear preference for employees not to go back to full-time office work, but rather to mixed models which give the best of both - flexibility and engagement. This is the mantra that FinTech needs moving forward.”
Paysend’s business is centered on the seamless movement of money around the world, and the firm has highlighted 3 major phenomena sparked by the coronavirus crisis: the growth of digital payments and transfers driven by lockdown restrictions; a drop in cash usage because of issues around the safety of cash; the increasing integration of payment platforms, where distinctions are being removed to focus on single supports such as smartphones or smart cards.
“At Paysend we have identified the key trends that will shape the world after the pandemic has settled down through a combination of social listening and customer analytics, and we’re exploring them through our new innovation process,” Mr Macciani added. “We have developed an approach which we identify as ‘customer centric’, for which we ignite 3 factors: technology, trends and customer feedback. The result is featured in our product innovation funnel which represents the roadmap for future products.”
Paysend has experienced record growth of its Global Transfer platform in recent months, reaching over 1.8 million customers joining to date, as well as the successful launch of new international money account Paysend Global Account, which demonstrates the potential of the integrated portfolio of Paysend.
“Innovation in times like these is a great opportunity as the world is being reshaped and it gives us the opportunity to tap into trends and create new products that are really in-tune with customer insights and needs, and not simply existing ones,” Mr Macciani said. “In that sense we aim to become a lifestyle brand that supports customers getting the most from their lives, rather than simply a service provider.
- 06:00 am
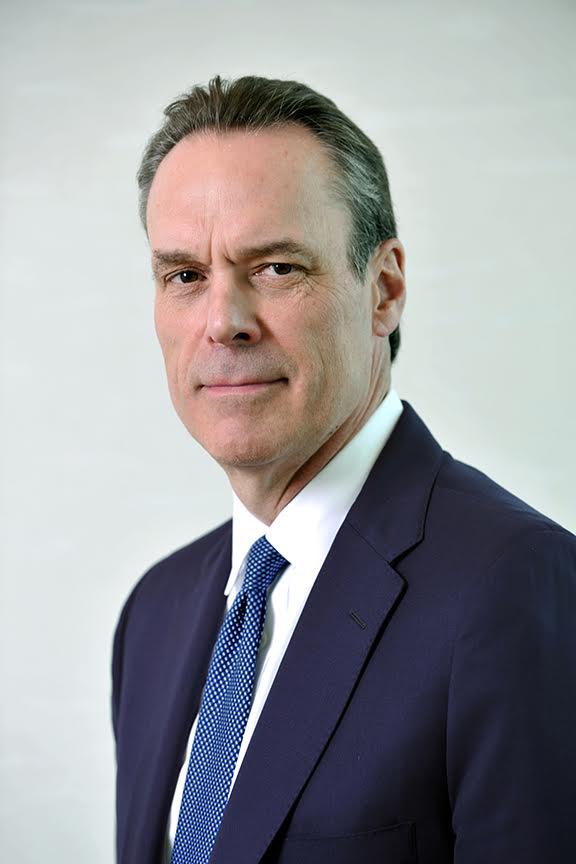
RTGS.global, the world’s cross-border liquidity network, has announced its appointment of Jim Cowles as an Executive Director of the Board. Jim will work closely with RTGS.global’s leadership team, including its founder, fintech entrepreneur Nick Ogden, who previously founded WorldPay and ClearBank.
Jim was CEO of Europe, Middle East and Africa at Citi for more than six years, leading a team of c. 23,000 employees located in 55 countries. He was previously EMEA Chief Operating Officer, and before that was head of markets in the region for the bank.
Alongside his appointment at RTGS.global, Jim is a non-executive director of Shieldpay and has strong experience in growing startups. Most recently, he founded media company The Venn, a nonpartisan platform focused on delivering an effective and efficient way of learning about political issues.
Jim’s appointment comes as RTGS.global gears up to launch the first stage of its go-live in conjunction with a number of commercial banks. As Executive Director, Jim will sit on RTGS.global’s board, playing a crucial role in advising the leadership team as the company commences its global rollout in late June.
On his appointment, Jim Cowles commented: “Having worked in financial services and banking for 39 years, I have experienced the challenges present in the current international interbank infrastructure. Simply put, this has to change to utilise technological advances to meet the needs and demands of clients, regulators, and the banks themselves. I am excited to be joining RTGS.global at such a pivotal time. With strong support from regulators, our investors, and technology partners, we’re in a unique position to launch the network and remake the cross-border transfer business.”
Nick Ogden, Founder and CEO of RTGS.global commented: “We are excited to have Jim join RTGS.global. He is a real heavyweight in the world of finance and banking, and with decades of experience, his insight and support will be truly invaluable. Jim’s appointment comes at an opportune time - we have a lot planned over the next few months, as we strive to our target of being the first company in the world to test and demonstrate global atomic settlement within our network of banks.”
- 03:00 am

Financial technology leader FIS™ (NYSE: FIS) today announced Enterprise Productivity, Intelligence & Compliance (EPIC™), a modular, desktop-based solution that helps financial institutions and businesses enhance the efficiency of their global operations while managing an increasingly remote workforce.
The COVID-19 crisis has created a host of operational challenges for organizations, requiring them to modify their business plans and invest in technologies that support and enable a remote workforce.1 With work-from-home arrangements on the rise, the FIS EPIC solution provides organizations with an integrated, dashboard view of their business processes, and digital and physical assets on a single platform.
EPIC leverages advanced data analytics technology to enable operations personnel to monitor enterprise-wide operations from their desktops. With the aid of the EPIC solution’s powerful automation tools, organizations can allocate virtual and physical resources in real-time to handle spikes in business activity.
“The pandemic has fundamentally changed the way businesses operate, manage their teams and interact with customers,” said Rob Lee, head of Digital and Banking at FIS. “Our new EPIC solution helps financial institutions and businesses understand and optimize the efficiency of employees working from home, providing greater control over their extended enterprise.”
The FIS EPIC solution includes six modules:
- Automation Module – Leverages robotics process automation and remote desktop agents to dynamically allocate workloads via a unified console
- Intelligence Module – Provides a set of powerful AI-enabled business intelligence tools that helps businesses manage workforce processes and performance.
- Compliance Module– Monitors workforce compliance with enterprise policies, regulatory requirements and fraud management.
- EPIC Core – Handles core tasks including analytics, data and process mining, event processing and reporting.
- Efficiency Module– Captures key operational data on workforce, asset productivity and workload management to help prevent bottlenecks.
- Knowledge and Experience Module – Synchronizes learning programs and distributes new policies and procedures to employees across the enterprise.
The FIS EPIC solution recently won four awards at the Asia Outsourcing Leadership Awards.
Learn more about EPIC in this video.
- 01:00 am

SunTec, a leading provider of revenue and billing management solutions, announced today that it is working with Amazon Web Services (AWS) to offer Xelerate platform and products on AWS Cloud. The Xelerate platform and products have been optimized to leverage the cloud capabilities of AWS.
Organizations across industries will now be able to leverage Xelerate products on AWS cloud and take advantage of the cost, resilience, high-performance, advanced security, scalability, and agility even while handling large volumes of customer and transaction data. SunTec is a Select Technology Partner in the AWS Partner Network (APN).
One of the world’s largest investment banking enterprises based in the US is currently implementing Xelerate on AWS Cloud. More than 125 customers across industries and geographies leverage the micro-services and API based, award-winning Xelerate platform and products for their digital transformation projects across pricing, billing, product, loyalty, deal, offer, partner monetization, and tax management processes.
Xelerate platform and products enable organizations to create and bundle products, services and offers for any customer segment, adopt relationship-based pricing strategies, and optimize billing processes. It also allows organizations to offer customized products, create and configure specific deals, offer partner products, and track the revenue and profitability of all products.
Amit Dua, President - Client Facing Groups, SunTec commented, “Current times will expose and segregate the ‘truly-digital’ organizations from ‘pseudo-digital’ ones. We are excited to work with AWS to help accelerate the digital transformation projects of our customers across the world and will enable organizations to become more customer-centric, reduce time to market, and create new revenue streams.”
Through this collaboration, SunTec will continue to accelerate the digital transformation journey of its clients via cloud-native and cloud-agnostic products. This will further allow SunTec’s clients to innovate faster and at lower costs, thereby enhancing the customer experience – ultimately transitioning to an agile, customer-first organization that can respond to the current challenging market environment.
- 07:00 am
Europe-wide research commissioned by innovative financial infrastructure provider Banking Circle has found that nearly two thirds (64.6%) of online merchants have needed extra finance in the past two years (excluding borrowing due to the current COVID-19 crisis). Nearly a quarter (23%) needed the additional funding to cover payroll, and a further 26.5% to cover regular business costs.Whilst needing to access extra funds is a fact of life for many businesses, the Banking Circle research highlights the serious gap in how easily and quickly funding can be accessed – which will be all the more crucial in the current climate.
Just under a quarter of respondents had to wait between three and four weeks to receive the cash they needed to cover essential costs, yet 26.4% felt that without access to new cash they would be forced to let employees go. And almost a quarter (24.4%) believe their business would ultimately fail if they were unable to access new finance.
With a whole new set of pressures on businesses of all sizes, but small businesses in particular, Banking Circle’s latest white paper, ‘Mind the Gap: How payments providers can fill a banking gap for online merchants’ highlights the continued issue of financial exclusion for SMEs – and the opportunities for payments providers. These organisations are already connected to online merchants – and can play a crucial role in providing wider banking services, as well as access to funding.
Key findings:
Cross border banking is a challenge
- Across EMEA an average of 19.2% of online merchants have separate banking relationships in every country in which they operate – adding to their costs and resources to manage
- 17.2% of UK merchants have separate banking relationships in every country in which their business trades
- 44% of UK merchants work with just one bank for all the countries in which the business trades
- 26.2% of businesses in the Nordics are the most likely to work with separate banks in each jurisdiction
- 13.9% of French merchants work with multiple banks
- 20.3% of Netherlands firms work with multiple banks
Banking services used by online merchants
- Around half of online merchants surveyed said they use short-term loans (47.8%), overdrafts (49.1%), and finance agreements for specific purposes (48.8%)
- 43.2% access settlement accounts for cross border payments (43.2%) from their main bank
- 35% use their bank for foreign exchange (FX) services (35%)
- German merchants are least likely to access solutions to help with cross border trade, with the lowest
proportion of all respondents accessing settlement accounts (38.8%) and FX (16.8%)
Accessing finance – how long does it take?
- Online merchants reported that accessing business finance had taken them as much as 6 months:
- 18.8% said it took 1-2 weeks
- 24.6% - 3-4 weeks
- 21.7% - 1-2 months
- 16% - 3-4 months
- 6% - 5-6 months
The Opportunities for FinTechs and Payments businesses
- 87.3% feel their business is well served by their current banking partners; German merchants are the least satisfied at 82.9%
- 42.6% of the dissatisfied businesses felt their business is not a priority for their bank, and 41.5% gave high fees as a reason
- Approximately one in fourrespondents dissatisfied with their bank gave each of thefollowing reasons for theirdissatisfaction:
- poor quality and inconsistentservice (28.7%)
- slow response times (28.7%)
- poor FX rates (24.5%)
Commenting on the findings of the study, Anders la Cour, Co-founder and Chief Executive Officer of Banking Circle said: “The world of digital commerce is a rapidly growing sector; but it is also a sectorwhere entrants face multiple barriers to operate because established financial institutions have a fear of the unknown.
“Opening a bank account – fundamental for most enterprises – can feel like taking an exam. And access to short-term funding, whether to fill a cashflow gap or to underpin growth plans, can involve multiple hurdles often just too steep to get over. However, payments providers already supporting the online merchant space can deliver a genuine added value by providing their merchant customers with banking services including access to funding. And in the current climate that support is going to be more valued than ever – indeed, for payments providers that demonstrate a real understanding of SME needs there could be a significant long-term gain.”
Anders continued: “Banking Circle has always been committed to improving financial inclusion for smaller businesses, and this study helps us and the wider industry to identify – and therefore help to fill –gaps in the current offering.”
The full white paper,‘Mind the Gap: How payments providers can fill a banking gap for online merchants’, is available to download for free at https://www.bankingcircle.com/whitepapers/how-payments-providers-fill-finance-gap-online-merchants.
The research was conducted by Censuswide between 30th March 2020 and 7th April 2020, amongst 1,514 respondents from merchants that trade online and respondents who work in the finance department in companies that sell digitally. The SME merchants surveyed were based in the UK, Germany, France, the Netherlands and the Nordics.
- 06:00 am
Koine, the provider of segregated, institutional custody and settlement services for digital assets and fiat money, has integrated with digital broker GC Exchange Limited (GCEX); two firms regulated by the UK’s Financial Conduct Authority (FCA).
GCEX, founded in 2018, will use Koine’s custody and settlement services, enabling GCEX’s client base to benefit from Koine’s cutting-edge platform for both fiat and digital currencies. Koine’s proprietary technology will support GCEX, which allows for the deposit and extraction of value (on and off ramps) in a large number of digital assets and FX pairs, from majors to exotics.
GCEX will also use Koine’s paying agency service, designed to reduce costs and dramatically improve security. This service allows clients to send digital assets directly to the GCEX-labelled hub on the Koine platform. In this way, the use of hot and cold wallets is minimised, reducing the number of transactions between the two platforms and making the movement of assets ultra-secure.
Koine customers gain access to a post-trade solution from a business licensed by the UK’s Financial Conduct Authority, a service specifically designed for institutional investors to mitigate counterparty, insolvency and credit risks of trading on exchanges. The automated service obviates the need for humans in post-trade processes, delivering massive operational scalability with near real-time egress of digital assets from custody where required.
Koine’s unique security model, using Digital Airlocks™, replaces the cold store and hot wallet model which exposes private keys to humans and results in poor operational scalability. By combining this new digital asset security model with fiat custody and DvP settlement, Koine provides a post-trade solution that is suitable for traditional capital markets.
Based in London, GCEX is designed to meet the demand for regulated and compliant exposure to the digital assets space. Authorised and Regulated by the Financial Conduct Authority (FCA), GCEX provides funds, brokers, asset managers, professional traders, and banks with a suite of cutting-edge products, including AI systems. This allows its clients to automate on-boarding, offer and trade digital assets and currencies with liquidity from Tier 1 banks.
Hugh Hughes, Chairman and CEO at Koine, said: “We’re thrilled to enter into this partnership with GCEX. We have already seen a positive industry response to Koine’s ultra-secure scalable institutional-grade solution for custody and settlement, and this deal highlights a further consolidation of our reputation as the institutional platform of choice.
“By working with fellow industry innovators, we know that, together, we will deliver the infrastructure and service our clients need to protect and fully leverage the potential of their digital assets. GCEX’s proven experience and valuable insight into the digital asset exchange market, as well as their global appeal thanks to the wide range of currency off-ramps they offer, will be tremendously beneficial to Koine’s development as we continue to go from strength to strength in 2020.”
Lars Holst, CEO at GCEX, said: “It is exciting to be entering into a partnership with Koine at such a pivotal time in the digital assets space. In choosing Koine as the custody and settlement provider for our clients, we will be able to extend our reach into institutional capital, and further capitalize on our advantage of offering a range of currency off-ramps, further reinforcing our position in the global exchange ecosystem.”
- 09:00 am
Today the British Business Bank has announced that it has approved four new lenders for accreditation under the Coronavirus Business Interruption Loan Scheme (CBILS).
New lenders The FSE Group, FW Capital, Mercia Asset Management and Whiterock Finance will be able to provide financial support to smaller businesses in the Northern Powerhouse and Midlands Engine regions, as well as Northern Ireland, that are losing revenue and seeing their cashflow disrupted, as a result of the Covid-19 outbreak.
Accreditation will now allow appointed regional fund managers to issue CBILS backed loans from the following regional funds – the Northern Powerhouse Investment Fund (NPIF) Debt Funds managed by FW Capital and Mercia Asset Management, the Midlands Engine Investment Fund (MEIF) Debt Fund managed by The FSE Group, and the Northern Ireland Growth Finance Fund managed by Whiterock Finance.
Following their approval, each lender will be putting in place the operations required to start lending under the scheme and will confirm shortly the dates from which they will be ready to start receiving CBILS applications from smaller businesses across the UK.
Keith Morgan, CEO, British Business Bank, said: “Our accredited lenders have seen an incredible demand for Covid-19 business loan schemes since they became available. Accrediting these four additional regional finance providers means further support for smaller business customers and continues the British Business Bank’s long-term objective to offer more diverse sources of finance to smaller businesses.”
Government published statistics show businesses have to date[1] benefitted from over £22 billion in loans and guarantees to support their cashflow during the crisis through schemes delivered by the British Business Bank. This includes 40,564 facilities worth £7.25bn through the Coronavirus Business Interruption Loan Scheme.
The accelerated accreditation process the British Business Bank has put in place for coronavirus schemes means it has been able to increase the number of lenders on the CBILS scheme by 90% since the scheme’s launch, increasing the number from 41 to 78.
The Bank continues to review applications from a wide range of lender types – from PRA-regulated banks, to platform lenders, debt funds, invoice finance lenders, asset finance lenders and responsible finance lenders.
_______________________________
[1] Latest figures published by HMT, 19 May 2020
- 06:00 am

The Board of Managing Directors of Commerzbank AG has decided to launch an issuance programme for additional tier 1 capital (AT1). This will enable the Bank to gradually issue subordinated bonds with a total nominal value of up to €3 billion. A decision on the first issuance under the programme will be taken at a later date.
“Over recent years, we have built up a strong CET 1 position. We are creating a framework with the AT1 issuance programme that can be used flexibly. This will enable us to further optimise our capital structure and also respond to the additional business opportunities that have arisen for us in the context of the coronavirus crisis and the changed regulatory requirements,” commented Bettina Orlopp, Chief Financial Officer of Commerzbank. “The programme will give us the opportunity to act rapidly in response to the capital requirement and the market environment.” The issuance programme also enables Commerzbank in future issuances to make use of the recent regulatory changes, whereby AT1 can now be used to a greater extent to meet the capital requirements (SREP).
The basis for the issuance programme is the resolution relating to the authorisation for the Board of Managing Directors passed by the Annual General Meeting in 2019 to issue once or more than once hybrid bonds up until 21 May 2024 which meet the requirements for regulatory recognition as additional core equity. It is planned to exclude the subscription right of the shareholders from the issuances of the programme. In July 2019, Commerzbank issued its first additional tier 1 bond with a volume of 1 billion US dollars. At the end of March 2020, the common equity tier 1 ratio (CET 1 ratio) stood at 13.2 percent and therefore exceeds all regulatory requirements.
- 04:00 am

Inclusivity Solutions, the company that designs, builds, operates and innovates digital insurance solutions, has secured an additional US$ 1.3 million in its second tranche of its Series A round, bringing the total Series A round to US$2.6m. Following on from their first tranche investment, the uMunthu fund, managed by Goodwell Investments, led the round with follow-on investment from UW Ventures (in partnership with Allan Gray). MFS Africa, a leading Pan-African fintech company, joined the round as a new investor. The timely move underscores the commitment by investors to the growth of inclusive digital insurance solutions dedicated to addressing risks, such as COVID-19, faced by the majority underserved consumers in emerging markets.
Inclusivity Solutions has already successfully launched digital insurance initiatives in Cote d’Ivoire, Rwanda and Kenya, in partnership with Orange, Airtel and Equity Bank’s Equitel respectively. Collectively a range of hospital cash and simple life products have provided protection to more than 700,000 people. The investment will be used to deepen the company’s footprint within its existing markets, support further international expansion as well as accelerate innovation in the backbone technology platform, ASPin, which underpins the three existing products.
Founder and CEO, Jeremy Leach commented: “As the humanitarian and economic disaster that is COVID-19 unfolds, we are reassured that there could not be a more important time for insurance solutions such as ours to play a role in protecting the vulnerable. This investment provides the endorsement and support that we need as an organization to continue our work in designing and scaling products that address the risks that really matter and can play a real role in adding value to consumers, as well as offering a digital-ready solution to insurers during operationally challenging times.”
Wim van der Beek, managing partner Goodwell Investments: “We are excited to lead this second tranche and make this additional investment from our uMunthu fund, especially in these challenging times. Our investment focus is inclusive growth, and we believe that collaborative insurtech solutions like Inclusivity Solutions are best positioned to reach large numbers of underserved consumers. Their model bridges the insurance protection gap for underserved through products that are designed to be simple, affordable and accessible, even on the most basic mobile phone. It is a perfect fit with our mandate, and we look forward to continue to support Inclusivity Solutions in its next stage of growth.”
“We could not think of a more relevant time for this additional support to Inclusivity Solutions to further their mission of designing innovative and inclusive financial products while developing insurance markets to protect and serve vulnerable communities across the developing world. We believe there is a huge opportunity to bring affordable health and life insurance to those communities that may be the most ill-equipped to deal with catastrophes such as COVID-19, and we are excited to partner with Jeremy Leach and his exceptional team to help achieve their ambitions.”Harry Apostoleris, Director, UW Ventures.
Dare Okoudjou, founder and CEO of MFS Africa commented, “I’ve known the Inclusivity team for many years, and as players in the fintech space ourselves, we have had the opportunity to collaborate with them on a few exciting opportunities. We share a passion for impact through technology, and a drive to innovate and implement. We at MFS Africa are very proud to be part of their next stage of growth.” Okoudjou added, “The investment was made through MFS Africa Frontiers, a vehicle dedicated to exploring Frontier opportunities in the greater fintech ecosystem. Through MFS Africa Frontiers, we invest in select ventures with whom we feel we can go further – and faster – together.”
Consumers such as primary school teacher, Peter, are now benefiting from these products. Through Riziki Cover, a product designed and operated by Inclusivity Solutions and delivered through Equitel in Kenya, Peter was able to cover his bills after being hospitalized for five nights.
Jeremy Leach: “Our obsession is to build products that directly meet the needs of consumers, consumers like Peter, and to make them simple to understand and easy to use. With insurance penetration at only 5.5 per cent of the adult population in Kenya, Peter would likely be without insurance today were it not for our innovative products. We are grateful and excited to have the support of these leading investors and partners who share our vision for a world with better protection.”








