
Published
- 03:00 am

Frost & Sullivan’s recent analysis, The Reshaping of Industries Caused by COVID-19, encompasses nine key trends that will emerge from industries reshaping as a response to COVID-19. With the pandemic’s negative impact on the global economy, immediate action is critical. Technology leaders must assess the emerging opportunities resulting from COVID-19 and provide technological innovations to build company, society, and consumer resilience.
"From transformative Mega Trends to geopolitical chaos, there are several factors making it increasingly difficult to grow,” said Murali Krishnan, Visionary Innovation Group Senior Industry Analyst at Frost & Sullivan. “In the near term, companies should focus on diversifying supply chains and leveraging new opportunities arising from changing customer demands. In the long term, it is important to internally adapt to new technologies that support workplace and operational continuity to have a smoother transformation during recovery.”
Chaitanya Habib, Visionary Innovation Group Research Analyst, added: “The shift in focus on cost optimisation and on avoiding further production losses post-COVID-19 has accelerated the adoption of automation and industrial robots across various industries. As a result, the global industrial robotics market is expected to grow from $44.6 billion in 2020 to $73 billion in the next five years, with increasing FDA approval and patent activity.”
The nine key trends across industries that will emerge as a result of COVID-19 are:
- Connected Living: The increased adoption of contactless surfaces post-pandemic will power the home automation and security markets. Systems encompassing voice activation technology will become increasingly popular among consumers.
- Connected Work: Reformed connected work scenarios will accentuate the need for “cloud everything.” New subscription-based models will witness a growing demand for Unified Communications as a Service (UCaaS).
- Digital Health: Digital health driven by telemedicine and robotic care will become the new standard of care delivery. Standardisation of service across the care continuum will require more service and technology providers.
- Geopolitical Balance: Countries should work together to keep trade flowing and ensure the supply of essential products, sending a signal of confidence to the global economy.
- Human Augmentation: The behavioural analytics market is expected to reach $3 billion in revenue in 2030, up from $230 million in 2019. Post-COVID-19, behavioural data will be used to enhance healthcare systems, financial services, and cybersecurity.
- Lights-out Operations: Autonomous “lights-out” operations will propel the demand for remote asset management solutions, and service providers will focus on data management strategies and data-driven business models.
- Smart Cities: Smart cities will create significant business opportunities with a market value of $2.46 trillion by 2025. Smart cities will prioritise more digitalised services and a strong data analytics infrastructure, leading to increased spending on technology.
- Supply Chain Optimization: The supply chain industry is creating radical innovations with augmented reality, virtual reality, advanced robotics, real-time inventory tracking, and exploring how 3D printing could completely disrupt the supply chain in the next 10 years.
- Technology Advancements: Pandemic preparedness will speed up the deployment of artificial intelligence (AI) solutions and accelerate AI innovation. Beyond specific disease management, post-pandemic economies also will rely on AI and machine learning (ML) tools to expedite digital transformation across key business initiatives.
The Reshaping of Industries Caused by COVID-19 is the latest addition to Frost & Sullivan’s Visionary Innovation Group research and analyses available through the Frost & Sullivan Leadership Council, which helps organisations identify a continuous flow of growth opportunities to succeed in an unpredictable future.
- 07:00 am

Cohesity announces Cohesity SiteContinuity, an automated disaster recovery solution that is integrated with the company’s backup and continuous data protection capabilities – making it the only web-scale, converged solution to protect applications across tiers, service levels, and locations on a single platform. Cohesity is making this announcement as organizations are concerned about losing data to ransomware attacks, natural disasters, or human error. This new integrated solution will help companies ensure data is not lost, applications are available, costs are reduced – by eliminating redundant or unnecessary infrastructure – and that strict service-level agreements (SLAs) are met.
Today, many companies are not equipped to meet critical recovery objectives. In a recent study published by the Enterprise Strategy Group (ESG), when respondents were asked if their actual recovery times met their pre-established SLAs, 78 percent stated they are unable to “always” meet their objectives and 33 percent said they “sometimes” or “rarely” meet these objectives.*
“Maintaining the integrity of our data in the face of a disaster or attacks is crucial and protecting our applications and data across various SLAs is complex and challenging,” said Steve Culy, senior systems engineer, Navis. “The new solution from Cohesity is very timely as it allows us to protect our mission and business-critical applications on a single platform. We can now automate our business continuity and disaster recovery strategy, all from Cohesity’s data platform, making it easier for us to manage SLAs, and reduce downtime with automated, rapid failover and failback.”
“Cyber threats such as ransomware and growing natural disasters such as hurricanes or wildfires increasingly put critical applications and data at risk,” said Matt Waxman, vice president of product management, Cohesity. “With that backdrop, this is an ideal time for IT leaders to rethink how they can simplify IT operations while also reducing costs with an integrated, web-scale, converged backup and disaster recovery solution.”
Elevating Business Continuity and Disaster Recovery
With Cohesity SiteContinuity, organizations can recover a single file, critical business application, or an entire data center with just a few clicks, automating recovery operations spanning across application tiers and on-premises and public cloud environments. It dramatically simplifies the challenge organizations face in trying to manage complex hybrid and multi-cloud IT environments with numerous applications running across multiple tiers with varying service levels during the course of normal operations. Cohesity’s converged backup and disaster recovery solution provides:
- Simplified operations: Consolidate backup, continuous data protection and automated disaster recovery on a single platform, managed through one global UI and a unified policy framework, across application tiers, service levels, and environments.
- Near-zero application downtime and data loss: With just a few clicks, automatically orchestrate failover and failback of a single application or an entire site, ensuring minimum data loss and downtime as business applications are rapidly recovered in a disaster scenario.
- Flexible recovery: Journal-based recovery helps to meet varying service levels across application tiers by restoring to any point in time — including days or even seconds before the disaster hit, on-premises or to the public cloud.
- Machine learning-based ransomware detection and recommendation: At the time of failover and/or restore, Cohesity Helios’ machine learning algorithm helps identify a clean point in time to restore. This helps protect the DR site from malware impact during the failover process.
- Disaster testing: Meet DR compliance objectives with confidence through end-to-end automated non-disruptive disaster recovery testing, including complete audit trail reporting.
- Reduced TCO: Reduce costs by converging backup and DR, eliminating the need for separate point products and driving better storage efficiency. Further reduce data footprint and costs with global variable-length deduplication and compression across workloads. Additionally, there is no need to deploy dedicated virtual machines to support recovery of each ESXi host.
- Limitless scalability: The underlying web-scale architecture of the Cohesity platform enables organizations to scale BCDR capabilities limitlessly and painlessly.
“Application availability and protecting data against disasters is vital for us,” said Francois Lepage, cybersecurity and infrastructure manager, Master Group. “And, we believe this new solution from Cohesity could easily empower organizations to strengthen their business continuity and disaster recovery strategy. A single platform that can automate DR orchestration, while also managing backups from a single policy has the power to be a transformative technology.”
“Business continuity continues to increase as a priority for many end customers. When a disaster strikes, they need simple, quick recovery as downtime and data loss are not an option,” said Brian Ellis, vice president, advanced solutions, Tech Data. “Cohesity’s new solution offers converged backup and automated DR on a single platform with automated failover and failback orchestration for near-zero downtime. This solution changes the game for our partners and their customers.”
“With the increased frequency and cost of cyberattacks, a robust set of disaster recovery processes combined with proven technology have never been more essential,” said Christophe Bertrand, senior analyst, ESG. “Organizations should look for ease of use, automation and the ability to truly control their data recovery and application availability service level agreements. That’s why Cohesity's web-scale converged backup and disaster recovery solution is not only timely, but also offers a comprehensive set of capabilities to take on the disaster recovery challenges enterprises face.”
This solution will be generally available in the fourth quarter of the calendar year 2020.
- 02:00 am

Rimilia, the leading SaaS-based fintech company, today announced the results of its two year partnership with Aston University to boost artificial intelligence (AI) expertise among Rimilia’s employees and enhance its intelligent financial management solution.
The collaborative project was a part of the Knowledge Transfer Partnership (KTP), a Government funded initiative that allows companies to access the expertise of a university’s academic community. The KTP links the industry with specialised academic researchers to provide businesses with expertise that reside at universities and apply the theoretical knowledge to real-life issues, creating a two-way relationship between both parties.
The initial project between Aston University and Rimilia involved building and testing a payments forecast engine, however the impressive results encouraged both teams to go further in-depth into the AI possibilities.
Since starting the project in October 2017, Aston University’s researchers and Rimilia’s team have engaged in developing and designing new products at Rimilia. The first outcome led the introduction of Insight – Rimilia’s cutting-edge solution which uses AI-powered customer behavioural analysis and customer segmentation to link the customer front office to business’ finance back office.
The KTP initiative also allowed for upskilling and re-educating companies such as Rimilia in different aspects related to data science and machine learning. Employees at Rimilia had the opportunity to improve their expertise in how and in which areas AI can help boost the company’s solutions, enhancing performance and increasing the market share. In addition, the project helped established the special requirements and the infrastructure Rimilia needs to meet to benefit from AI expertise.
The collaboration also brought positive results across the company at Rimilia and enabled it to increase brand exposure and drive product sales. The ground-breaking research uncovered how AI could be used to track debtor behaviour, and was shared at a number of national and international conferences, seminars, webinars, and during both prospect and customers visits. The research provided a boost of £220,00 in additional sales for Rimilia, with the team expecting this number to increase to £1.8m in over the next three years.
The project was run by lead Data Scientist and KTP Associate, Dr. Ali Rezaei Yazdi who commented: ‘‘Companies often overlook academic research, however I believe theoretical knowledge and technical skills must be blended with awareness of business requirements and business expertise to achieve great results. I'm proud to say that Rimilia, in comparison to many companies in the same market, has a much better understanding of the data and the importance of data cleaning and processing. The project has been an engrossing challenge which inspired me to join Rimilia and help the company continue to innovate.’’
“In addition, the Knowledge Transfer Partnerships are a great opportunity for academics to get a reality check and re-focus on issues directly of interest to a sector from industry.’’
Steve Dunn-Massey, CFO at Rimilia, added: “The project has been a huge benefit to Rimilia in helping develop its next generation of innovative products. As a company, we are committed to enhancing the variety and quality of our offering to meet the growing demands of today’s industry challenges.”
- 03:00 am

Nexi, the leading Italian PayTech in digital payments, signs a partnership with Ebury, one of the world's leading Fintech companies providing global transaction banking services to businesses.
According to the agreement, Ebury, founded in 2009 and with offices in 20 countries including Italy, joins Nexi Open. Nexi's partner banks will be able to offer their clients the full suite of Ebury services, including international cash management, FX risk management and import/export lending.
Credit institutions will be able to expand their global transaction services with innovative solutions to overcome some of the traditional complexities of cross-border transactions. For example, Ebury International Cash Management services allow customers to open multi-currency accounts in a few hours; FX Risk Management services help businesses to reduce the risks associated with international trade; the single platform for cross-border payments gives customers a simple and transparent way to pay suppliers in over 200 countries and over 100 currencies.
Ebury’s services will be offered to businesses via an advanced technology platform, easily integrating within the bank’s digital infrastructure, enabling efficient access to the services and strengthening the relationship between the bank and its clients.
Ebury’s business model also involves the support of dedicated specialists to help both the bank’s relationship managers to maximize the customers’ engagement and the SME clients to start using the new services.
“The collaboration with Ebury allows us to support Italian banks that want to expand their global transaction services to SME and Corporate clients, who are increasingly looking to compete cross-border,” Renato Martini, Head of Digital Banking Solutions at Nexi commented. “Our bank partners will be able to offer relevant services for Italian SMEs that are importing and exporting and strengthen the relationship with their clients by seamlessly integrating Ebury’s services into their digital offering for businesses.”
“We are very excited about our partnership with Nexi and how it will accelerate our collaborations with Italian banks to expand their transactional services for businesses that trade internationally,” Mauro Miotto, Global Head of Partnerships at Ebury said. “Ebury’s mission is to help SMEs grow in the global market and by partnering with other financial institutions we believe we can offer the best of both the Bank and the Fintech propositions, and to increase the support to businesses.”
- 01:00 am

SteelEye, the compliance technology and data analytics firm, has been selected by the world-class investment manager, Schroders.
The FTSE100 listed global investment manager with over £500bn assets under management deployed SteelEye in July 2020.
SteelEye is designed to provide clients with full visibility of their entire MiFID II transaction reporting workflow, including efficient and automated tools that enable them to easily and seamlessly manage any over or under-reporting, as well as data validation errors. SteelEye provides:
• Sophisticated MiFIR eligibility checks
• Analytics on rejection handling from both the Approved Reporting Mechanism (ARM) and National Competent Authority (NCA)
• MiFIR data validation rules
• The ability to edit transactions directly within the platform
• A full audit trail of all activity
• Automatic submission schedules
“The SteelEye implementation has helped us to improve the level of control and accuracy we have around our MIFID II transaction reporting,” said Keith Frimpong, Global Head of Operations Change at Schroders. “We selected SteelEye because of the quality of their technology, the expertise demonstrated by their team and their willingness to support our tight implementation timelines.”
Schroders operates from 34 locations across Europe, the Americas, Asia, the Middle East, and Africa. The two century-old business offers both asset management services to institutions and private investors as well as a wide range of wealth management services which focus on preserving and growing their clients’ wealth.
“MiFID II Transaction Reporting was the first RegTech service on the platform when we launched SteelEye in October 2017. We are honoured to partner with Schroders and delighted they recognise the value in our reporting solution. This reassures us that our data-centric compliance platform truly addresses an industry need,” added Matt Smith, CEO of SteelEye.
SteelEye reduces the complexity and cost of compliance by enabling financial firms to manage their regulatory obligations through a single platform. SteelEye’s extensive range of services include regulatory reporting for MiFID II and EMIR, trade and communications surveillance, best execution, transaction cost analysis, record keeping, trade reconstruction, analytics and more.
- 09:00 am
National Australia Bank (NAB) is partnering with Pollinate to transform their merchant acquiring offering for small and medium sized businesses (SMEs) across Australia.
SMEs are of vital importance to the Australian economy, driving over half of the country's economic output, and employing two in every three Australian workers. One third of Australian SMEs bank with NAB, and supporting them has never been more important. Central to this support is the ability for SMEs to access the digital tools and payment solutions historically only available to larger businesses.
NAB’s implementation of Pollinate’s global cloud-based platform will help their SME customers better manage and grow their businesses. In Australia only 54% of small firms use digital invoicing and accounting relative to 78% of large businesses 1. The Pollinate platform brings these and other digital services to SMEs through a single platform. Working seamlessly with NABs existing merchant acquiring infrastructure, the Pollinate platform gives SMEs business insights, integrations with third-party applications (such as accountancy) and the ability to run digital loyalty programs.
Andrew Irvine, NAB’s Group Executive for Business & Private Banking, said NAB was focused on delivering innovative products for small businesses to help them succeed. He added: “Real-time data that delivers greater insights into what customers want, when and how they want it, can be transformative to a small business. Leveraging Pollinate’s platform, NAB will be able to give businesses the information they need to make decisions about their daily sales at their fingertips.”
By working with Pollinate, NAB is the second bank to join a global network, dedicated to bringing the next generation of merchant services to businesses around the world. The platform was launched as Tyl by NatWest in the UK in September 2019. Pollinate’s model is to work with one leading bank in each geography, and is in advanced discussions in South Africa, Canada and other regions. NAB also joins NatWest, Mastercard, EFM Asset Management and Motive Partners as an investor in Pollinate, bringing the total amount raised to £70m.
Al Lukies CBE, Pollinate Founder and CEO, said: “Banks around the world have had a difficult decade, but they remain the only ones in the payment chain who can connect directly with both merchants and consumers. NAB is ideally placed to create a virtuous circle between the bank, its business customers and the communities they serve. We are honoured to be their partner of choice in Australia.”
2 The Australian partnership with NAB follows Pollinate’s global strategic partnership agreement with Mastercard, which was signed in August 2020. This deepened Mastercard’s relationship with Pollinate to a formal collaboration to bring the latest technology and data insights to banks serving SME customers around the world. The agreement covers product development, business development and marketing efforts across Europe, Africa, Asia and the Americas.
- 07:00 am

NYMBUS®, a leading provider of banking technology solutions, announced the Board of Directors has appointed Jeffery Kendall to serve as the company’s Chief Executive Officer, effective October 1, 2020. Kendall succeeds the company’s founder, Scott Killoh, who will continue to serve as Executive Chairman of the Board and trusted advisor to the management team.
Kendall is an experienced leader in the digital technology space, bringing a depth of operational knowledge along with a proven track record of scaling high growth companies. Notably, he served as the Executive Vice President and General Manager of Kony DBX where he grew the digital banking division by 500 percent in two and a half years, leading to an acquisition by Temenos in 2019 for $520 million.
In his new role, Kendall will help NYMBUS further capitalize on the massive opportunity presented by a fintech market that continues to explode in growth and is in top demand as financial institutions are seeking digital transformation. A unique alternative to the legacy business model, NYMBUS has disrupted the industry by enabling risk-free solutions for traditional banks and credit unions to rapidly innovate, digitize and grow their businesses.
“With over a decade of investment in our award-winning portfolio and rising customer success, NYMBUS is poised to become a fintech market leader,” said Killoh. “Jeffery’s strong domain and go-to-market expertise delivers the right leadership at this critical time when more financial institutions are seeking our proven and risk-free strategies to quickly digitize their banking operations and customer-facing channels.”
As Executive Chairman, Killoh will continue to lead operations and be actively involved in NYMBUS’ market advancement. He will chair the board of directors, act as an advisor to Kendall and be involved in the company’s long-term business strategy.
Added Peter Sobiloff, Managing Director at Insight Partners and NYMBUS board member: “Jeffery’s phenomenal business-scaling track record, combined with a deep understanding of the digital banking market and its customers, make him the clear choice to accelerate the company’s continued growth and expansion. On behalf of the entire board, we look forward to working closely with Jeffery as he helps take NYMBUS to the next level.”
“I am honored to join this exceptional team,” said Kendall. “In record time, NYMBUS has already delivered over 25 successful customer deployments. This is a powerful validation of the efficacy of our robust software and solutions, and the trajectory for continued success and growth by remaining focused on serving our clients, creating significant value for our shareholders and providing exceptional opportunities for our employees.”

N/A
N/A at N/A
The global impact of COVID-19 has been nothing short of immense. see more
- 04:00 am
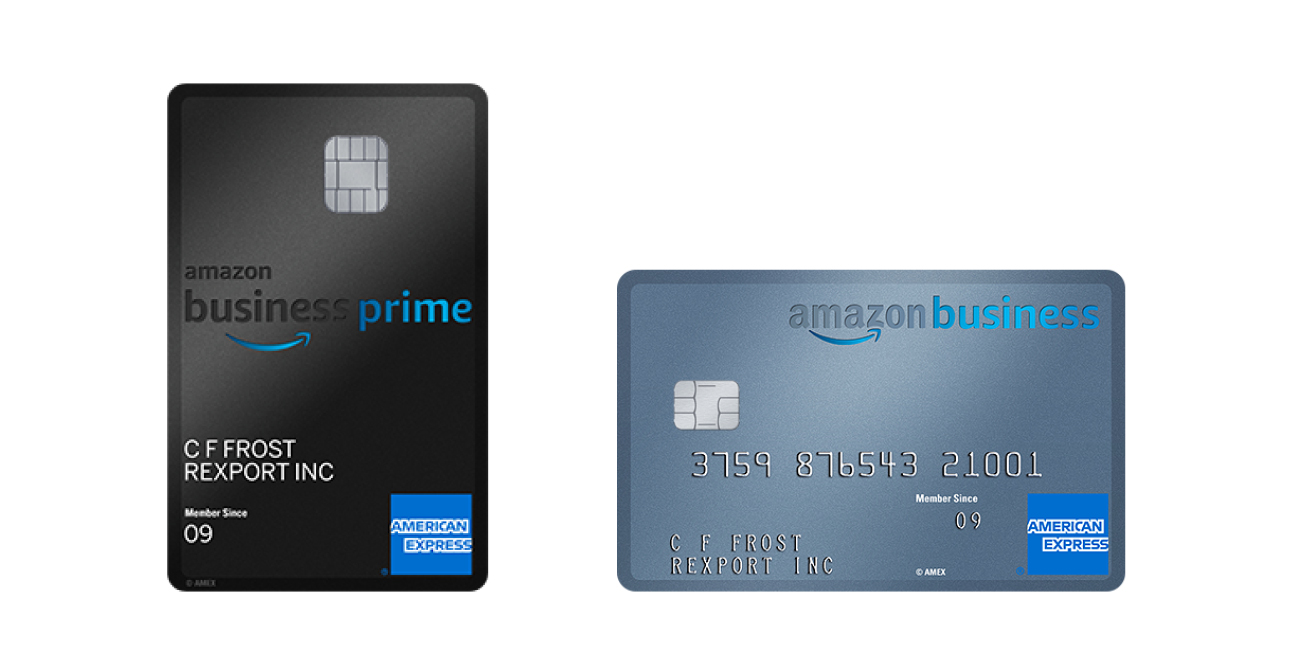
American Express (NYSE: AXP) today announced the launch of the new Amazon Business American Express® Card and the Amazon Business Prime American Express® Card for small businesses in the UK. The Cards offer a host of rich rewards and payment flexibility designed to help businesses better manage their cash flow and gain greater insight into their spending.
The Cards provide an enhanced check-out experience on Amazon Business UK and Amazon.co.uk that gives Cardmembers the option to earn reward points or select a deferred payment term for each transaction, enabling them to make the best payment choice for their finances. Reward points can be earned anywhere American Express Cards are accepted and redeemed toward future Amazon purchases or applied to the balance of their monthly Card statement. This new Card programme in the UK has been developed as part of the on-going relationship between American Express and Amazon which includes a co-branded programme in the US and a global Card acceptance relationship.
This launch comes at a time when 63% of British small businesses say cash flow issues have led them to delay purchasing goods and services they need to run their business, according to new research from American Express and YouGov1. Nearly a quarter (23%) of the survey participants said they have put off ‘bigger ticket’ purchases over the last six months until they have funds available, and 38% of them are only buying the ‘essentials’ they need to keep their business operating.
Commenting on the new Card launch, Colin O’Flaherty, General Manager of UK Global Commercial Services at American Express, said: “We have been serving small businesses for over 60 years, and are passionate about helping our small business customers effectively run and grow their businesses, especially during this challenging period. With many UK SMEs facing financial hardships, we want to make it easier for businesses to manage their finances and continue accessing the goods and products they need with more options to pay. We know that a vast number of the UK’s businesses rely on Amazon’s wide-ranging products and services and are excited to launch this powerful and flexible new payment tool that will allow small businesses to select how to pay, purchase by purchase.”
Dave Brittain, Director of Amazon Business UK, said: “Working with American Express to launch the small business credit Card was a natural decision for Amazon, given our shared long-standing commitment to helping small businesses flourish globally. We’re incredibly proud to launch this Card programme as it offers small business owners and entrepreneurs the best of both companies: the convenience and value they have come to know and love from Amazon, underpinned by the world-class service, benefits, access and security of American Express. These benefits have never been more important at a time when businesses are navigating the challenges and uncertainty which Covid-19 has presented.”
Amazon Business American Express Cardmembers and Amazon Business Prime American Express Cardmembers will have access to the following key benefits:
- 2% Amazon Rewards points on the first £120,000 in purchases at Amazon.co.uk, Amazon Business UK and Whole Foods Market UK each calendar year, 1% thereafter or 90-day payment terms on such purchases for Cardmembers who are Business Prime members on Amazon Business UK
- 1.5% Amazon Rewards points on the first £120,000 in purchases at Amazon.co.uk, Amazon Business UK and Whole Foods Market UK each calendar year, 1% thereafter or 60-day payment terms on such purchases for all other Cardmembers
- 0.5% Amazon Rewards points on all other purchases for all Cardmembers
Both Cards come with a £50 annual fee, however, this is waived for new Business Prime American Express Cardmembers in the first year. Upon approval, new Cardmembers who are Business Prime members will receive an Amazon gift card with £50 value, and all other Cardmembers will receive a £25 Amazon gift card. As an added benefit for Amazon Business Prime American Express Cardmembers, their Cards will feature a unique vertical design that is composed of metal.
Terms and conditions apply. To learn more about the Amazon Business American Express Card, visit americanexpress.com/uk/amazonbusinesscard.
- 05:00 am

As announced earlier, Ian Smith has been appointed Nordea’s new Group CFO, heading Group Finance. He will be a member of the Group Leadership Team and report to President and Group CEO Frank Vang-Jensen. It is now confirmed that Ian Smith will join Nordea in October 2020 and take on the position on 24 October 2020.
"I warmly welcome Ian to the Nordea team. I’m pleased to get him on board and look forward to working with him towards our common vision to be a strong and personal financial partner. At the same time I would like to thank Mark Kandborg, Group Treasurer, Head of Treasury & Asset and Liability Management, for stepping in as acting Group CFO and for his good work and efforts in this role," says Frank Vang-Jensen.
Nordea is the leading Nordic universal bank helping customers realise their dreams and aspirations. The Nordea share is listed on the Nasdaq Helsinki, Nasdaq Copenhagen and Nasdaq Stockholm exchanges.
Read more about the company on nordea.com.








