
Published
- 09:00 am

Bitcoin bolstered as Amazon appears to dip its toe into crypto world.
Susannah Streeter, senior investment and markets analyst, Hargreaves Lansdown
‘’When a simple job ad appears to spark resurgence in the value of Bitcoin, it shows how the crypto world is salivating for every nugget of news about the future use case for digital currencies.
Although Amazon has scores of openings for blockchain specialists, it was the listing for a digital currency and blockchain product lead that has led to heightened speculation that crypto currency payments could be integrated on its platforms.
Given the might of Amazon Web Services, it isn’t surprising that the tech giant wants to be at the cutting edge of new payments technology and establishing a new digital currency is likely to be on the agenda. But the expectation that payment may also be accepted from the current crypto kids on the block has also led to a spike in their value. Over the past 24 hours Bitcoin has risen by 11%, Ethereum by 8% and Dogecoin by 11%.
Crypto fans are also hanging on every word of Elon Musk and his hint that Tesla could start accepting Bitcoin again is also behind the crypto bounce. The suspension of Bitcoin as a means of payment for Tesla cars sent the crypto world reeling in May, but in a debate with Twitter CEO Jack Dorsey, Mr Musk indicated that could change given mining has reached a tipping point, with much more renewable energy used instead of fossil fuels.
Crypto assets are also largely following sentiment in financial markets. The sharp fall in stock markets around the world a week ago, was mirrored in the crypto world, and the rebound came as fears receded about the impact of new variants on economic recovery.
The sensitivity of crypto coins and tokens remains stark, and given the uncertain landscape ahead, with central banks looking to develop their own digital coins, investors should be wary of speculating with money they can’t afford to lose.’’
- 09:00 am
Lightspin, the next-generation cloud security platform, announced today that CRN®, a brand of The Channel Company, has included Lightspin in its 2021 Emerging Vendors List in the Security Category. This annual list honors up-and-coming technology vendors—all six years old or younger—that have proven their commitment to innovation and growth within the larger IT channel by enabling solution providers to tackle complex IT market challenges, increase bottom-line revenue across the board, and deliver customer-facing solutions that ensure the channel’s ongoing success.
Founded in 2020, Lightspin provides a contextual cloud security platform for cloud-native and Kubernetes environments that includes a full contextual view of all cloud assets and relationships, maps the potential attack paths and prioritizes and remediates the most critical security issues from build to runtime.
“Our solution has an immediate impact with the ability to leverage sophisticated inputs from multiple sources to detect and prioritize risk early on in the development cycle, to significantly reduce the number of threats reported. The result is effective protection with instant security fatigue relief,” said Amber Katz, Head of Business Development. “Lightspin is financially rewarding for partners as it is quick and easy to deploy and integrate, and incorporates intuitive visualization tools that boost user experience and make it easy for customers to study their cloud environment and take insightful actions.”
Deployed in companies ranging from startups to Fortune 500 corporations, Lightspin has been experiencing exceptional market growth. Recently completing a $16 million Series A funding round Lightspin was awarded the CDM Global Infosec Award for Hot Company in SaaS/Cloud Security at RSA 2021, and Gold for Security Cloud/Saas Start up of the Year award as part of the 13th 2021 annual Golden Bridge Business and Innovation awards.
- 05:00 am

The distributed, complex management of paper-based invoice processing is a burden that weighs down many businesses, leading to large time delays and huge risks of error. This was proven to be the case in a recently commissioned independent research project that showed 23% of businesses took more than 10 working days to process invoices, and 29% of these were unable to process them in less than 20 days.
Coastline Housing rectified this issue by implementing Invu Document Management and Workflow, which has now streamlined their entire process and freed up staff time to do more productive and valuable work.
Zoe Field, Head of Finance at Coastline Housing, noted that, The feel-good factor we get from the Invu system is amazing. You would not believe the messages I have had from users saying how much easier the system has made their job.
Invu Document Management brings increased visibility, control and efficiency to business documents. Combined with Workflow, which automates business processes, Invu Document Management enables businesses to process, share and store documents, like supplier invoices.
Ian Smith, GM and Finance Director at Invu, said: Businesses of a certain scale frequently find that those responsible for the approval of invoices are spread across a wide range of different locations. Such distributed approval slows down supplier invoice processing. This puts pressure on finance teams who are often criticised for making late supplier payments and failing to respond to supplier queries promptly. Digitising the process can enable swift approval across many locations and ease the pressure on finance teams.
Before implementing Invu Document Management, Coastline Housing’s invoice processing was a manual, paper-based and time-consuming process, susceptible to human error. It also created frequent stress for the finance team who were overrun with paper. With invoice volumes reaching 24,000 invoices each year, the move to remote working, driven by the COVID-19 pandemic, created many challenges. In this new environment, the Coastline Housing finance team recognised that their paper-driven invoice approval process was no longer fit for purpose. Invoices could no longer be passed around the office to staff in-trays.
Field continues, Moving away from our Excel-based system was a massive driver for the project. Regardless of what you can do, human error always kicks in and it only takes one person to type something wrong and we have an issue.
Finance departments are coiled like springs waiting for this digital transition, and 44% of finance workers think that automating processes would make them more productive, with one in five (22%) claiming they would welcome automation in their business.
Smith concludes, With Invu Document Management, those responsible for approving invoices can be certain they are being fed invoices they should be approving, see the related documents, and take ownership of the coding. They no longer have to manage the documents in their in-tray or work out whether they should be the one to approve it. Nor do they have to feel they do not truly own the budgets for the departments or projects they are responsible for because Finance allocates everything.
- 06:00 am

- Barclaycard Visa credit cardholders can earn up to 15 per cent cashback at their favourite retailers online and in-store with the new Barclaycard Cashback Rewards
- The new rewards programme provides personalised offers at brands across retail, hospitality and leisure
- Cashback can be redeemed towards a credit card balance, traded up for an e-voucher, or donated to a customer’s preferred charity
- The new benefit is available to all new and existing Barclaycard Visa credit cardholders, who can find out more information at https://cashbackrewards.uk.barclaycard/
Barclaycard, which sees nearly half of the nation’s credit and debit card transactions, has announced a new Cashback Rewards programme with Visa giving shoppers automatic cashback when spending at a range of high street and digital retailers.
The programme provides customers with personalised offers towards their favourite brands, based on their previous shopping habits, when spending on their Barclaycard Visa credit card. Once signed-up, customers can start earning up to 15 per cent cashback when making purchases at a variety of well-known retailers including Uber Eats, Costa and Holiday Inn Express.
Customers can sign-up effortlessly by clicking through to the new Barclaycard Cashback Rewards site: https://cashbackrewards.uk.barclaycard/. Once registered, they then have access to personalised offers from their favourite UK retailers, both in-store and online.
The Barclaycard Cashback Rewards offers cardholders the opportunity to save money, as the easing of lockdown sees the return of more normal spending patterns, with Barclaycard data showing spending on non-essential items increasing by 9.4 per cent* in June 2021 compared to the same period in 2019.
In addition, complementary consumer research shows consumers continue to have value front of mind, with 40 per cent** shopping around for the best deals to make their money go further. Moreover, spending looks set to continue, as 20 per cent suggest they will be taking a staycation in the upcoming weeks.
Whether dining and drinking at a favourite eatery, taking a break in the UK or shopping at a much-loved retailer this summer online or in-store, the new Barclaycard Cashback Rewards will help Barclaycard customers make the most of their spending.
Cardholders can also have their cashback redeemed back to their Barclaycard, trade up for an e-voucher, or donate to a chosen charity. Those already earning cashback with an existing Barclaycard Rewards card could earn additional cashback of up to 15 per cent by signing up to the new Barclaycard Cashback Rewards.
José Carvalho, Head of Unsecured Lending said:” Our spending data shows that consumers’ shopping habits are changing. Not only do we all want more flexibility about where we shop, but we are also looking for better value for money in the purchases we make.
“Knowing how important this is to our customers, we are delighted to announce the new Barclaycard Cashback Rewards with Visa, helping cardholders get more out of their everyday spending on their Barclaycard. We have designed the rewards programme to provide tailored offers based on where our customers like to shop and most often, while also ensuring signing up is as seamless as possible with easy access to the rewards.”
Cathy Dargue, Client Director at Visa said: “We’re delighted to partner with Barclaycard for the new Barclaycard Cashback Rewards. Providing cardholders with the latest and best products has always been a crucial part of our longstanding partnership with Barclaycard, and the new programme will give cardholders access to better deals, and the opportunity to earn cashback - at a time when all of us are more conscious about how and where we spend.
“This has been a truly collaborative effort by both Barclaycard and Visa and we’re excited to give something back to customers though such a substantial rewards programme - providing better value when shopping at their favourite stores.”
To learn more and sign up today, visit: https://cashbackrewards.uk.barclaycard/
- 07:00 am
- Experience designed around the customer – offering simplicity and control
- Complete transparency: one, simple APR and no fees
- UK’s first truly virtual credit offering with no plastic card. CVV and full functionality delivered from within the app and digital wallet of the customer’s mobile phone
- Launched to waiting list of 30,000 with an estimated 14 million people in the UK having operated on a cashless basis last year
Available now via App Store and Google Play
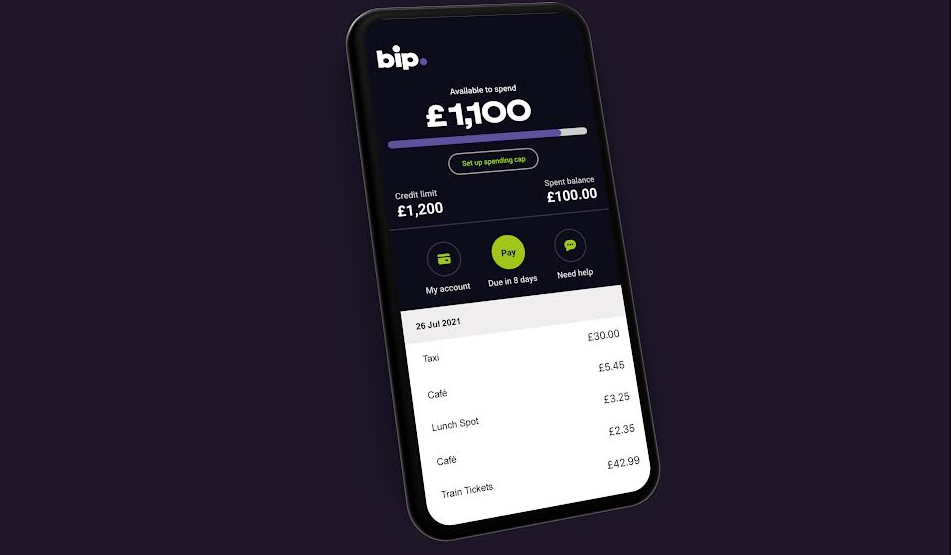
NewDay, a leading UK provider of accessible credit, has launched Bip – the first completely cardless consumer credit proposition in the UK. Bip has been designed around the customer, offering a fully digital credit experience that is simple to use, fully transparent on costs and with the customer in complete control.
With no physical card, Bip customers can apply and have access to appropriate credit within minutes. Bip (https://www.Bip.credit/) is available via the App Store and Google Play – and can be added to the digital wallet of the user’s mobile phone. Just like a traditional card, it can be used anywhere Mastercard® is accepted when making contactless or online payments.
Bip offers a transparent and seamless customer experience:
- No hidden fees – no annual, foreign exchange or late payment fees. Just one interest rate – typically 29.9% APR.
- Easy application process via the app. If eligible, users can be up and running in minutes. No need to wait for a card and PIN to be despatched by post.
- Paperless (and plastic-less) apart from regulatory required communications – for example letters regarding changes to credit limit.
- The full credit card experience (including secure access to CVV) via the app.
In addition, Bip has been designed to ensure the customer stays in complete control:
- Customers can set two kinds of spending caps to give them control – including a warning and a freeze cap within the app.
- Customers can also set spending alerts to ensure they remain in control.
- Customers can see how much they could save on interest with the Payment Calculator, allowing them to understand the impact on the interest they will pay by increasing their repayments.
- Everything is accessed through the Bip app – including a chat function to help customers service their account.
NewDay has involved its customers in the design of Bip from the start, producing a solution that truly meets their needs, which is evident from customer demand and initial feedback from the testing phase. The firm has successfully recruited a waiting list of over 30,000 customers through the development and testing of Bip. The product is rated ‘Excellent’ on Trustpilot, with a score of 4.5, with customers especially positive on aspects such as the ease of applying, simplicity of use and ability to track and cap spending (https://uk.trustpilot.com/review/www.Bip.credit).
Sharvan Selvam – Commercial Director at NewDay said: “We worked with our customers all the way through the design, testing and launch of Bip. It is a proposition designed to make credit easy to access, simple to use and, importantly, puts the customer in full control.”
Bip will be backed by a full consumer launch including mass market advertising later this year. Bip is the latest product from NewDay – one of the UK’s leading credit providers. NewDay offers credit to a broad spectrum of UK customers, providing accessible credit to close to 5 million people. This includes underserved sections of the market such as existing prime credit customers who may have seen their credit score reduced; and those new to credit who don’t have a full profile with the credit bureaux. At the heart of NewDay is its proprietary technology underpinned by two decades of underwriting experience and intelligence.
NewDay has seen digital wallet and contactless use of its other products more than double in the past year, from around 8% in August 2020 to 20% in June 2021 across customer retail spending. This is in line with wider trends, with 13.7 million people in the UK leading a “cashless life” last year (2020)1 and this accelerating due to the pandemic, and with the UK predicted to be a cashless society by 2026.2
Ian Corfield, Chief Commercial Officer at NewDay, added: “We have seen a huge shift in the number of consumers who are swapping their physical wallet for a digital one. Consequently, we believe Bip will have a wide appeal, from early adopters and tech savvy individuals through to more mainstream consumers who are now more comfortable using their digital wallets for payment. This is even more relevant today as changes in spending habits have been dramatically accelerated by the coronavirus pandemic, with cash use falling dramatically from 60% to just 15% of transactions, highlighting our acceleration towards becoming a cashless society.
“Bip is a manifestation of everything we are at NewDay: responsible, transparent and accessible. We want to help our customers – whether they are retailers or consumers – move forward with credit.”
- 06:00 am
Baton Systems, the market solution transforming asset movements and settlements, today became a signatory to the updated FX Global Code, underscoring its commitment and support to firms keen to eliminate settlement risk by enabling real time, payment-versus-payment (PvP) settlement for all market participants.
Principle 35 of the updated FX Global Code strengthens previous guidance, advising “Market Participants should reduce their Settlement Risk as much as practicable, including by settling FX transactions through services that provide PVP settlement where available.”
Baton allows all market participants to reduce settlement risk, by providing on demand PvP settlement for real assets, in real accounts held at commercial banks. Since the solution was initially deployed, Baton has facilitated the PvP settlement of trillions of dollars.
Baton’s transformative PvP solution utilises secure distributed ledger technology (DLT), deployed through the cloud using a single tenant architecture, without the need for tokenisation. Backed by a robust rulebook, Baton currently facilitates PvP settlement in 18 currencies across a spectrum of G10 and EM currencies. In addition, Baton provides participants with the flexibility to settle when it best suits their funding profile, with access to real time netting and payment strategies. Delivering transparency, auditability and configurable automated workflows, Baton is opening up the benefits of PvP settlement protection to all.
Arjun Jayaram, CEO and Founder of Baton Systems commented “The world of clearing and settlement is on the threshold of revolutionary change. We see the updated FX Global Code as validation that today’s status quo for settlement risk and liquidity management must evolve. There is a clear need for safer and more robust settlement protocols for all currencies and all market participants.”
- 06:00 am
4 percent rise in credit card spend and 10 percent increase in payments to balance reflects continued use of pandemic savings, plus pragmatic financial management with end of government support on the horizon
Highlights
Third consecutive monthly increase in credit card spend – but growth rate slowing at 4 percent
Percentage of payments to balance increased for the second time since December, by 10 percent
Average balances on accounts with three missed payments 8 percent higher year on year
Cash usage continues to slowly grow – by 6 percent
Global analytics software provider FICO today released its analysis of UK card trends for May 2021, which suggests that some consumers are practicing pragmatic financial management, as well as continuing to make use of savings accrued during the pandemic. There are, however, warning signs of the financial pressure growing for those already in debt.
Whilst the effects of a full month of retail and hospitality re-openings were reflected in a further rise in card spend, the increase was just 4 percent compared to the 12 percent increase seen in April. This suggests that consumers foresee future pressure on income with the prospect of furlough support and payment holidays ending.
The percentage of payments to balance continued to increase - by 10 percent month on month. However, an 8 percent year-on-year increase in the average balance for accounts with three missed payments and a growth in the use of cash on cards – 6 percent – will ring warning bells for lenders.
June data will highlight the impact of a full month of the last stage of lockdown prior to the end of the final retail and entertainment restrictions. The ability of issuers to react swiftly and appropriately to sudden changes in their customers’ financial conditions will be tested over the coming months. Those who can detect and act upon the early warning signs accurately with a wide and flexible range of treatments and a robust collections strategy will provide the most benefit to their customers.
Spend on UK cards continued to increase, along with the percentage of payments

The average spend on UK credit cards increased for the third consecutive month, by £26 to £651 in May 2021. However, the monthly increase may not be as high as some might have been expecting for the first full month of the easing of lockdown restrictions, especially compared to the growth seen in April.
Some consumers receiving furlough payments may be showing caution relating to their spending levels, ahead of the planned scaling down of the government contribution as of 1st July. This caution could also be the reason that the percentage of payments to balance continued to increase — by 10 percent month on month to 36 percent, the highest ratio over the last two years.

Average balances on accounts missing three or four payments continue to grow
The percentage of accounts which have missed only one payment increased in May. June’s results will show if there is a segment of consumers where spend in April was unaffordable and so will miss their second payment.
Accounts missing one payment are £25 lower than a year ago. For accounts missing two payments, the average balances are £39 or 2 percent lower year on year, however, this was the peak month during the early stages of the pandemic, so this is not surprising. Average balances on accounts with three missed payments are £221 higher (8 percent) and four missed payments plus are £228 higher (8 percent).
One way to ensure payments aren’t missed is to set up a direct debit, but the percentage of accounts with a direct debit is 2 percent lower than a year ago.
Cash usage continues to slowly grow
May 2021 also saw the percentage of consumers using cash on their credit cards increase for the second time since September 2020, albeit again marginally. This is being driven by the increased spending opportunities, however, it remains 35 percent lower year on year.
Issuers could look at consumer cash spending patterns. If cash is being used when this was not the case prior to the pandemic, this could be another warning sign of financial stress.
These card performance figures are part of the data shared with subscribers of the FICO® Benchmark Reporting Service. The data sample comes from client reports generated by the FICO® TRIAD® Customer Manager solution in use by some 80 percent of UK card issuers. Issuers wishing to subscribe to this service can contact staceywest@fico.com.
- 01:00 am
- Two leading specialist financial services change management consultancies partner to offer an enhanced service
- Bishopsgate Financial’s expertise in transformation, change management, compliance and financial crime will combine with CubeMatch’s capabilities in strategic change, risk management and technology
Today, Bishopsgate Financial, the financial services change management consultancy, announces it has been acquired by CubeMatch Ltd. This move will create one of the UK’s largest independent financial services change management consultancies, with major global financial institutions as its client base.
CubeMatch and Bishopsgate Financial share the same vision, and are committed to ensuring financial services organisations facing large change programmes can complete them in an effective and timely manner.

Mike Hampson, CEO, Bishopsgate Financial
Both firms offer consultancy, resource augmentation and managed services enabling change programmes to be embedded in their clients’ businesses. Bishopsgate Financial’s core specialisms are in business change, compliance and financial crime which combines powerfully with CubeMatch’s expertise in strategic change, business and digital transformation, risk and compliance, data and technology, quality assurance and managed services.
The existing Bishopsgate Financial management team will remain in place, and assignments with existing clients will continue uninterrupted. The two management teams will come together to enable the wider capability to be made available to the firms’ joint client base.
Andrew Seymour, MD of CubeMatch UK, said “Our focus is helping financial services firms develop the skills, attitude and technology toolsets to cope with tomorrow’s challenges today. The CubeMatch approach is about blending deep domain expertise with a highly rigorous approach to project deployment to ensure our clients are future fit. Bishopsgate Financial has the same ethos as us, along with a significant proven track record in ensuring banks embed robust financial crime and compliance protocols. When this experience is combined with our expertise around strategic change, risk and technology, we offer a highly powerful proposition to our clients.”
Mike Hampson, CEO Bishopsgate Financial adds, “The pace and scale of change in financial services shows no sign of abating. Our clients know the challenges they need to prepare for are complex and they need partners with the combination of sophisticated specialist knowledge held across multiple fields. This transaction will provide an enhanced service offering to our clients as well as enabling us to service them in a wider number of geographies, I am excited to be becoming part of the CubeMatch team.”
- 04:00 am
· Lloyds Bank Commercial Banking will be utilising Mastercard’s Open Banking Merchant Payment Solution to launch PayFrom Bank.
· The solution enables individuals to make online payments directly from their bank accounts, giving consumers more choice over how they pay and providing merchants with instant settlement of funds
· United Response, a charity supporting vulnerable people, is the first merchant to sign up.
Mastercard and Lloyds Bank Commercial Banking have partnered to deliver a new Open Banking payment solution to Lloyds Bank’s business clients.
Lloyds Bank’s PayFrom Bank, enabled by Mastercard’s Open Banking Merchant Payment Solution, lets consumers make payments on an organisation’s website directly from their bank account, without having to enter any payment details.
The solution – which is compatible with most retail bank accounts – gives consumers greater choice over how they pay and enhances their user experience by providing a quick, secure and seamless payment option without the need to remember passwords or input data.
Meanwhile, merchants benefit from a cost-effective payment method that supports their working capital by settling funds immediately.
Mastercard and Lloyds Bank’s partnership will help to move open banking account-to-account (A2A) payments into the mainstream. PayFrom Bank combines Mastercard’s Payment Gateway capabilities and its Open Banking Connect platform – a universal connection to financial institutions’ Open Banking functionality – to deliver a merchant A2A payment solution that covers around 95% of UK bank accounts leveraging Open Banking APIs.
Initial interest in PayFrom Bank is coming from charities for online donations and wallet funding use cases such as investment accounts, although it can be used for any payment scenario. United Response, a charity that provides support to people with learning difficulties, autism, and mental health needs, is the first merchant to go live with the proposition.
Kelly Devine, Divisional President of Mastercard UK and Ireland, said: “Our Open Banking Merchant Payment Solution offers merchants and consumers an alternative to card based payments and even greater choice over how they checkout. Merchants can now provide their customers with a wider range of payment methods without needing to store payer account details. It also removes friction for consumers as all payer details are automatically populated, meaning there’s no risk of entering the wrong account details. We’re excited to be partnering with Lloyds who has a strong pipeline of merchants waiting to sign up to PayFrom Bank.”
Mastercard’s Open Banking Merchant Payment Solution is available as a white-label solution. Financial institutions – such as Lloyds Banking Group – are able to easily integrate with it and instantly access the majority of UK bank accounts through Open Banking Connect.
To find out more visit https://openbanking.mastercard.com/register-interest/
- 08:00 am
Axyon AI partners with DeFi FX exchange DeFinity to develop Deep Learning AI market anomaly detection
Axyon AI, the leading AI solutions provider for asset management and trading, today announces its partnership with DeFinity, a DeFi marketplace for fiat foreign exchange, tokenised currencies and central bank digital currencies (CBDC) to deliver the first ever use of Deep Learning-powered AI to detect market anomalies in the digital asset space.
Axyon’s AI-powered market anomaly detection is a leading-edge technology that generates automated alerts on irregular patterns in asset prices. These may be the result of undisclosed new information, ripple effects from correlated assets, or structural breaks in an asset’s behaviour versus the broader market. Axyon AI’s technology can promptly discover these hidden market data aberrations, which would be otherwise undetectable, and provide an early warning on potential volatility events.
This technology comes at a time when detecting the sign of an upcoming unpredictable event is more important than ever. Detecting market anomalies can help the digital asset space to anticipate and prepare for future events that could impact the industry, just like COVID-19.
Axyon AI is a leading European FinTech company with expertise in Deep Learning/AI for asset management and trading firms. Axyon AI has successful products in several financial use-cases, from security selection and asset allocation to anomaly detection in option pricing.
Daniele Grassi, Chief Executive Officer of Axyon AI, says “Digital assets will inevitably reconfigure the financial sector, and DeFinity is at the forefront of this evolution. We believe that our AI-powered solutions, which are already used by leading players in the traditional asset management sector, will provide DeFinity’s community a valuable help in identifying market anomaly and related risks in the digital assets space. It is a fruitful combination of two terrific technologies, AI and blockchain in the digital asset space.”
DeFinity is a layer-2 protocol and decentralised exchange solution that utilises existing blockchain frameworks, including WeOwn, Ethereum, Binance Smart Chain, Polkadot and Cardano. With a focus on interoperability, the ambition is to create a more inclusive decentralised ecosystem that helps to bridge traditional assets with digital assets.
Manu Choudhary, Chief Executive Officer of DeFinity, says: "Artificial Intelligence is the apex technology of the information age and we are incredibly fortunate to have partnered with Axyon AI, a true innovator in the field.”








