
Published
- 07:00 am
Tata Consultancy Services’ Marketplace of Partner Solutions is a Destination for Financial Institutions to Curate Contextual Customer Experiences and Build New Revenue Streams
Tata Consultancy Services (TCS), a leading global IT services, consulting and business solutions organization, announced the launch of the enhanced TCS BaNCS™ Marketplace, an innovation hub for customers to collaborate and adopt cutting-edge partner solutions compatible with the TCS BaNCS suite, spanning banking, capital markets, and insurance domains.
Financial institutions are increasingly partnering with TCS to accelerate their innovation and to leverage a larger co-innovation ecosystem curated by TCS. The TCS BaNCS Marketplace offers them a rich ecosystem of solutions and APIs from fintechs, insurtechs, risktechs, regtechs and other innovators.
Customers can collaborate and experiment with these partners in a secure and trusted sandbox environment, to co-innovate and rapidly prototype solutions that enhance end-customer experience, and enable new value-added services and revenue streams. They can also select pre-packaged and curated solutions to accelerate their responses to evolving market needs.
For partners the Marketplace offers access to TCS BaNCS’ large installed base across the world and an opportunity to expand into newer markets. More than 100 partners are already part of the TCS BaNCS Marketplace. Of these, 50% are in different stages of monetization and 25% of the partner solutions have already been deployed at customer organizations.
To be hosted on the Marketplace, partners go through a process of curation to determine their strategic relevance to customers and complementarity with the TCS BaNCS product roadmap.
R Vivekanand, Co-Head, TCS Financial Solutions, said, “TCS BaNCS Marketplace gives our customers a place to collaborate and innovate with our curated set of partners in a secure, trusted environment, and deliver fresh experiences to their customers. The solutions on the Marketplace have evolved with the product direction of TCS BaNCS and the market, and its API-first approach not only facilitates easy and secure integration with multiple ecosystems, but also creates new business models and possibilities for our customers.”
- 05:00 am
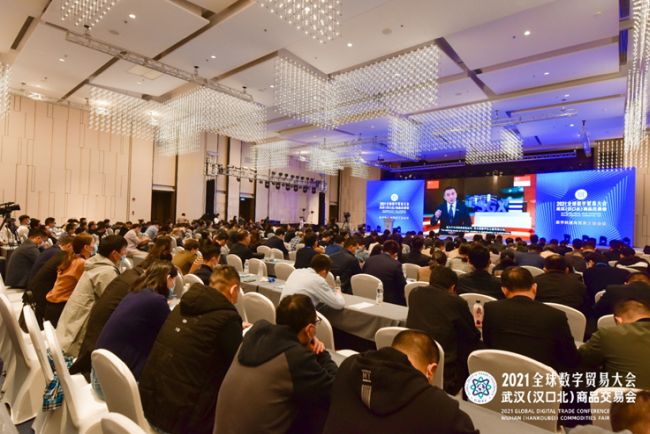
The 2021 Global Digital Trade Conference and Wuhan (Hankoubei) Commodities Fair presented "Digital Trade and Technology", a thematic keynote event, on October 13 in Wuhan, Hubei Provence, China. More than 300 distinguished guests, including experts and scholars in the digital economy, shared new insights on digital trade under China's new "dual circulation" development strategy, and on the future of the global digital economy.
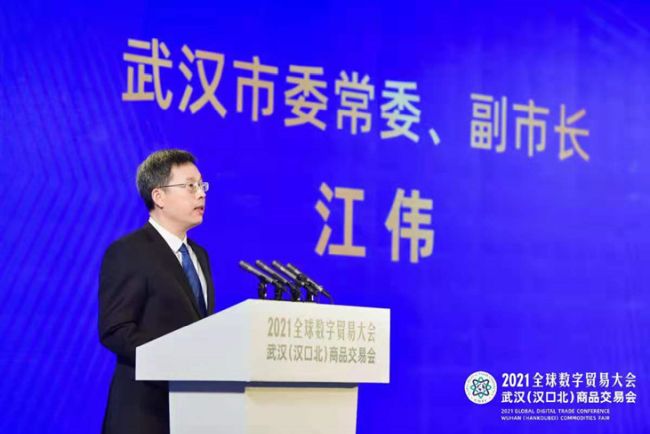 |
| Jiang Wei, Standing Committee-member Wuhan Municipal Party Committee and Vice-Mayor of Wuhan encouraging conference attendees to take advantage of digital trade development opportunities in Wuhan for new businesses and tech innovations. |
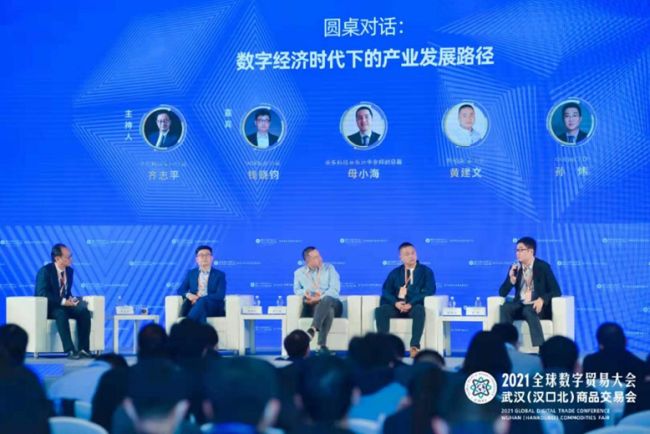 |
| Organizer/host Qi Zhiping, CEO, ZALL Smart Commerce Group, joins entrepreneurs Qian Xiaojun, CEO, Beijing United Information Technology; Mu Xiaohai, Vice President, JD Cloud Business Group; Sun Wei, CEO, Shenzhen Sinoagri; and Huang Jianwen, Chairman, pao400, for panel "Industrial Development in the Digital Economy Era". [All images: ZALL Smartcom] |
This new technological revolution and industrial transformation brought about digital trade, significantly impacting the trading sector, fostering new business models and trading patterns. This has reshaped the global industrial chain, supply chain, value chain and innovation chain, becoming a major driving force for economic globalization.
As one of the key highlights of the Global Digital Trade Conference, the "Digital Trade and Technology" event aims to become the leading platform that facilitates discussions, exchanges, and conversations around global digital trade.
Jiang Wei, Standing Committee member of the Wuhan Municipal Party Committee and Vice Mayor of Wuhan, delivered a speech that addressed Wuhan's geographic location and transportation advantages, vibrant commercial hub, and quality modern logistics infrastructure laying the foundation to advance the development of Wuhan's digital trade and economy. Wuhan has introduced a series of policies to promote development of the digital economy with much success. Jiang Wei welcomed all attendees to take advantage of the digital trade development opportunities and invest in Wuhan for their new businesses and technological innovations.
Internationally renowned speakers including Dr Finn E. Kydland, Norwegian economist and winner of the 2004 Nobel Prize in Economics; Yoshinori Ogawa, Executive Director, Marubeni Corporation and Managing Director, Marubeni China; Wu Ying, Chairman of the Digital China Federation; Liang Rubo, CEO of Bytedance; Jiang Guofei, Vice President of Ant Group; Loh Boon Chye, Vice Chairman, World Federation of Exchanges (WFE) and CEO, Singapore Exchange (SGX); Tian Ning, Chairman of the Board of the Panshi Group delivered keynote addresses, sharing new insights into the development trends of the global digital economy, the integration of digital trade and technology, and industrial supply chain innovation and transformation.
Host organizer Qi Zhiping, CEO of ZALL Smart Commerce Group, joined entrepreneurs Qian Xiaojun, CEO of Beijing United Information Technology; Mu Xiaohai, Vice President of JD Cloud Business Group; Sun Wei, CEO of Shenzhen Sinoagri; and Huang Jianwen, Chairman of pao400, for an in-depth panel discussion around the development and transformation of traditional industries in the digital economy era.
iResearch Consulting, China's leading data research organization, presented a new white paper on Global Digital Trade during the event. Li Chao, a Chief Analyst at iResearch and Executive Dean of iResearch Institute, presented their findings. The white paper shares the current development of digital trade from the existing digital infrastructure, policies, technologies, and capital. It also analyzes in-depth how digital trade has redefined traditional trade across production, transaction and supply chain.
The whitepaper looks at five major industries: agriculture, steel, plastics, wholesale and cross-border trade, along with the business models of renowned Chinese and global digital trading companies. It analyzes the profound changes digital technologies and supply chain services bring to the global trade industry, highlighting the growth momentum of digital trading companies and their financial market prospects. The paper suggests that with continued industry upgrading and business segmentation, there will be opportunities for digital trade services and ecosystem-based platforms to create new industrial supply-demand relationships and ecological synergies.
Themed "Intelligent Connectivity . Global Trading", the 2021 Global Digital Trade Conference is organised by the Hubei Provincial People's Government; supported by the All-China Federation of Industry and Commerce; co-organised by the Wuhan Municipal People's Government and the Department of Commerce of Hubei Province; and executed by the Wuhan Huangpi District Government, Wuhan Municipal Bureau of Commerce, Hankoubei Group and ZALL Smart Commerce Group.
The Wuhan (Hankoubei) Commodities Fair is organized concurrently and features hundreds of procurement hubs and thousands of live streaming activities, pushing global industrial and supply chains towards digitalization and intelligent connectivity while promoting high-quality economic development and global trade. Running through October 26, 2021, the event has attracted representatives from 100+ countries, as well as over 10,000 merchants, experts and scholars. (en.hubei.gov.cn)
Read more here https://financialit.net/news/it-innovations/hybrid-conferences-are-they-now-default
- 05:00 am
- Custody provided by Fidelity Digital Assets
- Authorised by the Guernsey Financial Services Commission (GFSC)
- Administrators: Sigma Asset Management (Guernsey) Limited
- Fund Architecture/Consultancy: Midshore Consulting Limited
Jacobi Asset Management has received approval to launch the world's first tier-one Bitcoin ETF. The Jacobi Bitcoin ETF is a centrally cleared crypto-backed financial instrument, authorised by the Guernsey Financial Services Commission (GFSC) and with custody provided by Fidelity Digital AssetsSM. It is Jacobi's intention to list the Jacobi Bitcoin ETF on Cboe Europe, one of the largest pan-European equity exchanges, subject to Financial Conduct Authority (FCA) listing approval.
Launched in May 2021 to shape the future of digital asset management, Jacobi brings together decades of expertise from Banking, Regulation, and Fintech to shape the future of digital asset management by designing, issuing and managing institutional crypto products and funds connected to digital assets.
Jacobi is spearheaded by CEO Jamie Khurshid, a former Goldman Sachs investment banker and pioneer of regulatory transparency in financial markets. Jamie was named by Financial News as one of the top 40 under 40 in European trading and technology and ranked in the 'Exchange invest' Top 1000 most influential people in global financial markets. He has appointed a team with extensive financial services, regulatory and crypto asset expertise.
CEO Jamie Khurshid said: "We are excited to be launching a new secure, transparent and accessible product to track the performance of Bitcoin. We are de-risking investments in crypto by removing the technology risk associated with the physical asset and the counterparty risk associated with traditional funds or tracker products that are unregulated leveraged debt instruments. We are proud to collaborate with Europe's leading regulated firms for a truly tier 1 offering to service market demand, subject to the necessary regulated approval. This is an exciting moment for Europe as regulatory approval comes ahead of those waiting for a decision from the U.S. Securities and Exchange Commission."
"The Jacobi Bitcoin ETF will finally bring digital assets wholly into the mainstream investment infrastructure with the support of the leading firms we are working with. It will provide investors with the opportunity to participate directly in physically-settled Bitcoin. This new ETF provides simple, secure, accessible investing into one of the world's most exciting asset classes via some of the world's leading regulated entities," commented Roy McGregor, Chairman of Jacobi Asset Management and former CEO of Credit Suisse Channel Islands.
Jacobi Bitcoin ETF investors will benefit from the security of Fidelity Digital Assets' enterprise-grade custody and execution services, designed to enable institutional investors to safely secure, trade and support investments in digital assets. Chris Tyrer, Head of Fidelity Digital AssetsSM in Europe, commented: "Greater diversity of investor interest has created significant demand for additional vehicles for exposure to help provide broader access to digital asset markets. While safekeeping of assets is a top priority for investors and asset managers in all asset classes, the highly technical nature of digital assets places even more emphasis on this and underscores the need for institutional-grade custody solutions like ours."
The Jacobi Bitcoin ETF was developed to meet regulatory standards by Christopher Jehan, Head of Fund Architecture and former Chair of the Guernsey Investment & Funds Association (GIFA). Christopher led the team at Midshore Consulting in designing the Fund with legal work performed by Collas Crill led by Partner Wayne Atkinson and Senior Associate Gareth Morgan.
Prior to FCA listing approval, Jacobi Bitcoin ETF investments will be facilitated through Sigma Asset Management (Guernsey) Limited ("Sigma"), the fund manager providing management and administration. Fund consultancy support will continue through Midshore Consulting.
For further information visit Jacobiam.com
- 01:00 am
Few deals drive FinTech volumes, record number of mid-market M&A transactions, but European capital markets remain elusive for FinTech
Today Finch Capital issued the 6th edition of its annual State of European FinTech Report for 2021. The report covers a range of topics including capital market and M&A implications for FinTech valuations and exits, events that might stall the FinTech “blast”, the broader European FinTech landscape and the themes the Finch Capital team expect to shine through in the next year.
"Fintech continued to dominate European tech, but compared to last year we see a shift towards B2B, more concentration of large funding rounds with 5% of deals getting 65% of funding, a growing war for talent, and exits predominantly in the €50-500m range with limited large ticket listings. The last trend is especially concerning for the highly valued loss-making unicorns' ' says Radboud Vlaar, Managing Partner at Finch Capital.
Key findings:
FinTech Funding dominates European Tech: The lull pandemic phase seems to have disappeared in the past 12 months, as financing amounts have more than doubled in Europe from c.€5 billion in H2 2020 to over €15 billion in H1 2021. B2B funding has clearly dominated with 65% of the capital, seeing the appetite in B2C FinTech businesses slip from 50% to 35% in the past two years
More capital went to fewer companies in Europe than any other region: Despite record financing, it is becoming increasingly clear that a few deals are driving the growth in overall funding. Europe is the least diversified, with 5% of the deals seeing over 65% of the funding amounts. As FinTech now accounts for over 25% of the value of overall VC funding, a few large unicorns are driving this trend (eg: Klarna, Rapyd) rather than the broader ecosystem benefiting from more capital
War for talent as aggressive hiring continues across most sub-sectors: Companies are not backing down. The shift in workplace dynamics has enabled all companies to become even more aggressive with their pace of hiring. Brokerage businesses understandably saw the most growth, but as new member growth slows and wage inflation creeps into the system, there could be signs of margin pressure
Record M&A transactions in the €50-500m range, while IPO and SPAC markets in Europe remain elusive: Europe should see a record 2x growth in the number of financial services M&A under €500m by the end of this year compared to 5 years ago, higher than the US or Asia in terms of growth. However, the IPO market remains elusive, with 60% fewer IPOs expected this year than in 2015.
There are early signs that the FinTech blast could stall in 2022: We see 4 factors: (1) War on Talent, putting financial plans at risk as growth falls behind due to longer time to find talent and cost rise due to increase in salaries; (2) Public & IPO markets starting to slow down putting pressure on the primary exit path for European Unicorns; (3) Increased regulatory scrutiny resulting in higher costs and slower expansion; (4) Finally, rising interest rates can have a dramatic impact on the valuation of high growth loss making companies
Big trends that will shape 2022: Examples of our predictions are margin pressure in payments driving M&A and value add growth; Credit cards to be replaced by BNPL; The rise of embedded insurance; New infrastructure being delivered for financial services via APIs; and a shift back to basic AI.
Vlaar continues: “We expect the market environment for FinTech in 2022 to be a bit circumspect, with early signs of structural events that could stall the amazing ride of the last 8-10 years. Rising interest rates put pressure on the valuation of loss-making high growth companies, war for talent puts pressure on economics and ability to grow. To allow the unicorns to deliver against their growth expectations we expect significant M&A activity in 2022 of € 50-500m companies using their cash war chest and valuable stock.”
The report summarises and compiles industry data from hundreds of sources including Dealroom, CBInsights, McKinsey, Morningstar and equity research as well as interviews and views from experts in the industry. It also includes the Finch team’s own views, proprietary insights and data based on a decade of investment experience in European FinTech.
- 05:00 am
EMURGO has invested a 7x figure undisclosed amount as a seed investment to Adanian Labs through its newly launched EMURGO Africa investment entity |
|
EMURGO is the official commercial arm of Cardano blockchain; This investment is part of EMURGO Africa, a subsidiary of EMURGO’s new $100 million Cardano ecosystem investment vehicle; The undisclosed funding will support Adanian Labs (www.AdanianLabs.io) with its mission to build 300 tech startups across Africa. Adanian Labs, a pan African venture studio today announced its partnership with EMURGO (https://emurgo.io), the official investment arm of Cardano (https://cardano.org) blockchain to scale tech startups in Africa and grow the Cardano ecosystem. EMURGO has invested a 7x figure undisclosed amount as a seed investment to Adanian Labs through its newly launched (https://bit.ly/3aGt9Lu) EMURGO Africa investment entity. This investment is focused on achieving one of the goals of Cardano which is to bring financial and educational empowerment via its blockchain platform to the billions who lack these opportunities. Founded in 2020, Adanian Labs is focused on building a platform where African Tech start-ups can thrive and access all key resources that allow them to grow sustainably. The lab provides all the critical support start-ups would need to launch and scale in the continent including, access to funding, technology development, technical support, go to market strategies and partnerships. John Kamara, Adanian Labs CEO said “We are extremely encouraged by the partnership with EMURGO Africa as their vision to build a thriving technology ecosystem in Africa is well aligned with ours. We aim to build 300 tech powered, impact driven start-ups by 2025. We are passionate in our drive to create “CAMELS” strong, resilient companies, entrepreneurs and youth who will sustain African economies, even with limited resources. We coined #TheCamelTheory knowing the challenges in terms of equity that Africa has in its spin towards the fourth industrial revolution (4IR).” As a venture studio, Adanian Labs uses its unique positioning to create and spearhead the sharing economy for African start-ups, by building a socio-economic ecosystem revolving around the sharing of resources, creation, production, distribution, trade and consumption. “As the start-up that builds start-ups we apply lean start-up principles in processes, learning, iteration, scaling and innovating solutions. Our aim is to build solutions across SDG’s impact goals that will power Africa economies while creating massive impact to the youth.” Further stated Kamara. “This partnership with EMURGO Africa will allow us to forge more efficient collaborations that will enable us to build quicker, scale faster and optimize capitalization, creating a win win benefit to all our partners in the sharing nature of our growing ecosystem.” concluded Kamara. Ken Kodama, EMURGO CEO said: “We are more focused than ever on accelerating the development of Cardano’s ecosystem with a rich mix of decentralized services catering towards a global community that is increasing in overall blockchain awareness including in Africa. EMURGO Africa is especially dedicated to delivering financial and educational empowerment opportunities on the continent by providing the capital and strategic partnerships necessary for local startups to scale rapidly and bring new solutions to Cardano. Our partnership with Adanian Labs provides us with a great framework to launch in Africa.” The Adanian Labs – EMURGO Africa partnership signifies a new dawn for the African technology evolution that aims to foster private sector growth and see a burgeoning middle class emerge. Tech startups interested in joining the Adanian Labs can apply through the Adanian Labs website – www.AdanianLabs.io and join its various communities across digital social platforms. Distributed by APO Group on behalf of Adanian Labs. |
- 02:00 am
Steffen Vollert, Co-Founder & CTO at Volt,
“With at least 135m contactless cards in circulation and the technology accounting for 9.6bn payments a year, there’s no doubt that the new contactless limit brings new opportunities for many. Consumers will benefit from greater flexibility and convenience; merchants could see an increase in sales and operational efficiencies; payment service providers might experience an uptick in transaction volumes.
“However, concerns that the increased limit will make it easier for fraudsters to steal larger sums of money from cardholders are valid, and should not be disregarded. During the first six months of this year alone, contactless fraud – covering cards and mobile phones – totalled £7.6m, according to UK Finance.
“Certainly, steps are being taken in right direction to combat card fraud. After 14 March 2022, issuers in the UK will have a legal obligation to implement SCA on card transactions under the FCA’s PSD2 requirements, for example. But this doesn’t solve the issue of contactless transactions, or card fraud itself. As a result, the increased limit could accelerate growing demand for an equally fast, but more secure payment method, which can be realised via open banking. Direct account-to-account payments in real-time eliminate card fraud altogether, whilst providing a single-click checkout experience for the consumer and substantially reduced fees for the merchant. It will take time for open banking payments to become mainstream. But could the increased contactless limit be the catalyst for a transition away from card payments? Only time will tell.”
- 01:00 am
Susannah Streeter, senior investment and markets analyst, Hargreaves Lansdown
‘’Regulators have been tip-toeing round the crypto world, shouting out occasional warnings to the crowds of speculators, but we now have the firmest indication yet that they will soon be stepping in to break up the block party.
The Deputy Governor of the Bank of England Sir Jon Cunliffe clearly believes the speculation has reached such a level that a crypto time-bomb is now ticking, which could blow up in the face of the financial sector.
With unregulated crypto assets growing 200% this year alone from just under $800 billion to $2.3 trillion, and banks and hedge funds now becoming involved, the Bank of England is worried about contagion if the value of coins and tokens held deflates rapidly.
The warning from the Bank of England comes hot on the heels of a call to action from the chair of the Financial Conduct Authority, Charles Randell in September. The FCA is extremely worried about the collision between social media and the crypto world, with Kim Kardashian’s single post about a token earlier this year considered to be the biggest financial promotion in history. Now, this nervousness about how financially vulnerable younger investors are being targeted by influencers has widened to an anxiety that the crypto wild west could undermine the stability of the financial system. There has been a hesitancy until now to bring crypto currencies into the regulatory sphere because of the risk it will add more legitimacy to the currencies.
It’s clear central banks and regulators see part of the solution lies in pushing this intense interest away from thousands of coins and tokens in the crypto space, towards stable coins, pegged to fiat currencies like the dollar, but they currently only make up around 5% of crypto assets held. The Bank of International Settlements, a global forum for central banks has already set out how clearing and payments services should be applied to stable coins.
There appears to be increasing backing of recommendations made by the influential Basel Committee on Banking Supervision. If banks and other regulated financial institutions dabble in crypto, the committee is considering making them put aside enough capital to cover 100% of potential losses. Giving speculative tokens a high-risk price tag is likely to make crypto currency dealing and investment very expensive and could limit the number of new institutional entrants into the crypto world.
Regulators and central banks are walking a tricky tightrope, recognising the need to foster new decentralised payments technology but ensuring enough rules are in place to prevent runaway speculation infecting the wider financial sector. If the environment is made too cumbersome there is a risk that innovation in the fast moving world of decentralised finance could be quashed, slowing down the efficiency of operations and leaving the UK behind countries which are welcoming crypto with open arms.’’
- 08:00 am
Historically, IT and tech infrastructure at banks has never been focused on the customer. The design underpinning these labyrinthine networks was centred on the delivery of distinct outputs and functions relating to different financial products. These individual products, whether they be credit cards, current accounts, mortgages or indeed any product relating to family life and responsible adulthood as we know it, were designed to be managed in siloes.
These product-based siloes were helpful during a time when banks were just beginning to refine and expand their offerings and analyse the effectiveness and profitability of, say, home insurance versus this once ‘new-fangled’ thing called an ISA.
By contrast, data on the individual customer was (and largely still is) not easily identifiable, as customers ‘live’ in various parts of incumbent banking systems, according to how many accounts or products they hold with the bank. These disparate parts cannot ‘talk to’ eachother easily, if at all.
In addition to the focus on more easily quantifiable products and business units, there was a distinct lack of concern among early banking architects, with the ‘financial life’ of the customer. The ‘personas’ discussed in fancy branding workshops today were unheard of or at best, such activities were regarded as too costly and frankly unnecessary; during a time when banks’ customers had less choice.
As far as the consumer (I’m including corporate banking clients in this description) is concerned, there is a broad frustration with how banks interact with them, borne out of a misunderstanding of how banks organise – or not – customer profiles. Such frustration has contributed to the increasing popularity of neo banks such as Revolut, who hit the 10 million customer mark in February 2020. For traditional banks to keep pace with such aggressive, venture capitalist-backed growth in this sub-sector, they must achieve customer-centricity.
Banks are already mostly convinced about the importance of being or at least coming across as, more user-friendly. The real change won’t happen because of pretty wireframes and good user interface, however, but as a result of the explorations that are happening right now in order to achieve more customer-centricity within banking. This exploration is a team effort, a meeting of the minds and skills of dev teams within banks themselves, some external consultants, those with working knowledge of the original mainframe systems and beyond, to first of all analyse the incredibly complex architecture that is rendering the customer almost invisible within the ‘haystack’ of systems.
Incumbents are museums of technology
A ‘mega bank’ could have a master framework of between 30-70 core banking systems plus hundreds more sub-systems that pertain to each. While some banks have started to build customer-centric layers into this master framework, so that individual customer transactions are allowed to ‘live’ for longer, this isn’t always the solution. While this approach has improved the customer experience, the architecture became even more complex and costly and remains siloed by product.
For most banks, a single view of the customer still does not exist. Rather, customers live as fragments, scattered across their siloed systems. Again, the will to change this for better does exist, but is being hampered by outdated systems that are difficult or impossible to modify.
The journey to personalisation
The rising threat from neo banks and fintechs – many of which were built with the customer in mind from their inception, has intensified during the pandemic, which saw banks closing branches with increased veracity and accelerating their existing digital transformation processes.
We must bear in mind that these legacy systems were created with a 9-5 mindset, during a time when shops were closed early and certainly on a Sunday. The consumer of today expects much more convenience than this and any relatively new bank today will of course be built with a 24/7 mindset, for the mobile-first user.
The raw materials, such as the troves of personal data they’ve collected over time, and the will to become more customer-focused, are present among banks. So, what are the tangible steps they must take in order to cut through the current, product-focused set-up and to move the explorations to a productive conclusion?
What do banks need to do?
- Partnering with third parties: To solve the problem of bank architecture being product-centric, more conversations need to take place between the banks themselves, developers (from both the neo and legacy eras), mathematicians, quants and the like. These partnerships will only be as impactful as the levels of trust between the banks and these groups. One breakthrough in this vein would be for tacit knowledge from legacy tech providers to be shared with banks and fintechs alike. An example of how this type of relationship works is the venture between Lloyd’s Banking Group and Thought Machine. The two are working to transfer data on 500,000 customers to a new core system and exploring the possibility of transferring all of the group’s customer data over the next few years.
- Building new platforms: For many incumbents, one solution has been to create new, smaller platforms that operate on cloud-based systems designed to serve a specific strategic need. These platforms often operate separately from the larger institution, using their own infrastructure and deploying new technology solutions as needed. This keeps investment under control and quarantines risk to some extent.
- The total shift to cloud: Cloud technology should be considered for upgrading bank systems as a whole, as it has the potential to transform an institution’s operational efficiency and negates the need for further investment in hardware.
Final thoughts
As banks are currently so siloed, they need to spend more time in understanding their legacy infrastructure, which can be done by hiring in-house to plug knowledge gaps, rather than rely on the protected knowledge of external consultants and transient project managers.
The goal of unification of systems as well as customer and product is more achievable than ever before, thanks to the tech and innovators at our disposal. Untangling systems to provide a better service for customers and improve personalisation is a process still in its infancy, but with a thorough approach to this current discovery phase, that haystack will certainly become a lot easier to navigate.
- 04:00 am
Russian Railways self-service terminals use advanced Smart Engines technologies to sell tickets for long-distance trains. The integration of the Smart ID Engine software product for passport scanning into terminals simplifies the routine procedure of manually entering passenger personal data and speeds up the ticket sales process. The project of creating a network of terminals currently has more than 300 units operating on the railways of Russia and Kazakhstan. The project integrator is JSC Transinfoset.
An AI-based software for data capture of a passenger's passport was integrated into a new generation of self-service transaction terminals (SSTT). The first samples of terminals were installed at the Leningradsky railway station in Moscow, Russia. Russian Railways plans to expand its SSTT fleet, primarily by equipping the most visited railway stations in Russia with intelligent terminals. Smart Engines is developing energy-efficient algorithms for scanning identity documents integrated into the SSTT. The high-speed Smart ID Engine detects the passenger's passport and automatically enters the data into the required form fields to issue a ticket. Thus, the passenger no longer needs to enter the passport details on his own, making the ticket buying process six times faster by reducing the time spent on the manual data entry.
With secure and fast scanning of international passports of more than 210 countries and Russia, citizens of the Russian Federation and travelers from other countries can quickly purchase a ticket. Smart ID Engine ensures the security of document processing, simplifying entering passport data and reducing the likelihood of errors during manual filling. Flagship Smart Engines technologies are GDPR and CCPA compliant. Passenger data is extracted and analyzed in local RAM, and passenger data is not saved or transferred to third-party services.
"The accelerated deployment of contactless services and equipment for process optimization over the past years indicates its significance. Manual entry of passport data when issuing a ticket is a routine procedure. That's why the process of purchasing tickets should be as convenient as possible for Russian Railways passengers. According to our estimates, implementing the Smart ID Engine software product will increase the usability and economic return of self-service terminals", comments Alexander Galaktionov, General Director of JSC Transinfoset.
"Smart Engines is pleased to become a part of the innovative projects of Transinfoset and aims to further cooperation. The creation of new generation self-service terminals with scanning Russian and foreign passports data will mark a new stage in the ticket sales at railway stations after the automation of ticket offices using smart scanners", says Vladimir Arlazarov, CEO of Smart Engines, Ph.D.
- 08:00 am
- Three-quarters rely on traditional VPNs for remote access while a third also use zero trust as part of their remote access strategy
- Over half plan to reduce third party/contractor access to systems due to security risks
A report launched today by Menlo Security, a leader in cloud security, highlights growing concerns about securing users as the trend for hybrid and remote working is set to remain. The new report – which surveyed 500+ IT decision makers in the U.S. and the U.K., including a third at C-level – looks at attitudes to securing remote access to applications and resources and the adoption of zero trust solutions.
While most respondents (83%) say they are confident in their strategy for controlling access to applications for remote users, three-quarters are re-evaluating theirs in the wake of new ways of working and the growth in cloud application use. While half of employees are currently working remotely or adopting a hybrid approach, around two-fifths (42%) are expected to continue in 12 months’ time.
According to the findings, three-quarters (75%) of organisations continue to rely on VPNs (virtual private network) for controlling remote access to applications, which rises to 81% for organisations of 10,000+ employees. For around a third (36%) of organisations a zero trust approach also forms part of their remote access strategy.
“It seems that most businesses are confident in their remote access security, yet are still relying on a traditional and inherently insecure way of doing things using VPNs, which give access to everything on a network,” said Mark Guntrip, senior director, cybersecurity strategy at Menlo Security. “With only a third currently using zero trust network access, there’s a real opportunity to provide users with access to only those applications and resources needed to do their job. When you start to adopt this approach across everything you do then your whole security mindset changes.”
The top reason for implementing a zero trust solution is improved security, according to 60% of respondents, regardless of whether they are using it or not. One third (32%) point to ease of use, while speed of access and scalability are both more widely recognised among those already adopting a zero trust approach. Significantly, 40% of respondents believe that implementing a zero trust solution places less pressure on IT.
Despite overall confidence by global IT decision makers in the robustness of their strategy for controlling application access for remote users, Menlo Security’s research also shows that:
· Three-quarters of respondents believe that hybrid and remote workers accessing applications on unmanaged devices poses a significant threat to their organisation’s security. Despite this, around a fifth still allow unmanaged devices – laptops, desktops and mobile devices – to connect to corporate applications and resources.
· While the majority (79%) of respondents have a security strategy in place for remote access by third parties and contractors, there are growing concerns about the risks they present, with just over half (53%) planning to reduce or limit third party/contractor access to systems and resources over the next 12–18 months.
Menlo’s Mark Guntrip adds: “As the internet becomes the new corporate network, controlling user access to private applications has become more important than ever. Organisations need to evolve their thinking from providing connectivity to the entire network to segmenting access by each individual application. The right zero trust approach will ensure seamless access between users and the applications they are authorised to use, while all other applications are invisible, preventing lateral discovery across the network.”
Menlo Private Access
Menlo Security has a clientless-first approach to implementing Zero Trust Network Access, enabling organisations to secure access to applications from all devices – including managed, unmanaged and mobile devices. This approach minimises the workload on IT and security for deployment, while maximising the security posture of the company. The clientless-first approach can be augmented with a client for use cases that specifically require client-based access.
Unlike many ZTNA solutions that cannot monitor traffic being sent and received between an end user and a controlled application, Menlo Private Access ensures that security policy is always enforced by remaining inline between the end user and protected applications; utilising our Elastic Isolation Core as a control point to prevent sensitive data loss and stop potential malware from reaching the endpoint.








