Published
- 01:00 am

Landsbankinn, the largest Icelandic bank, has joined forces with Salt Edge, a pioneer in open banking, to comply with Icelandic law on the PSD2 legislation.
The new Act on Payment Services, which transposes the European PSD2 into Icelandic law, entered into force on November 1, 2021, and will take full effect on May 1, 2022. Once the regulation accompanying the Act is fully implemented, banks and fintechs will get authorised access to customer and business bank accounts to initiate payments and provide banking data-related services. Leveraging Salt Edge’s PSD2 Compliance Solution, Landsbankinn will offer its customers the possibility to view their bank accounts in apps and websites external to the bank and use these services to make transfers from their accounts.
Landsbankinn is enthusiastic about technological development that helps us simplify life for our customers. With that in mind, we have chosen to work with Salt Edge, a reliable and experienced partner, to comply with the Act on Payment Services. The Act enhances competition and consumer protection in financial markets and supports innovation in the payment market. Our collaboration with Salt Edge gives us access to international expertise that in turn enables us to enhance our robust and agile customer service. We aim to harness technology to make finances smarter and more approachable, as always placing customer satisfaction first.
Arinbjörn Ólafsson, Managing Director of IT at Landsbankinn
Following the provisions of the Act, Landsbankinn has opened a sandbox, or development environment, hosted and operated by Salt Edge, allowing fintechs and other companies in the sector to explore the functionality of various bank systems and to develop innovative fintech solutions. The sandbox allows developers to retrieve account information and transaction statements, test domestic and cross-border transfers, and more.
As a pioneer in open banking, Salt Edge is thrilled to assist Landsbankinn on its way to becoming one of the open banking trailblazers in Iceland. Becoming compliant means much more than just fulfilling legal requirements, it is an amazing opportunity for the whole region to offer the ultimate banking experience and boost local financial wellbeing. Landsbankinn, an ever-smarter bank, will continue to change and develop in harmony with the community it serves, and Salt Edge is honoured to be a part of such an important milestone.
Andrei Scutari, Country Manager at Salt Edge
- 09:00 am

As online business grows exponentially, finally fulfilling the internet’s promise of a ‘global village’ in which anyone can buy and sell anything from anywhere, CellPoint Digital is providing merchants with the ability to increase conversions, reduce operational costs, and boost profits.
Typically, merchants retain long-term partnerships with a single acquirer that processes credit or debit payments on their behalf. However, leading merchants and payment services providers are increasingly finding that working with multiple acquirers can deliver compelling commercial benefits.
As a payment orchestration platform provider, CellPoint Digital connects merchants through a single API to the acquirers they want, that will support them on their growth journey. This ensures they can offer customers anywhere in the world the seamless payments experience that is so desired.
While many merchants still opt for traditional payment services, others are learning that this one-size-fits-all approach is becoming incompatible with a more complex and international eCommerce landscape.
Here Mark Patrick, Head of Global Payments at CellPoint Digital explores the concept of multi-acquirer strategies and touches upon the benefits to customers of CellPoint Digital’s solutions.
What is a multi-acquirer strategy?
A multi-acquirer strategy is one in which a merchant holds accounts with more than one acquirer which processes credit or debit card payments. Though introducing multiple players might at first appear to be a needless complication of a merchant’s payment ecosystem, the advantages of a multi-acquirer strategy are significant.
Factors such as the sector they operate in, their size, and the regions they cover all contribute to a merchant’s decision to diversify the number of acquirers they work with, but others are more universal.
Increased conversion rates – Increasing the completed number of sales is essential for achieving growth objectives, yet is impeded by the likes of declined transactions, abandoned carts and unsatisfactory customer experiences.
With increased payments acceptance - facilitated by more intelligent routing - coupled with an ability to accept a wider range of payment methods, merchants are able to provide their customers with a greater mix of both domestic and international payment options.
Omnichannel support – Today’s merchants need to be able to take various forms of payments to maximise sales. As a result, omnichannel support and the flexibility it affords is a key benefit of deploying a multi-acquirer strategy.
With the migration towards digital channels gathering pace every day and the growth in alternative payments reaching record highs, consumer expectations are more sophisticated than they have ever been. They demand secure and seamless payment experiences across a range of channels and the ability to use their preferred payment methods.
Accommodating these diverse and changing consumer preferences while preserving growth requires merchants to modify their payment strategies through multiple acquirer relationships.
International growth – The transaction speeds and success rates of payment gateways can vary considerably depending on payment methods used and consumer location.
Smart routing offers a solution through the use of advanced data analytics and technologies such as artificial intelligence (AI) and machine learning (ML). By analysing large datasets according to payment method and location, it can be determined which payment gateways will generate optimum returns per transaction. It means merchants can more effectively process payments, enhance revenues, and save on cross border transaction fees.
Merchants across the globe are now implementing these dynamic routing techniques on a much broader scale and boosting their transaction success rates both domestically and across borders.
Compliance support – With a greater online presence, more and more merchants are offering their services globally. However, meeting regulatory mandates as part of a global operation is complex.
With a Payment Orchestration Platform forming the bedrock of a multi-acquirer strategy, merchants access bespoke middleware designed to not only manage multiple PSPs but also achieve jurisdiction-based compliance.
The Platform provides the merchant with PCI compliance using flexible tokenisation of personal data and streamlines KYC and PSD2 management, helping the merchant ensure compliance while reducing compliance costs.
Less is not always more
The deeper we get into the digital age, the more it’s communicated to us that benefits are had by having less. Accessing operations through just one interface. Managing accounts through just one app. Completing digital transformation through just one provider.
For the most part, this is true. But it is not true when it comes to working with acquirers. By developing a multi-acquirer strategy, merchants can plug into different acquirers across the globe, helping them to expand cross border and avoid the need to navigate relationships with individual acquirers. And, with intelligent routing, each payment is processed in a way that works best for both merchants and customers alike.
To find out more about how a Payment Orchestration Provider can plug you into multiple acquirers and ultimately boost sales, head to www.cellpointdigital.com
- 05:00 am
- Vauban is building the infrastructure and network powering the global alternative investment industry.
- The platform provides venture capital fund managers and angel investors with everything they need to raise and invest capital quickly and simply.
- Users can set-up, deploy and manage Funds and SPVs online, from multiple global investment jurisdictions, at a fraction of the usual time and cost.
- The company’s investors include co-leads Pentech and Outward VC, with 7percent Ventures, PiLabs, MJ Hudson, and a roster of notable angel investors are also participating.
- Vauban is currently onboarding at least one new client every day. Over $1bn has been invested via the platform since launch, with users including Anthemis, Passion Capital, and Octopus Ventures.
- This follows unprecedented levels of activity in European VC, with €41.8bn raised by European companies in the first half of 2021. Vauban presents a huge opportunity for investors to easily deploy capital in the European market.
- As a result of the funding, Vauban will deepen its tech and regulatory infrastructure, double its headcount and launch a new office.
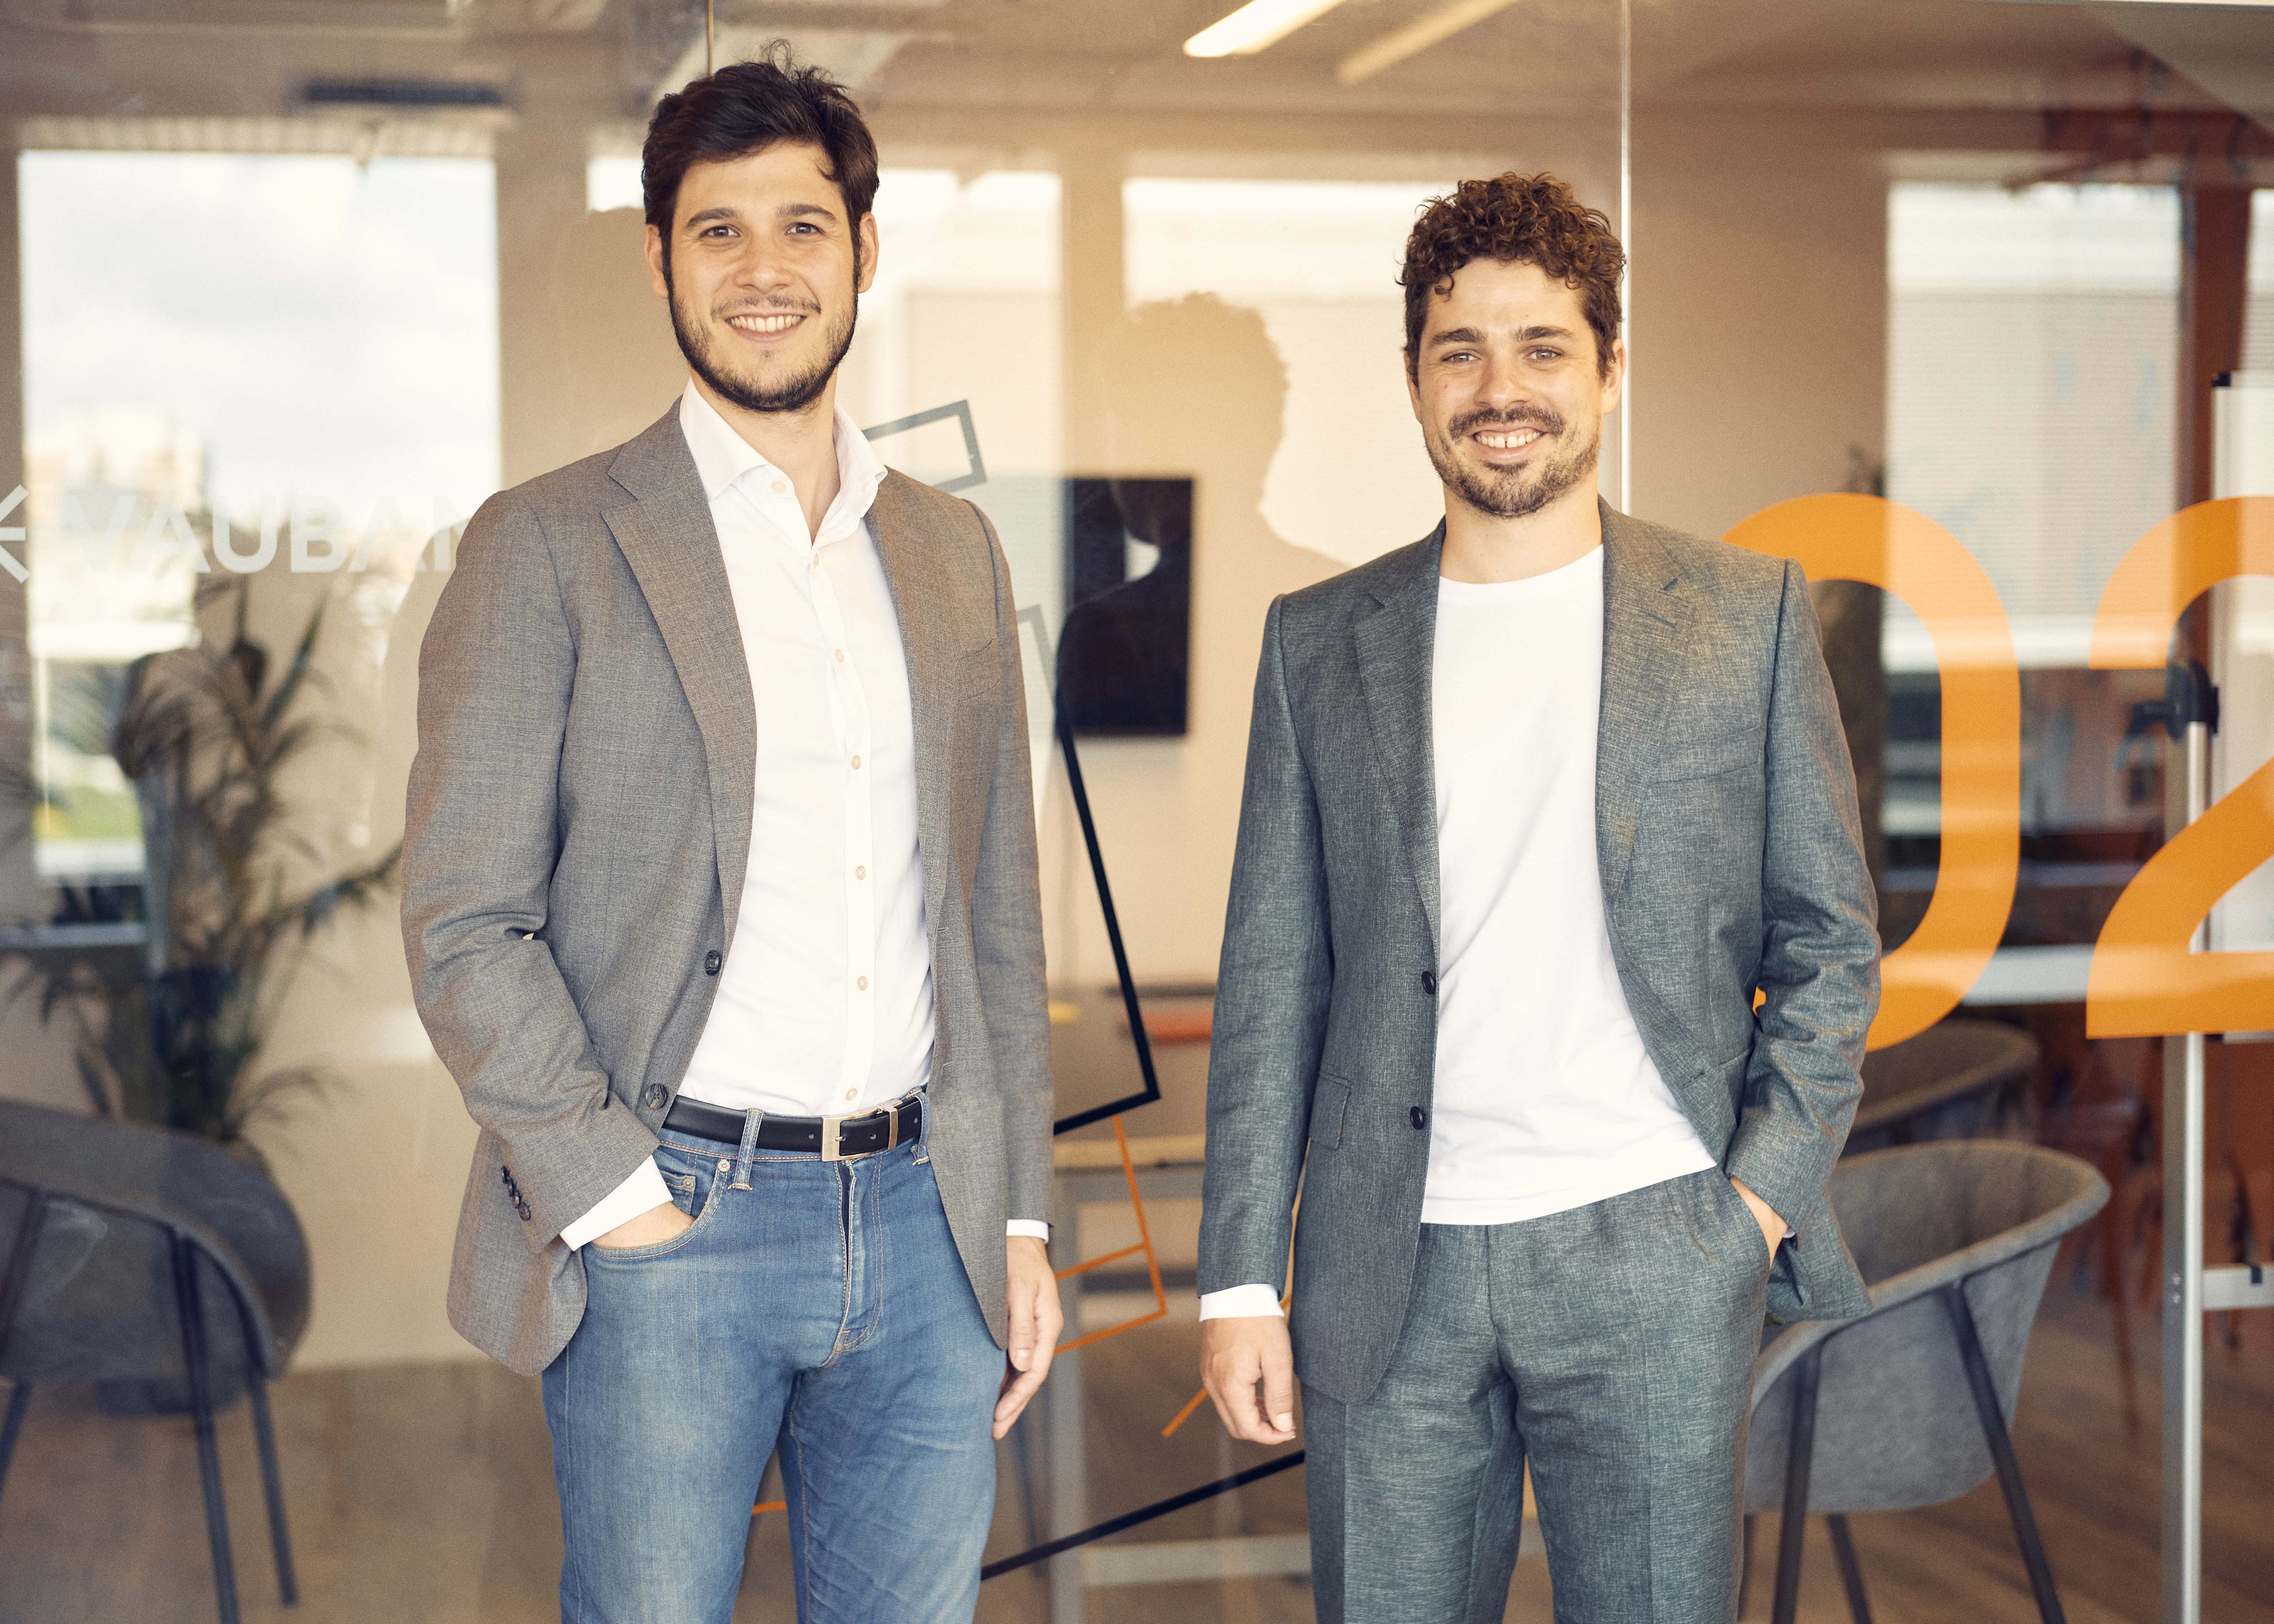
Vauban, the platform that provides venture capital fund managers with everything they need to raise a fund and invest capital quickly, today announces that it has closed £4.7m.
Investors include co-leads Pentech and Outward, in addition to 7percent Ventures and MJ Hudson. A roster of high profile angel investors have also participated; This includes the CEO of Nested Matt Robinson; the founder of Grabayo, Will Neale; the founder and CEO of ComplyAdvantage, Charles Delingpole; Partner at Augmentum Fintech Perry Blacher; and Al Giles, from legal services provider Axiom.
Through its end-to-end platform, Vauban provides VCs and angel investors the tools necessary to raise funds, easily create angel syndicates, and effectively manage fundraising and investment activities. The platform enables users to set-up and deploy Funds and SPVs, from multiple global investment jurisdictions, at a fraction of the usual time and cost, covering everything structuring, legal documents, investor onboarding, banking and reporting within a single integrated platform.
Vauban is onboarding at least one new client every day. Over $1bn has been invested via the platform. Current VC users include Anthemis, Passion Capital and Octopus Ventures. In total, over 5,000 LPs are using the platform.
Founder and Co-CEO Rémy Astié said, "When raising capital, VCs are obliged to undertake a countless number of time-consuming, long-winded and expensive processes. This deter many prospective managers from raising a fund, and therefore prevent many founders from getting funded. “
“Our goal is to reduce the friction between those who have the capital, and those who need it to solve humanity's biggest problems. So, we decided to start by rebuilding the infrastructure on digital rails, because it's mission critical in order to provide a great UX to everyone in the industry: GPs, LPs and Founders. The next step is to build a super platform and network on top of our existing platform, in order to offer life-changing services to all parties involved.”
This comes against the backdrop of unprecedented investment activity in European tech. With €41.8bn raised across Europe in the first half of 2021, up from €32.6bn in the entirety of 2020, the addressable market for European VC investors is increasing.
In recent years, venture capital activities across Europe have evolved, with an increasing number of established VC firms now managing several funds. More funds are using Special Purpose Vehicles (SPVs) to participate in specific deals, make secondary investments, or to set up 'sidecar’ funds alongside EIS vehicles or their main institutional funds. In addition, angel investors are professionalizing and syndicating; they are grouping together to increase their dealmaking potential and access to dealflow.
These developments have led to an increased demand for access to the tools that help investors raise and pool capital - including fund structuring, banking requirements, legal documentation, fund admin, reporting, investor onboarding, ongoing LP management and more.
Ulric Musset, Founder and Co-CEO says, "One of the biggest catalysts for new startup creation was the launch of Amazon Web Services in the early 2000s. It drastically decreased the cost and complexity of launching a new tech company. Unfortunately the way these startups were funded remain in the past. That's what we are changing. From operators-turned-investors starting their first fund to established VC firms launching their co-investment program, we want everyone to be able to seize opportunities when they arise. We believe Vauban will have the same impact that AWS has had on the startup ecosystem.”
Andi Kazeroonian, Investor at Outward VC, said, “Despite the meteoric growth in alternative investments in recent years, the infrastructure the industry relies on has failed to evolve. Simply creating and administering an investment vehicle remains synonymous with lengthy, cumbersome and expensive processes fragmented across multiple service providers. Vauban’s integrated platform has turned this on its head with a relentless focus on product and user experience, which has unsurprisingly led to exceptional organic growth and its emergence as the standout category leader in Europe. We have high conviction that Vauban will play a significant role in powering the growth of the alternate asset industry as it continues to move from the periphery of the global investment landscape into the mainstream, and are delighted that they have chosen Outward VC as its long term partners on this journey.”
Craig Anderson, Partner at Pentech said, “We like to invest in category-leading companies with big ambitions for growth. We believe Vauban is building a modern infrastructure for the alternate asset market which enables users to set up, deploy and manage their funds and SPVs in just a few hours. We have been very impressed by what Remy, Ulric and the Vauban team have achieved to date, both in terms of building a truly compelling product and their tremendous commercial progress, and we are very excited about their growth potential moving forward.”
Using the money raised, Vauban will deepen its tech and regulatory infrastructure, and launch a new office in Luxembourg to strengthen its European offering, alongside its headquarters in London.
- 06:00 am

PCI Pal, – the global provider of cloud-based secure payment solutions – has upgraded Chill Insurance’s payment security solution to aid secure and compliant payment card transactions, regardless of whether contact centre agents are working onsite or remotely from home.
During the pandemic, most agents transitioned to working remotely, which spurred the decision to implement a more robust payment security process to ensure that PCI DSS compliance was maintained regardless of agent location.
Chill Insurance also required a solution that would easily integrate with its existing communications Genesys PureConnect platform, managed by contact centre specialist Wren Data, and which would make the payment process seamless for customers.
Chill Insurance selected PCI Pal Agent Assist, buoyed by its ease of use, integration with Genesys PureConnect and its ability to be deployed via the cloud.
John Riordan, Chief Information Officer for Chill Insurance, said, “We had been using a solution whereby our agents paused call and screen recordings during dialogue with customers at the point where the customers were providing their card payment details. We wanted to update our contact centre payment processes to reinforce our PCI DSS compliance and embrace remote working, without breaking the conversation between our contact centre staff and customers.”
In contrast to the previous method used, PCI Pal Agent Assist allows conversations between callers and contact centre agents to continue uninterrupted, so that if customers have any difficulty while inputting their card details, the advisor can talk them through the process and provide assistance where required.
Concludes John, “With a new system going live you prepare yourself for an initial learning curve, however I was really pleased of just how smoothly this went. When looking at our metrics, there was no negative impact on call times or sales conversions. In fact, the overall feedback is that it’s now a far cleaner process between the agent and the customer.
“Our objective from the outset was to reinforce our PCI compliance and to update our operation from a manual process and replace it with a more systematic solution that provides assurance that calls and information coming through are being handled in a compliant way. That objective has been achieved and it’s working well.”
For more information on Chill Insurance visit www.chill.ie, or for more details regarding PCI Pal, visit www.pcipal.com, call +44 207 030 3770 to arrange a demonstration or follow PCI Pal on Twitter.
- 04:00 am

With FICO® Originations Solution, Powered by FICO® Platform, financial institutions can eliminate barriers to customer acquisition as more consumers opt to open accounts digitally
- FICO has launched its next-generation loan origination solution, FICO® Originations Solution, Powered by FICO® Platform, giving financial services providers the ability to transform their customers' digital onboarding experience.
- Solution tackles risk of application abandonment, as FICO research suggests 23 percent of consumers would go to a competitor if they have to complete excessive steps in the application process.
- Built on FICO® Platform incorporating decades of FICO intellectual property, the solution makes decisioning faster, smarter, and more profitable.
- The extensible cloud-native solution is "future-ready" and scales to meet any business demand.
The pandemic forced many financial institutions around the world to rethink their business strategy to better compete in a digital-first economy. According to recent research[i] by leading applied intelligence company FICO, 31 percent of UK customers expressed willingness to open an account digitally using an app or website. However, 8 percent give up completely if they are asked to complete excessive steps, while 23 percent will go to a competitor. And only 15 percent of respondents said they would complete the process if asked to move outside digital channels – for example, by visiting a branch.
Originating a new account is a critical decision affecting 80 percent of the measureable risk throughout the lifecycle of an account. Getting digital-first acquisition right is therefore crucial.
In response FICO has launched FICO® Originations Solution, Powered by FICO® Platform, the next-generation of its best-in-class loan origination solution. The solution is powered by the industry-leading FICO® Platform and delivered globally on Amazon Web Services (AWS) Cloud. It empowers businesses to deliver exceptional, personalized customer experiences by automating a frictionless customer journey throughout the loan origination process.
FICO’s Originations Solution, Powered by FICO® Platform allows financial services providers to make more precise, value-based decisions at origination while helping them grow more profitable portfolios and manage customer-level risk.
"FICO Originations Solution, Powered by FICO Platform has proven to be the perfect solution for standardizing OTP's workflows while still maintaining country-specific rules and processes," said Gyorgy Kiss-Haypal, group chief risk officer at OTP Group, one of the largest independent financial services providers in Central and Eastern Europe. "Not only is FICO Platform helping us balance pan-continent standardization with in-country localization, but it is also providing improved cost efficiency while increasing our control over risk management for new customers."
By having FICO Platform drive the Originations Solution, organizations can see benefits including:
- Fast, flexible, frictionless digital account opening: Delightful, meaningful user experiences have become standard across industries. FICO® Originations Solution, Powered by FICO® Platform enables financial institutions to easily deliver those experiences, no matter where the organization is in their digital transformation journey.
- Efficient, IP-laden configuration templates across domains: These configurable templates incorporate decades of leading FICO origination IP and best practices, enabling business users to adopt existing end-to-end origination solutions that meet their needs, rather than waiting for constrained IT staff to develop solutions for them.
- Improved automation, autonomy, and access: Financial institutions can reduce their dependence on multiple technology vendors by automating and replacing their legacy systems with a unified, centralized, cloud-based solution that works across products, regions, and lines of business.
- More precise, data-driven predictions about what customers will do: Businesses can use the right combination and sequencing of data to drive insights, then use analytics to mathematically identify the best possible decisions and products for each customer.
- Easy access to 130+ global data sources through FICO's ever-growing data library: With increased access to data, financial institutions can make faster and better customer decisions across every line of business.
- Future-proof, agile decision-making that is easily scaled across multiple regions: Standardize and centralize legacy originations systems across multiple regions to drive greater efficiencies, transparency, and big economies of scale.
- Underlying capabilities provide a foundation for the future: Firms can easily add more customer-centric decisioning applications in other areas of the business, such as customer management or fraud prevention.
"Unlike point solutions, FICO Origination Solution is delivered on a unified decisioning platform," said Nikhil Behl, CMO at FICO. "The additional benefits of deploying solutions on FICO Platform are significant, including the ability to share decision assets and platform capabilities across the entire customer lifecycle, from onboarding and originations through customer management, fraud, and collections optimization. FICO Platform goes beyond any single use case to give firms true customer-centricity with deep, real-time, 360-degree insights into every customer touch, across all channels, for the full duration of the customer lifecycle."
Learn more about FICO's global digital account opening research findings across 14 countries and 14,000 consumers here.
- 09:00 am
- Debt levels among variable workers* have increased by ten percentage points throughout the pandemic, with the number of variable workers with debts of between £5,000 and £10,000 more than doubling from 2020 (10% to 23%).
- Of the 25-34 year olds that expect to increase borrowing in the next six months, 31% need additional funds to buy Christmas gifts for friends and family.
- These groups of society are also more likely to use higher cost credit options, such as an unauthorised overdraft.
- While it’s important people can access credit when they need it, consumer protection must remain a top priority.
New research has found that the number of people with debt in the UK has increased by ten percentage points in just six months (64% to 74%), with variable workers, which includes gig workers and freelancers likely to be acutely impacted, alongside young people aged between 18 and 34, according to the latest findings from Credit Kudos’ Borrowing Index.
The research found that the finances of variable workers and young people have been unduly impacted by the pandemic, with four in ten (40%) 18-34 year-olds and almost half (47%) of variable workers saying they have had to borrow more than usual since the start of the pandemic. This compares to the national average of 21%.
The landscape is particularly concerning for variable workers, especially when it comes to levels of debt. In the first iteration of the Borrowing Index in early 2020, only one in ten (10%) variable workers had debts of between £5,000 and £10,000. This figure has now more than doubled to around one in four (23%).
While these groups of society are clearly more in need of financial support to help them get by, they are also most likely to have to turn to higher cost borrowing options, for example unarranged overdrafts. On average 24% of the UK population have used some form of higher-cost, short term credit, but variable workers are more than twice as likely to do so than the rest of the population, at 51%. The figure is also significantly higher among younger generations, at 35% for 18-24 year olds and 30% among 25-34 year olds.
This is perhaps unsurprising, given that 3.6 million, or 40% of 25-34 year olds and around 850,000** variable workers have previously struggled to access mainstream credit. This is an issue that has been exacerbated by COVID, with 78% of lenders saying they implemented a change in their lending policies during the pandemic, in part due to difficulty verifying borrowers’ income and a decision to avoid ‘higher risk’ customers during an uncertain period. When considering that over half (51%) of variable workers and 44% of 25-34 year olds said that COVID had a significant negative impact on their income, it’s clear to see why many struggled to access affordable credit during this time.
It’s crucial that financial service providers are lending responsibly. Having access to the right credit options is a key enabler of financial flexibility, but if people are unable to access mainstream credit - despite being able to afford it - it can leave them with no other option but to turn to higher cost sources of credit. Traditional credit data is based on a narrow view of someone’s financial situation, making it difficult to accurately assess an individual’s ability and willingness to repay. If a person hasn’t taken out credit before, for example, or rents rather than makes regular mortgage repayments, lenders may consider them high risk - even if they have never missed a payment. When you add in the disruptive effects of the pandemic on people’s finances and the growth in non-traditional income patterns as the future of work shifts to more freelancers and flexible roles, the ability to determine someone’s true affordability and creditworthiness becomes even more complex.
Transforming this, Open Banking allows individuals to securely share their financial transaction data, giving their chosen lender a full picture of their affordability and creditworthiness - which enables the lender to make more accurate, informed and responsible decisions.
Freddy Kelly, CEO and co-founder at Credit Kudos, said: “The financial shockwaves of the pandemic will continue to reverberate for years to come, especially for those who were already financially underserved, such as young people and variable workers. For these groups, access to affordable credit is essential, and lenders should be looking for ways to serve these people in a responsible, sustainable way. The implementation of innovations such as Open Banking are helping to tackle these issues and paving the way for a brighter financial future. This use of data is enabling the creation of tools that open up access to affordable credit for more people, allowing lenders to expand their customer base while continuing to put customers first.”

Kriya Patel
CEO at Transact Payments
Despite industry concerns over the UK’s direction after Brexit (not to mention post-pandemic), there are compelling reasons to believe the country will continue to play see more
- 03:00 am

Collaboration will enable Western Union Business Solutions’ customers to support a range of initiatives with certified carbon credits, from renewable energy to clean water access, as part of their hedging strategy
Western Union Business Solutions, the payments arm of The Western Union Company (NYSE: WU) a global leader in cross-border, cross-currency money movement and payments, has partnered with climate and sustainability pioneer Gold Standard to provide a Green Hedging offering for all types of organisations. The partnership will enable customers of Western Union Business Solutions to financially support sustainable initiatives as part of their hedging strategy, empowering them to make a positive global impact with ease.
Available to new and existing customers, the offering will enable businesses to select from a range of Gold Standard-certified climate and sustainability initiatives, supporting chosen projects at a cost of just 0.1% in addition to the notional trading amount. Project categories range from community-based energy efficiency and clean water access, land use activities and nature-based solutions to renewable energy and waste management. Western Union Business Solutions will then match this fee – contributing a total of 0.2% to the cause – and donating it in full in the customer’s name.
Gold Standard’s projects have seen over 173 million tonnes of CO2 reduced worldwide to date. Using customised safeguards, requirements, and methodologies to measure and verify impact, its experts will work with Western Union Business Solutions to provide participating customers with insight on the projects they have supported.
Alex Lawson, Regional Director of Hedging – UK and Europe at Western Union Business Solutions, commented: “We are excited to bring our customers this opportunity to make a positive impact in such a simple way. By partnering with Gold Standard, which embodies best practice for climate and sustainable development initiatives, customers can be confident in the integrity of every green investment made. It makes complete sense to leverage a planned hedging transaction to also drive genuine change and we at Western Union Business Solutions remain committed to our own sustainability vision, which is why we promise to match every penny paid by our customers for this cause.”
With more than $25 billion in shared value already created for climate action and sustainable development, Gold Standard initiatives are designed to quantify, verify, certify, and maximise progress towards the UN’s Paris Climate Agreement and the Sustainable Development Goals. This means that customers partaking in the Green Hedging project know that their contribution is creating a real impact.
Margaret Kim, CEO of Gold Standard, said: “We are delighted to partner with Western Union Business Solutions in launching this initiative. It is promising to see the financial system being channelled to deliver positive impact – something which could be echoed further across the industry. By making the process simple for customers, Western Union Business Solutions’ offering removes barriers to meaningful action. By participating in this initiative, even SMEs can make a measurable difference to the world we live in.”
- 02:00 am

Trulioo’s automated identity verification solution receives a positive assessment as an age verification system (AVS) concept in telemedia
Trulioo, the global identity verification leader, today announced that the Kommission für Jugendmedienschutz (KJM) or the Commission for the Protection of Minors in the Media, has certified its solutions can be implemented in the German market to verify the ages of end users trying to access age-restricted content.
After a robust assessment, the KJM concluded that Trulioo’s identity verification solution complies with both the legal and technical requirements of the Interstate Treaty on the Protection of Minors in the Media (JMStV).
By enforcing age verification checks, it becomes difficult for youth and children to access age-restricted content in telemedia.
“Trulioo’s age verification solution provides a straightforward and seamless user experience for age-appropriate users while ensuring minors don’t engage in potentially harmful content,” said Steve Munford, Trulioo CEO. “By turning to Trulioo’s solutions, media providers and businesses can perform age checks that adhere to compliance measures while upholding a privacy-centric approach in handling this sensitive data.”
Trulioo GlobalGateway provides secure access to reliable data sources to verify a person’s age in real-time. Media providers and businesses have flexibility in setting minimum age parameters, ensuring age-appropriate visitors can access content while minors are kept out. The identity data provided by the visitor is checked against independent databases to see if the information positively matches. GlobalGateway provides access to over 400 data sources to reliably and securely verify the identities of over 5 billion individuals around the world through one API.
- 05:00 am
Proponents of digital currencies claim that in the not-too-distant future, they will become a new financial reality. Despite the current instability in the stock market, digital assets continue to grow in popularity on a global scale. More than 73 million people will have used a blockchain wallet by the end of 2021, according to predictions (15.87 % growth within 6 months).
Furthermore, crypto users prefer to store their assets on exchanges rather than in their personal wallets. Bitcoin users. More than 60 % of investors and dealers who own digital assets do so via exchanges, according to data currently available. 380 cryptocurrency exchange sites have been identified by Coinmarketcap, which are grouped into three categories: spot exchanges, derivatives exchanges, and decentralized platforms.
This has resulted in the market being more accessible to new entrants, and the sector as a whole seems to be quite promising. Before delving further into the operations and dangers of the cryptocurrency market, newbies should get acquainted with how does Bitcoin exchange work.
What is a crypto exchange and what are the trading platforms types
To begin, novices need to have a basic understanding of what a cryptocurrency exchange is and the features it offers. To put it another way, an exchange is a platform that allows people to buy, sell, and trade digital currencies easily and quickly.
What are the most widely used forms of crypto exchanges?
Exchanges that deal in bitcoin and other cryptocurrencies. There is no fiat cash on these websites.
Digital assets to fiat currency exchanges make it easy to move money back and forth between the two.
Decentralized exchanges that provide unparalleled levels of security and anonymity
To comply with the law, centralized exchanges must be licensed.
Platforms for margin trading provide traders access to additional borrowing power, which they may use to boost their profits. Hazards, on the other hand, grow in direct proportion to the increase in risk.
Additionally, a crypto exchange may exhibit several traits.
Initial market entry stages
The following phases comprise the how to start crypto exchange step-by-step guide:
License and legal considerations:
The first problem is the need to secure a license and do legal research in order to ensure that your platform complies with current regulations. The exception is decentralized exchanges; in the meanwhile, the market is leaning toward regulation.
Liquidity provider:
Liquidity is a critical component of a successful trading platform. Your order book should execute bid and ask orders swiftly; this is why you should apply to prominent crypto liquidity providers.
Software that is appropriate:
Businesses may spend between $100 and $150,000 on custom software developed for their unique needs. Another approach allows younger players to take advantage of lower-priced WL solutions by using a third-party service. Meanwhile, a platform is under the jurisdiction of a service provider. A provider's servers host an exchange.
Additionally, the procedure entails a number of critical considerations:
Financial (set up deposit and withdrawal procedures, utilize cold storage facilities, and etc.);
Marketing (advertising should increase brand recognition);
Technological (connect APIs, matching engines, and other integral components).
There is a significant probability of problems, thus novices are encouraged to seek the help of firms that provide turnkey solutions. Quality items and cutting-edge technology innovation come together in B2Broker. Turnkey crypto exchange platforms are one such approach.