
Published
- 09:00 am
GreenKey Technologies, creator of an artificial intelligence (AI) and voice-driven collaboration tool for financial market participants, announced today that the U.S. Patent and Trademark Office has accepted its application for improved speed and transcription accuracy of automatic speech transcription based on multiple speech-to-text engines.
The speech recognition engine, GreenKey Scribe, can reduce transcription error rates by 50 percent using the approach documented in the new patent. Scribe uses an array of transcription engines trained on different content domains and automatically selects the engine that will perform best on a particular segment of a conversation. The transcription engines that Scribe leverages can be a combination of models built by GreenKey, engines built by partner transcription providers and cloud transcription services.
Other multi-engine approaches send audio to many engines in parallel and compare the transcriptions. This process can be slow and computationally expensive. Through the method detailed in GreenKey’s new patent, termed “Scribe SwitchBoard,” Scribe can analyze an audio file in less than a second to determine which engine will transcribe it best, without having to send it to all of them.
Tom Schady, GreenKey Chief Technology Officer, said: “We’re in an exciting era of rapid advancement along several avenues of speech AI. In order to deliver the best, most accurate results for our customers, we complement our technology with the most cutting-edge solutions available today. This allows us to embrace innovation across the entire spectrum of automatic speech recognition (ASR).”
GreenKey Scribe was designed to help firms transcribe noisy, jargon-heavy audio with high accuracy in a variety of industries, from Finance to Emergency Services, where common cloud transcription solutions typically perform poorly due to the audio content. With its latest transcription method, Scribe enables firms to maintain high transcription accuracy across a variety of accents, languages and audio quality environments.
Dr. Tejas Shastry, Chief Data Scientist for GreenKey Technologies, said: “Scribe’s SwitchBoard changes the paradigm on how we train AI to transcribe human speech. Firms can train their own customized models, and Scribe can leverage them all together. Beyond increasing accuracy, it opens up the possibility to transcribe multi-language conversations with a single engine.”
- 05:00 am
Econocom UK, a European digital services provider, and JTRS, a leading supplier of technology solutions and member of the Econocom Group, have announced a strategic partnership with BT to provide end-to-end solutions to their customers through a wide range of BT and EE business services.
The partnership came about following BT’s search for companies that could help deliver its breadth of products and solutions via a differentiated approach in the SME and education sectors. Econocom and JTRS were chosen due to their experience in both sectors and their expertise in designing flexible subscription & project finance offerings.
As an authorised partner of BT, Econocom/JTRS is now able to provide a range of additional BT services to customers, including telephony, internet, cloud VoIP (voice over IP), BTnet leased lines, managed WAN (wide area network) as well as the full range of EE mobile voice and data solutions.
This partnership has already resulted in the creation of a true end-to-end EE mobile subscription for business customers including devices, lifecycles services and airtime. This has enabled UK companies and institutions to adopt a BOS (Business Optimisation Services) solution that will now also include EE business airtime plans for voice and data as part of their subscription.
Chris Labrey, MD for Econocom UK & IRL, says: “This partnership signals a huge step forward for the potential of our BOS offering. With EE business airtime and 4G capabilities now included, our customers will be able to benefit from devices that work straight out of the box, with no need to go to a separate network provider in order to get fully up and running. This is an incredibly valuable proposition in a world where businesses are looking to make their lives easier by consolidating the number of suppliers they work with.”
Tim Morgan-Hoole, Managing Director, JTRS, says: “This strategic partnership with BT allows us to essentially provide customers with a ‘one-stop-shop’ for all of their technology needs. With these new solutions available, we are capable of designing, supplying and supporting any offering a customer may wish to implement. We can also help those looking to build any new premises or upgrade/improve their current systems and infrastructure.
Steve Rathborne, Director Business Partner Channel at BT says: “By giving Econocom and JTRS access to BT’s expertise, technology and resources, we are confident of helping customers adapt to market changes quickly and get the digital technology they need to meet today’s and tomorrow’s needs. Our partners play a big part in providing differentiated services to business customers and we look forward to extending this opportunity in collaboration with Econocom and JTRS.”
- 01:00 am
CA Technologies (NASDAQ:CA) today announces that it has secured a UK Cyber Essentials certification to protect customer data at a global level.
Cyber Essentials is a UK Government-backed scheme designed to protect an organisation and its data against a wide range of common cyber attacks. CA Technologies made a strategic decision to secure the certification for protection of its global customer data, rather than just its UK-based customer data.
“The UK Cyber Essentials provides a strong foundation for consistent, effective measures to protect our customer data against a wide range of cyber threats, and it helps us communicate clearly with our customers about the types of security measures we have in place,” said Duncan Bradford, CTO, North for CA Technologies. “We felt it was important to roll out this certification on a global basis because the types of threats that Cyber Essentials is designed to protect against do not recognize national borders.”
The UK’s Minister for Digital and the Creative Industries, Margot James, said: "It is important companies take advantage of Government's Cyber Essential programme to help protect themselves against the most common cyber threats. I welcome CA Technologies’ commitment to cyber security and congratulate them on achieving the Cyber Essentials certification."
Various laws around the world, like the EU’s General Data Protection Regulation (GDPR), emphasize the need for investments in security to protect data. Cyber Essentials gives CA’s customers additional confidence about the company’s efforts to protect customer data and its compliance with these laws.
Many of the CA proprietary solutions used to protect internal networks and systems are ideally suited to help both CA and its customers align with many of the Cyber Essentials controls. These include CA Privileged Access Management, CA Advanced Authentication, CA Single Sign On, CA Identity Management, CA Identity Governance, and CA IT Client Automation.
CA Technologies worked with 2-Sec, a leading London-based integrated cyber security consultancy, to manage the certification process.
Find out more on our blog.
- 08:00 am
Firm draws on expertise in Digital and User Experience (UX) design for Banking, Financial Services and Insurance to provide industry-leading insight
Synechron, the global financial services consulting and technology services provider, has today announced the launch of its newest eBook, UX Design for Enterprise Apps. The eBook serves as an instructive reference guide to help firms institutionalize best practices, benchmark their User Experience (UX) Maturity, and innovate their digital and design initiatives.
UX is becoming one of the top priorities for banking and insurance institutions as they face changing user expectations and demands, which have changed drastically over the last decade due to the Digital Revolution. Clients are demanding more intuitive usability, on-demand services, and personalized experiences with just a click. While all firms strive to be on the leading edge of innovation, simplicity is key for great UX, while still delivering streamlined, interactive and intuitive user experiences to transform the approach to client interactions. Given this, it has never been more important within the Financial Services and Insurance industries to design highly usable, data-driven systems that are responsive to a new set of user’s needs and expectations.
As a leader in Digital User Experience Design for Banking Financial Services and Insurance (BFSI), Synechron provides instructive advice and insight on how to craft a successful and strategic approach to UX in its newest eBook, which focuses on:
- What separates UI from UX – and how to move from uniformed design to more strategic design initiatives informed by design thinking, research, iterative design, and more.
- User Experience Design (UX, UXD, or XD) – best practices for bringing the human aspect to technology and design through a blend of creative, behavioral, and analytical skills.
- Design Trends and Innovations – front-end visual and engineering approaches to achieve strong aesthetic, optimized speed and throughput, and to overcome challenges related to legacy infrastructure.
- The Role of the UX Designer – to create a design solution that aligns with a user’s mental model and context of use, and effectively delivers business objectives with technical feasibility.
- A UX Maturity Assessment – allowing readers to benchmark their UX maturity against a core set of criteria to measure their applications’ effectiveness, identify gaps, and elevate User Experience.
Through the eBook, firms can gain valuable strategies to help increase efficiency and productivity, enhance adoption rates, improve brand loyalty, speed time-to-market, and reduce total cost through design.
“Today, UX is a key differentiator for banks and financial institutions. To remain competitive and keep up with the evolving needs of changing and increasingly digital client demands, it is critical for institutions to have an effective user experience and design strategy,” said Ashish Nangla, Senior Director at Synechron. “To do this, they must have a deep understanding of end-user requirements and their different needs in varying contexts. We have created this guide to assess their UX maturity and compile key factors to begin on the path to success.”
- 06:00 am

Viva Wallet, an official sponsor at Money 20/20 Europe, an offer of 0% acquiring fee available from July 2, 2018. Retail merchants who use Viva Wallet acquiring services to accept European MasterCard and Visa cards, will benefit from a 0% acquiring fee when they use their Viva Wallet business cards to utilise their funds.
The new offer applies both to card-not-present (e-commerce) transactions as well as to card-present transactions via Viva Wallet’s card terminals. To complement the offer, Viva Wallet introduced its innovative Android™ card terminal by PAX global technology at Money 20/20, which accepts a wide range of alternative payment methods and local closed-loop card schemes.
Dr Yannis Larios, Business Development Director at Viva Wallet, says: “We always strive to combine our top-notch cloud-based processing infrastructure and our principal membership for acquiring and issuing services, to benefit our merchant base in Europe. Today, we give our retail merchants the unique opportunity to have zero charges for all their Visa and MasterCard transactions, which are made by European consumers, when they use their funds through our business debit cards.”
- 09:00 am
Paysafe launches new global research into consumer payment trends
The shift towards ‘frictionless’ payments – i.e. invisible transactions that take place ‘behind the scenes’ in apps – is being held back by UK consumer concerns over security and data privacy, according to new research conducted by Paysafe. The report from the leading global payments provider uncovers some unexpected findings. For these ‘invisible’ payments, figures show:
- 52 percent of UK consumers cite fraud as the biggest barrier to using them. 43 percent express concerns around the use of their data;
- Two-thirds of British consumers (67 percent) think voice-activated systems are not secure. 69 percent worry about being overcharged if they used this type of service; and
- 59 percent report that checkout-free stores – where smart technologies record the shopping basket and automate payments – sound too risky, or they’d need to know more before using them.
Meanwhile, other emerging payment methods are polarising consumer opinion – 39 percent of the UK public would let fridges automatically re-order food, but 43 percent don’t expect to adopt the technology in the next two to three years.
The report, called Lost in Transaction: Payment Trends 2018, is an international research study investigating consumer attitudes to new and traditional payment methods. The research incorporates consumer views from the UK, US, Canada, Germany and Austria, and draws comparisons with Paysafe’s inaugural Lost in Transaction report in 2017.
Perhaps surprisingly, cash continues to thrive as the most common form of payment: 88 percent of consumers used it in the past month to make a purchase. ATM visits were up too – 89 percent had visited one in the last month compared to 84 percent in 2017. Yet, as contactless has expanded, 62 percent of UK consumers carry less cash than a year ago, falling from an average of £33 last year to £21 in 2018.
Contactless has continued to grow rapidly in the UK, where 54 percent of consumers had used it in the previous month. That’s in stark contrast to the US at just 3 percent, in spite of the fact that 40 percent of Americans reported trying contactless in 2017. In Canada, 58 percent of consumers tried contactless in 2017 but only 19 percent used it in the last month.
However, even if people are carrying less physical cash, they are finding other ways to keep cash at the forefront in the overall mix. While the UK has the highest adoption of contactless, in Austria and Germany, cash replacement systems are being used by 12 percent and 9 percent of respondents respectively; and in North America, prepaid cards are the most popular cash alternative, used by 18 percent of Canadians and 16 percent of Americans respectively.
Commenting on the research, Oscar Nieboer, Chief Marketing Officer, Paysafe Group, said: “Despite the apparent benefits of low-friction payment technologies, these findings suggest many consumers aren’t ready to lose visibility of the payment process. It’s clear that the benefits are not unilaterally agreed upon, with cultural and infrastructure trends at play, and it may be some time before adoption is widespread. In the meantime, there’s a need to continue servicing the cash consumer, as well as providing options for contactless payments as the UK is so advanced in this area of payments compared to other countries.”
The report also highlights the growth of digital wallets: 61 percent of UK respondents had used one for an online purchase in the past month – more than either credit or debit cards. Digital wallet usage averaged 50 percent globally and ranged from 39 percent in the US to a high of 61 percent here in the UK.
But when it comes to fraud, the report highlighted a convenience versus risk paradox and a geographical split in how fraud impacts payment behaviour locally:
- 65 percent of Britons and 70 percent of Americans believe online fraud is inevitable, but only 28 percent of Germans and 26 percent of Austrians hold the same view;
- More consumers in Germany and Austria choose to pay by invoice rather than debit card. 55 percent of Austrians and 49 percent of Germans say it feels safer.
Nieboer adds: “If retailers, merchants and payments companies want to disrupt the old way of doing things they must make all underlying processes feel secure. Consumers want convenience, but they want protection too. They are making sensible choices when it comes to security and are willing to change what they’re used to ensure they’re not at risk of fraud. For instance, nearly four in five Britons prioritise the use of a website that already has their payment details – the highest amongst the countries surveyed in this report.”
- 08:00 am
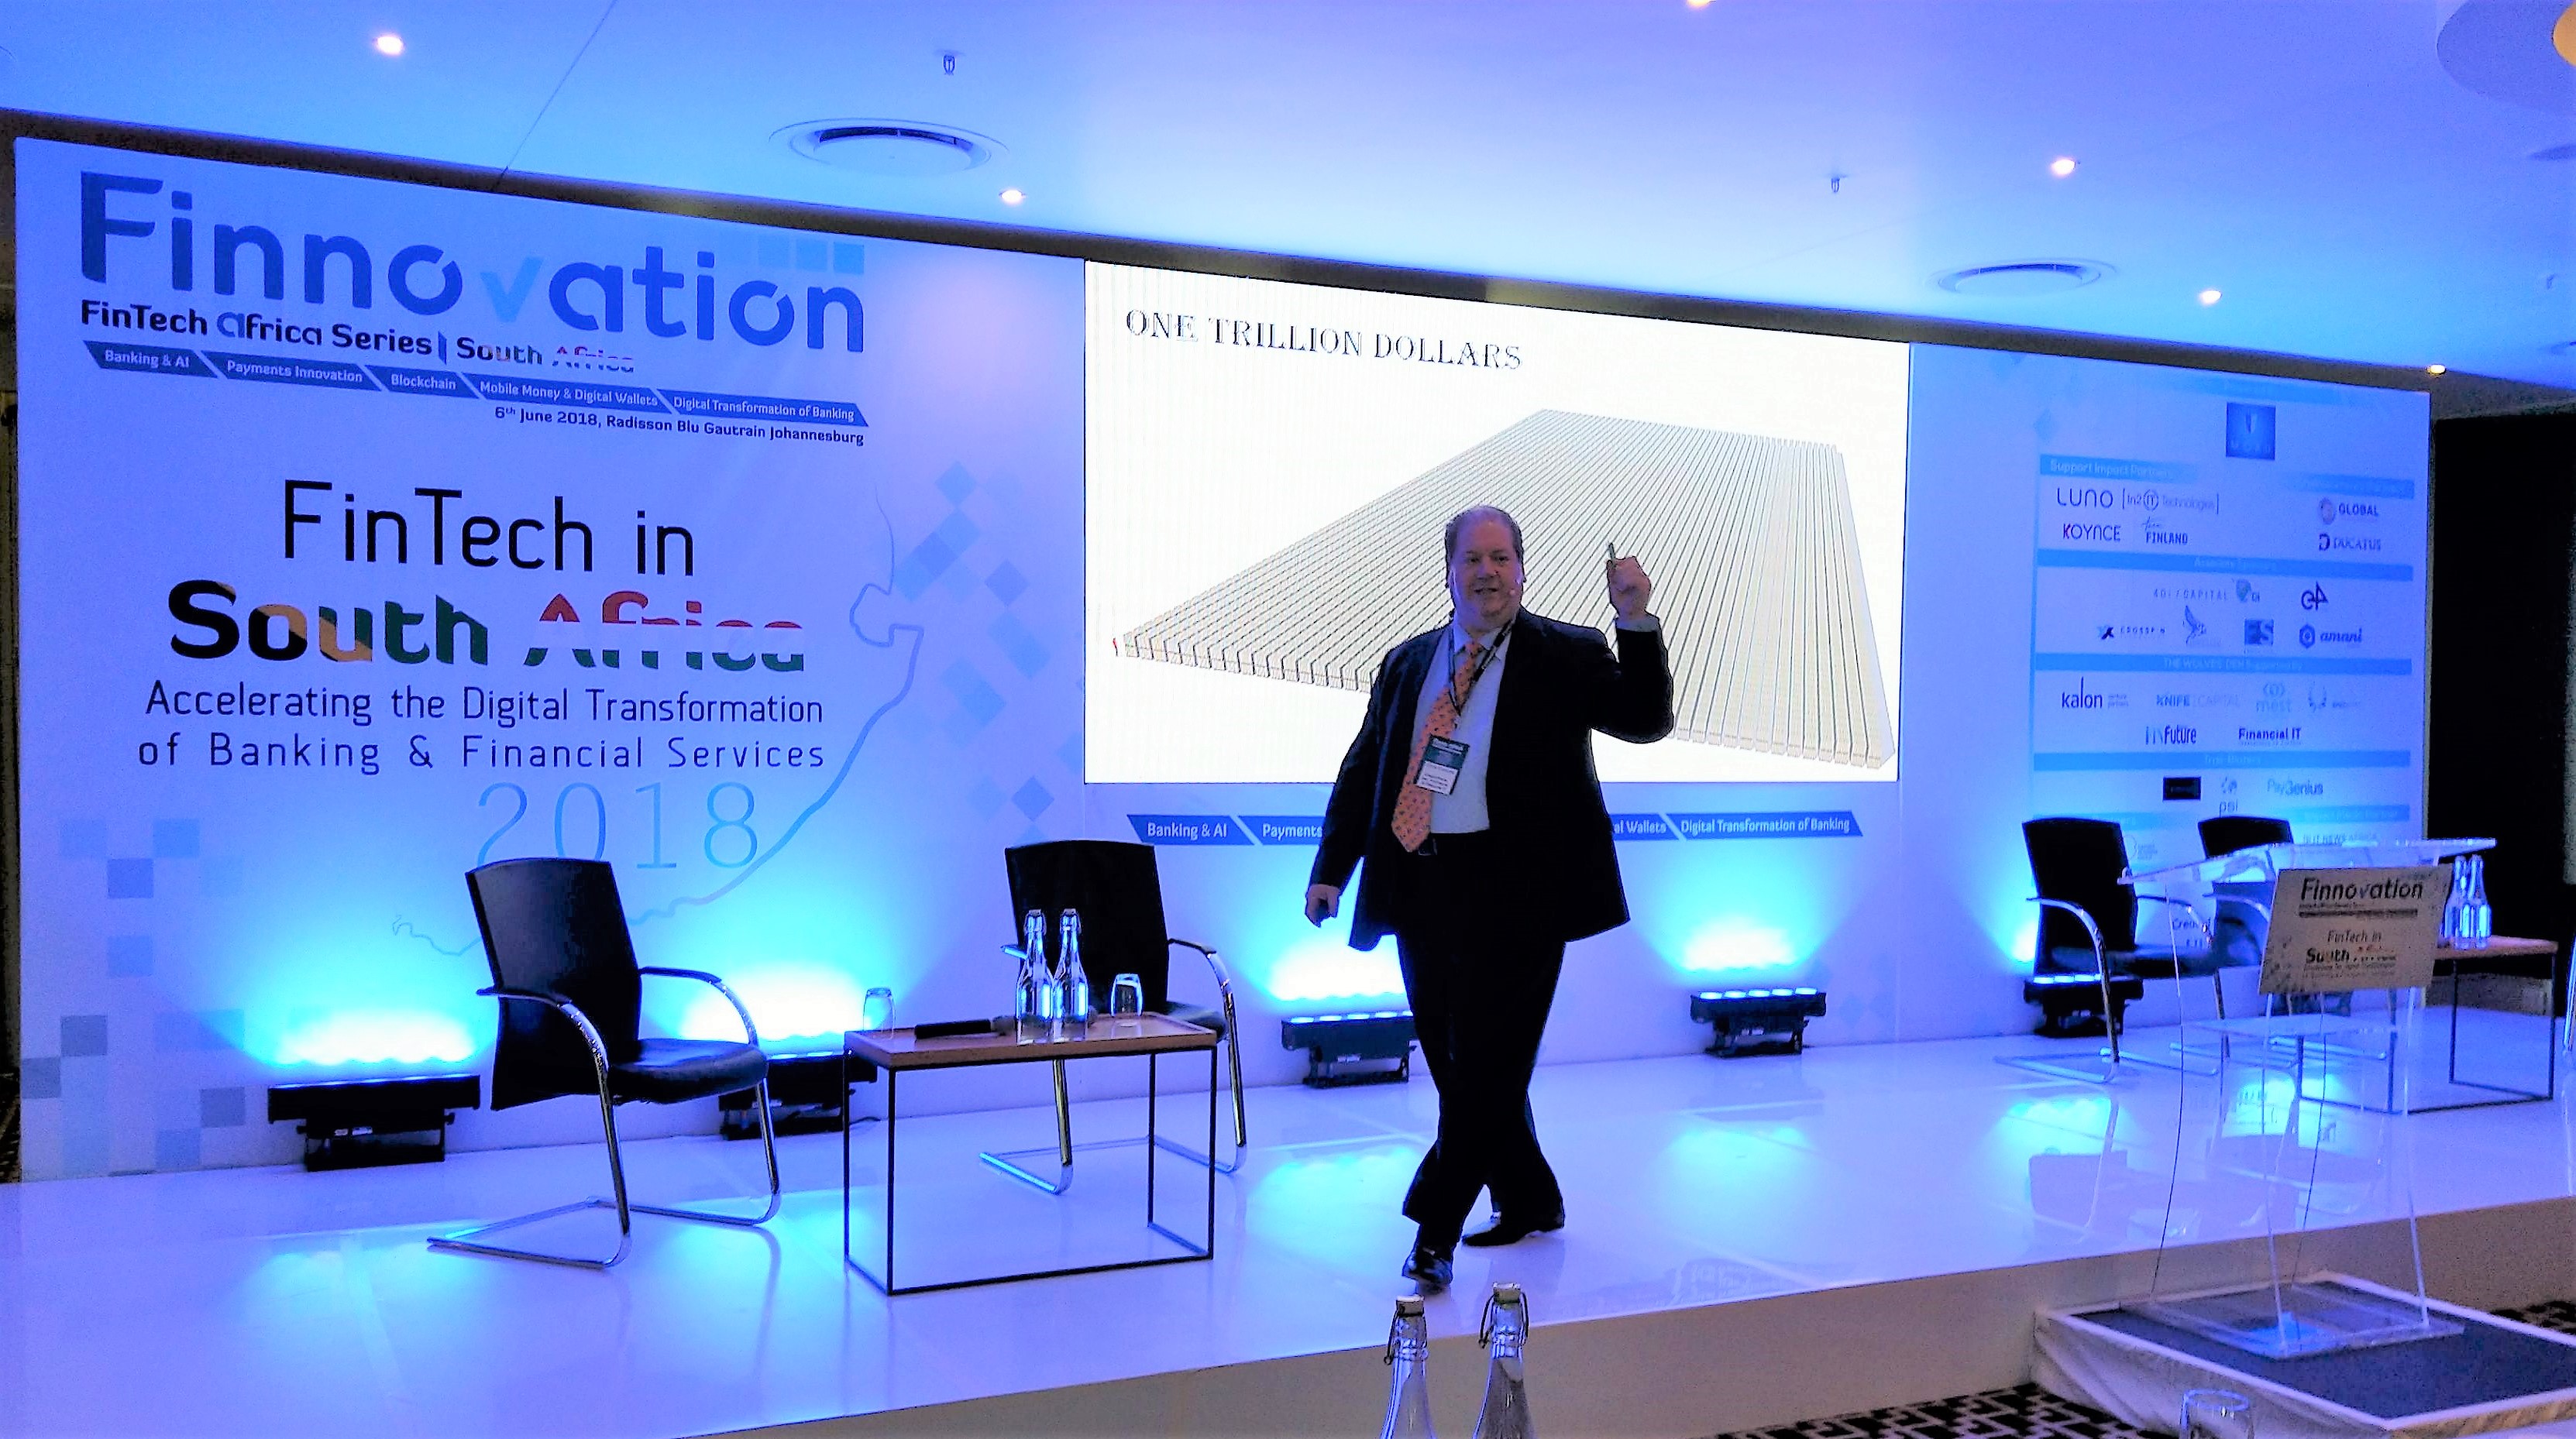
Finnovation South Africa 2018 opened today at the Radisson Blu Gautrain, Johannesburg, where more than 200 international Fintech experts, African digital pioneers, investors, policymakers, entrepreneurs and leading bankers gathered to harness the Fintech revolution. The high-profile event also explored how the major banks and financial institutions in South Africa and across the continent are addressing the digital transformation of financial services; and how their own digital innovations are being shaped and accelerated as a result of the gathering momentum of Fintech disruptors.
The impact of Blockchain, Digital Wallets, Cryptocurrency, ICOs, Open Banking, Mobile Money and Payments innovation are radically transforming the financial services landscape as Fintech disruptors intensify the challenge to incumbent banks in Africa and kickstart new opportunities. The unique environment for financial services in Africa is fertile ground for innovative Fintech players who are capitalizing on the opportunities to disrupt or leapfrog established business models to make financial services more affordable, accessible and profitable across the continent.
Finnovation South Africa 2018 was delighted to welcome a stellar list of keynote speakers, including Nick Ogden, Executive Chairman of ClearBank; Assel Zhanassova, Chief Digital Officer of Astana International Financial Center (AIFC); Nvalaye Kourouma, Chief Digital and Innovation Officer, ROA of Barclays Africa Group Limited; David Gyori, CEO of Banking Reports and Founding Member of the World FinTech Association; Chris Principe, CEO of Chain2Trade, Inc. and Publisher of FinFuture and Financial IT; and Paul Mitchell, Fintech and Blockchain Lead of PwC South Africa. This powerful opening keynote session focused on collaboration as a key catalyst for success in the digital transformation of financial services and how better aligning the role of Government Policymakers, Incumbent Banks, Fintech Innovators, Investors, Multilateral Agencies and MNOs will drive a positive Eco-System for FinTech in Africa.
From the perspective of a leading strategist on digital financial services, Paul Mitchell, Fintech and Blockchain Lead of PwC South Africa, highlighted that “South African financial services players, old and new, are uniquely positioned on a high growth continent to seize the opportunities to create innovative solutions and harness the impact of Fintech in Africa, which could well make a more significant contribution and impact than what we are currently seeing in the US and Europe. Customers' behaviour, and their expectations around how financial services companies traditionally interact with them, is changing rapidly. Fintech is accelerating these changes and the established players who recognise this are having to learn fast. This is leading to a reassessment of many elements of the customer experience and engagement process that will play out over the next few years. Finnovation South Africa 2018 provided a platform to engage with Fintech pioneers and thought leaders to address the most pressing questions for the digital transformation of financial services in South Africa.”
Another major highlight of Finnovation South Africa 2018 was the Leader’s Dialogue Live! informal conversational session with an international Fintech pioneer, which presented a unique opportunity to gain a fresh perspective and first-hand insights from a leading innovator. The live interview session featured renowned industry leader Nick Ogden, Executive Chairman of ClearBank, who stressed the innovative potential of fintech in Africa: “The Financial Technology market is accelerating groundbreaking innovation and transforming the financial solutions landscape across the continent. We firmly believe that the rapid growth in the sector of fintech is providing a platform to enable payments, wallets and increase access, helping the drive to digital banking
services.” This highly interactive session was moderated by well-known media personality, Abe Wakama, CEO of IT News Africa.
Addressing new innovations and opportunities in the ICO market at Finnovation South Africa, Juan Engelbrecht, CEO of MOBU, stressed that: “as the cryptocurrency market evolves, the global adoption of ICO fundraising structures has led to an explosion of new capital formation that has outpaced both the seed and venture capital investment markets. The 86 ICOs that were launched during the first term of 2018 were able to raise a mammoth US$ 3,4 billion in total. The total costs of launching successful ICOs are a lot more cost effective in raising funds than IPOs. However, approximately 98% of these ICOs launched utility tokens. The securities market is a multi-trillion-dollar arena which remains virtually untouched in the blockchain space. We know that a security token start-up can be a legal, technical and regulatory nightmare. MOBU is a decentralized organized all-in-one platform that facilitates the release of validated security tokens, offering a complete blockchain solution by bypassing barriers and introducing a simple marketplace for security issuances and secondary trading. MOBU offers KYC, AML and SEC approval, escrow (safe-keeping proceeds of ICO funds), bank support to investors when fiat is converted to crypto and facilitates all other processes needed to raise funds. MOBU creates a network of confidence and trust that will boost economic and operational efficiency and we were delighted to share our insights at Finnovation South Africa 2018 by engaging with Fintech pioneers and leaders to address the digital transformation of financial services across the world and in South Africa.”
In-depth sessions continued throughout the day featuring bankers and FinTech pioneers deliberating on key issues such as Blockchain – from Hype to Reality in Africa; Banking & AI; and the Cryptocurrency Revolution; as well as further conversational sessions including Founders’ Painpoints and Start-up Success Stories. High-profile speakers included Ned Phillips, Founder and CEO of Bambu; Jane Zhang, Founder & CEO at Shell Pay; Camilo Ramada, Advisor at Business Finland Southern Africa; and Warren Hero, Chief Technology Officer of Microsoft.
The day concluded with the much-anticipated Wolves’ Den session, which again lived up to its billing as a powerful and often ruthless session that enabled innovative Fintech start-ups and trail-blazers to real-time test the positive impact of their solutions with a panel representing savvy Investors/Venture Capitalists and seasoned African Fintech Pioneers. FinTech trail-blazers including PSI, Pay Genius, and Brown Sense all made their respective pitches while the “Wolves" asked the tough questions and provided the illuminating insights during a dynamic closing session to the event.
Finnovation South Africa 2018 is part of the FinTech Africa Series which regularly gathers leading stakeholders and influencers in the African FinTech ecosystem, from start-ups to banking powerhouses, across the key markets of Africa and internationally.
Ethico Live Limited UK is an international trade & investment nexus that focuses on the digital transformation of financial services and the role that Fintech is playing in driving positive and profitable change through blockchain, AI, mobile money, finclusion, ethical finance/Islamic banking, payments, and data driven innovations. We support our clients who are transforming the global financial markets through our high-profile engagement platforms that connect investors, government policymakers, bankers and game-changing start-ups from across the Middle East and Asia - with a special focus on the exciting high-growth markets of Africa.
For further details, please contact:
Sanay Lalwani, Media & Marketing Lead: Finnovation at Ethico Live:
sanaylalwani@ethicolive.com www.finnovationworld.com
Contact No - +91 90245 26133, +91 124 418 2794/5
- 06:00 am
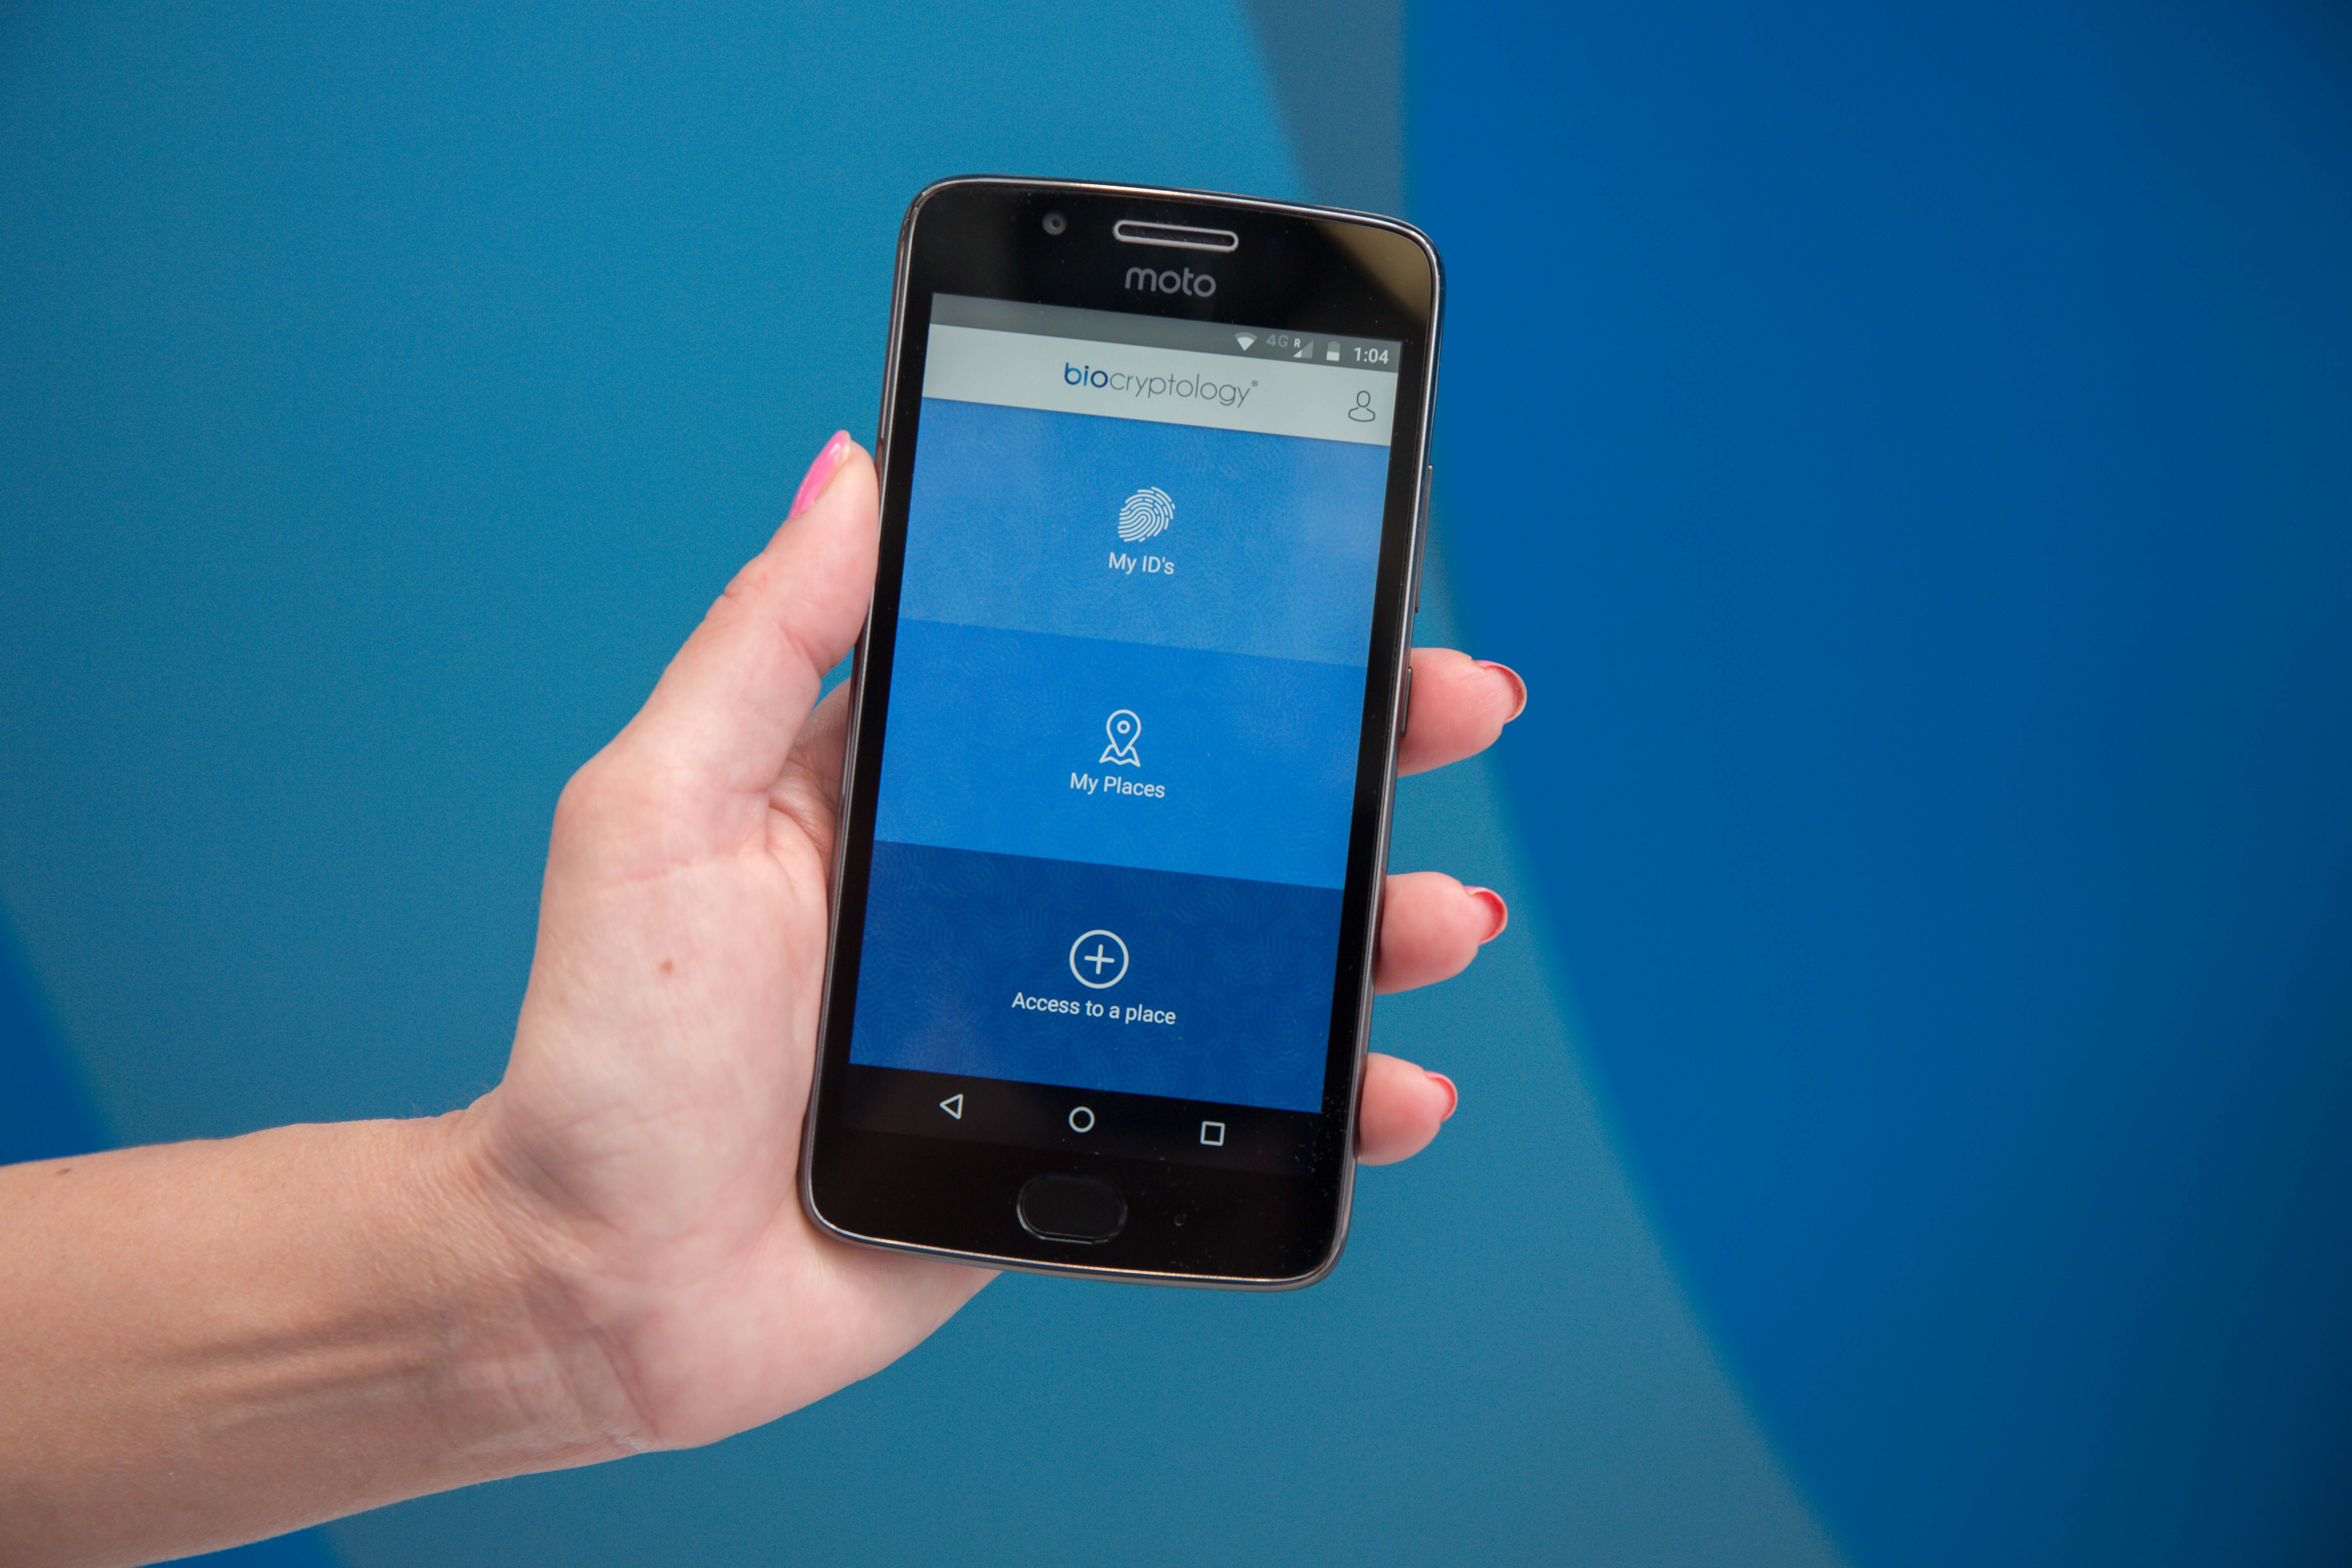
Biocryptology, a European biometric technology company, presented the identification platform that it has created to offer security, privacy, and convenience to companies, users, and public administrations, in Amsterdam at the Money 2020 forum. The platform's technology is based on the biometric identification of the users, thus avoiding the questionable use of passwords.
The new platform aspires to become the worldwide standard for online and physical identification by 2025. Ted Oorbals, the company's CEO, said "We're very proud to have created a technological platform for complete, secure access that also eliminates the need for passwords and user names".
BIOCRYPTOLOGY, absolute control over your identity
Biocryptology is a universal identification platform that allows its users to identify themselves unequivocally, both online (mobile and desktop devices) as well as in physical or in-person settings, using biometric data. To obtain the biometric data, Biocryptology uses one of the user's devices to ensure their identification. The solution currently has an app for mobiles with biometric sensors (fingerprint sensor and face ID) and it is already operational for all types of environments. Both the app and the hardware, produced by Foxconn European Manufacturing Services (Czech Republic), were developed in Madrid by an international team of experts.
To create a profile, users download the app on their phones and register with an email, a phone number, and their biometric data (fingerprint or Face ID). After completing this simple process, the user can access both online and physical environments using the app and their biometric data. Biocryptology encrypts and stores the user data with the highest level of security in different locations, so that if someone managed to access and decrypt the data, the information would be useless.
After several periods of testing in different settings, such as financial transactions or access permissions, 4 levels were established for platform users depending on their needs:
LEVEL 1 - Access to physical and online locations controlled by the user, such as home, car, personal email, and websites, among others.
LEVEL 2 - Access to closed environments, online platforms and physical spaces controlled by another company, such as offices or gymnasiums.
LEVEL 3 - Access to online banking, online betting, etc. Identity is verified by a qualified third party.
LEVEL 4 - Access to official services or premises and procedures for legal purposes. Identity validation by an official body, such as the police.
Identity theft, a growing problem in society 4.0
Identity fraud and theft are still considered to be mainly a financial problem, a problem that cost banks a total of six billion dollars in 2016. But the problem is much larger and it destroys the lives of many victims every day.
UK
According to the Annual Fraud Indicator Report from credit agency Experian, the annual cost of fraud in the UK is £190 billion, equal to nearly £7,200 per household, according to a new research study. Its latest report issued in November 2017 reveals the staggering prevalence of fraud, which is now the UK’s most common criminal offence.
‘Put into context, the scale of the problem is such that the cost of fraud to the UK is greater than the Gross Domestic product of 148 out of 191 countries.’
USA
According to the United States Department of Justice, more than 17 million people in the US are the victims of some type of identity theft each year. This includes activities such as fraudulent credit card transactions or the use of personal information to access accounts without proper authorization. According to Google, hackers manage to hijack almost 250,000 web session starts every week.
SPAIN
According to the most recent data from the European Office of Statistics (Eurostat), Spain is the county in the European Union with the most recorded victims of identity theft, accounting for 7% of internet users. In addition, 4% have suffered financial losses in the last 12 months as a result of fraudulent use of their credit card information or fraudulently obtaining their bank information (phishing).
For the first time, institutions have access to a service that eliminates all conceivable types of identity fraud: the Biocryptology security platform.
ANTONIO BANDERAS
The well-known actor Antonio Banderas, in addition to being one of the first investors, is also Biocryptology's ambassador."Of course, if you are famous, your identity is always being examined under a microscope, and it is often twisted or even used improperly. We all know that many of the accounts of celebrities on Twitter, Linkedin, or other social networks are not actually owned by them, or they are not under the control of the right person, and they are often used incorrectly. This is just one, and perhaps the most commonplace example of the importance of our identities. Biocryptology's calling is to eliminate identity fraud on social networks, but also in more critical areas such financial transactions", said the artist, who was recently named Biocryptology's Global Ambassador.
Biocryptology wants to encourage consumers to actively protect their own identities and eliminate user names and passwords. The company also feels that it has the responsibility to provide effective assistance to the victims of identity fraud and theft. For this reason, it will offer support to valuable causes in all countries that also help these victims, not just economically, but also by providing its experience and legal assistance.
- 05:00 am

On May 17, the capital of the Czech Republic hosted the fourth annual event dedicated to blockchain, cryptocurrencies, and ICO – Blockchain & Bitcoin Conference Prague. Special speakers were representatives of world-famous companies (for instance, IBM and PwC), and distinguished international crypto experts.
Conference presentations
Data privacy, protection, and storage
The Technical Vice President of Innovation and New Technologies for IBM Cloud René Bostic focused her presentation on the analysis of modern blockchain trends. The speaker believes there are three most important conditions for successful blockchain implementation in business: privacy, cyber security, and safe data storage. Besides, René Bostic thinks that business collaboration in the field of blockchain should rely on the readiness to develop.
Cryptocurrency under the regulator’s watchful eye
Leader at PwC Legal Switzerland Dr. Günther Dobrauz-Saldapenna told about the increasing attention to cryptocurrencies from the side of national financial regulators. He also reported that every token sale project should be evaluated independently, as none of the international financial organizations provides an official classification for tokens or ICO.
Blockchain in healthcare and energetics
Speaker that consults the European Parliament on capital markets and fintech regulation expressed the view of blockchain shared by the European public officials. He believes that primarily blockchain will be integrated in energetics, healthcare, logistics, education, and creative industry. But a serious work on the cyber protection of such blockchain solutions should come first.
Artificial intelligence on blockchain
Report on open source artificial intelligence based on blockchain was presented by one of 50 most inspiring Scandinavian women engaged in high tech (according to the pan-European program Inspiring Fifty) Anita Schjøll Brede. She informed that the artificial intelligence technology integrated in blockchain would reduce energy consumption and improve CPU and core memory data processing.
Exhibition area
Attendees of Blockchain & Bitcoin Conference Prague had access to the exhibition area that gathered representatives of the global blockchain industry. Cleverance presented software for financial and telecommunication companies. KompiTech displayed blockchain solutions for supply chain management. BubbleTone unveiled an application for international calls without the need for intermediary services. Inno3D showcased mining hardware. NAFEN presented nano materials used in different business areas.
Organizer and sponsors
The blockchain conference was held by the international company Smile-Expo that established the network of Blockchain World Events. The organizer would like to thank the sponsors of the event: Money Maker Group, KompiTech, Cleverlance, HiDone, and CoinTraffic.
The hype before the Blockchain & Bitcoin Conference Prague and the packed conference hall have once again proven the relevance of blockchain events in Europe. It means that the next year Smile-Expo will return to Prague for the fifth time!
Subscribe to the news not to miss the announcements of new blockchain events.
- 02:00 am

A new report from Skytap and 451 Research shows that despite appetite to modernise, 74 percent of tech leaders report more than half of applications remain on-premises, creating internal skills challenges
Skytap, a global cloud provider, today announced the results of a commissioned study on the state of enterprise IT modernisation and the conflict between cloud strategies and datacentre realities. Conducted by 451 Research, the “Realities of enterprise modernisation: Urgency mounts for a clear path to cloud” surveyed 450 C-level and Director-level technology leaders in the UK, US and Canada.
The report finds that although enterprises have a clear appetite to move to the cloud, businesses are creating additional technical complexity and recruitment challenges in the process. Businesses know they need to modernise if they are going to remain competitive and UK IT leaders recognise the critical role of the cloud in doing this. However, a lack of skills, combined with internal resistance to change, is holding UK organisations back.
Key findings include:
· The enterprise runs in the datacentre:
o The majority of technology leaders report managing more than 100 applications, with 74 percent stating at least half of these applications are on-premises.
o Another 71 percent of respondents see more than half their on-premises applications as mission-critical to their business.
· Cloud use for application modernisation is reaching a tipping point:
o 67 percent of respondents plan to migrate or modernise at least half their on-premises applications in the next 12-24 months. As a result of this process, nearly two-thirds of respondents expect better customer responsiveness and to be more competitive.
o However, at least half of the respondents cite common, core business applications including CRM, ERP, and Data Analytics as least-suited for hyper-scale clouds, and report lack of skills to manage these applications and an inability to deliver new features as current challenges in their operations.
· But enterprises are choosing the path of most resistance, unintentionally creating a self-induced cloud skills gap:
o The two top-ranked strategies that respondents report taking when they migrate traditional applications to the cloud are the strategies that require the highest degree of IT skills -- 49 percent cited refactoring or rewriting applications as their primary modernisation strategy.
o Embarking on the most arduous path to cloud may be one reason why 55 percent of respondents cited “people capable of migrating existing applications to the cloud” as their most critical recruiting need.
o In the UK, IT leaders are struggling to galvanise enthusiasm for driving change:
§ 54 percent cited “internal resistance to change” as a top three-factor holding them back from modernisation
§ 82 percent said they felt some apprehension embracing a cloud-first strategy and learning new skills
Skytap and 451’s new study found that the reality of enterprise IT modernisation is a myriad of difficult choices exacerbated by urgent skills needs and the significant challenges created by traditional but mission-critical applications left in the datacentre. The research found technology leaders varied widely in cloud and application deployment models and that while the majority want to migrate most of their existing applications to the cloud in two years or less, they are in desperate need of the skills to do so.
“Enterprises are motivated to leverage cloud to modernise, and clearly understand the benefits,” said Jay Lyman, Senior Analyst, 451 Research. “However, the sheer mass and complexity of on-premises application portfolios, combined with a propensity to choose the most arduous path to cloud, is creating a painful skills challenge that may require a more patient, progressive approach to find relief.”
These new findings underscore the reality that enterprises need a clearer, more iterative path toward modernisation, and examines the cloud technology, people, and process challenges to digital business success.
“Cloud is an often over-hyped and simplified, while modernisation and digital transformation can be even vaguer,” said Brad Schick, CTO, Skytap. “Our study cuts through to clarify the fact that technological change is hard and is being further aggravated by cookie-cutter approaches to cloud adoption. We want to be part of a conversation that gives enterprises clear choices to manage change and progressively modernise without burning everything to the ground.”
The study found respondents in the UK, compared with the US and Canada, were experiencing even more acute pain in their modernisation initiatives. More than two-thirds of UK respondents intend to migrate existing applications to the cloud in the next 12-24 months, with business and digital transformation being primary motivators for their change. However, more than half cite “internal resistance to change” as a top three-factor holding them back from modernisation, and more than 80 percent noted IT teams would be “somewhat apprehensive” about a cloud-first strategy.
Further complicating the situation, UK technology leaders currently view technological change as having a negative impact through new skills shortages and cost challenges, and more than half are managing 300 or more applications, most of which are both on-premises and mission-critical.
The study’s findings underscore the fact that, like their US counterparts, UK technology leaders need a better path to modernisation that begins where they are today, then progresses forward to more modern infrastructure, processes, and organisational structure at a pace their business can handle.
“Our survey shows UK organisations are simply not realising the benefits of digital transformation and risk falling behind,” said Chris Griggs, VP and EMEA GM. “Rather than finding new revenue streams or helping them connect with customers in new ways, technology change is giving UK IT leaders a cost and skills headache. UK enterprises need a more holistic modernisation strategy or face even greater risks from rapid technological change.”








