
Published
- 02:00 am
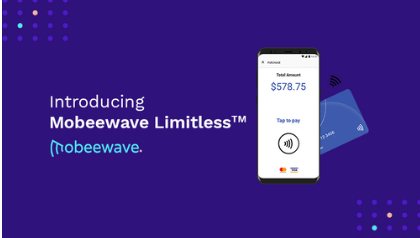
Mobeewave, a pioneer in contactless payment acceptance, is launching a suite of innovative new features that remove current contactless payment limits for merchants and consumers around the world using its tap-to-phone technology.
The company develops solutions that enable businesses to accept contactless payments by tapping a card or a digital wallet onto the back of an NFC-enabled mobile device – without the need for dongles, card readers or additional hardware.
Contactless payments are currently capped at around $100 in Canada and Australia (depending on the issuer), where contactless penetration is at over 80%. In Europe, contactless limits are usually lower and vary by market. To add complexity, the revised Payment Service Directive (PSD2) requires banks to implement a PIN request from the consumer after every five contactless payments, or once payments have totaled €150 EUR/£135.
For tap-to-phone payments, entering a PIN on the screen of a merchant’s mobile device presents a number of challenges. These include requiring additional hardware for PIN entry, as well as the fact that today, PIN for contactless is not supported in some countries such as Canada, France and the UK (due to the PIN technology used in those countries). PIN entry also presents additional user experience and security challenges when entering a personal PIN number on someone else’s device.
Mobeewave Limitless™ is a full suite of high value transaction contactless tap-to-phone features that cater to the varied authentication challenges, regulatory environments and Cardholder Verification Method (CVM) requirements across North America, Europe and APAC. The solution, which has been successfully tested, comes in several flavors, including a secure PIN-based solution and one that leverages a user’s CVV number to authenticate their payment.
However, the most innovative solution in the Mobeewave Limitless™ portfolio leverages 3D Secure 2.0, a newly released security standard that is used for online card not present transactions, effectively removing the need for a PIN to be used to authenticate the cardholder during a tap-to-phone payment. Combined with a card tap, Mobeewave’s 3DS solution combines Authorization with Authentication methods without the need for PIN, enabling a high value contactless transaction by initiating a 3DS check, which provides an authentication request to the consumer on their own device. This solution also shifts the chargeback and fraud liability from the merchant to the card issuer.
“PIN entry on a consumer off the shelf (COTS) device can present a number of issues when needing to make a high value purchase,” explained Eran Hollander, EVP Product at Mobeewave. Our Mobeewave Limitless™ solution eliminates all of these while shifting the liability of the transaction away from the merchant. With Mobeewave Limitless™, we combine risk mitigation best practices of both card not present and card present technologies. We are also in discussion with payment schemes to look at discount fees based on the solution at hand, rather than the technology rail it rides on, similar to how mobile transaction fees have evolved.”
“The use of contactless payments continues to grow around the world, and with the current health and security challenges that both merchants and consumers are facing, it’s become more critical than ever to accommodate high value contactless transactions,” added Maxime de Nanclas, co-founder and co-CEO at Mobeewave. “We’re the first to market a solution that uses what we believe to be the CVM process of the future, 3DS, via mobile devices and AI technology, to enable a fully digital seamless experience for both consumers and merchants. We’re excited to see how the pilots run and to be able to roll-out Mobeewave Limitless™ over the next few weeks.”
The Mobeewave Limitless™ 3DS solution, which is patent pending, has been approved by the main payment schemes and will be rolled out to merchants in April 2020, including to those using the Samsung POS app, which is powered by Mobeewave
- 06:00 am
British Business Investments, a commercial subsidiary of the British Business Bank, has announced a new £15m commitment to Par Equity as the latest partner in its Regional Angels Programme.
The funds from British Business Investments will be invested by Par Equity alongside the Par EIS Fund and the Par Investor Network to deliver over £75m of new funding for scale-up businesses primarily in the North of England, Scotland and Northern Ireland.
The £15m commitment from the Regional Angels Programme will help to drive further investment into promising scale-up businesses in these parts of the UK. The Programme will also help with Par Equity’s follow-on investment activity, ensuring that the portfolio receives the capital it needs to reach critical milestones.
The Par Investor Network, with nearly 200 members, invests alongside the Par EIS Fund to create a distinct, operationally focused investment model where professional investors and experienced business angels add value to businesses throughout the investment lifecycle.
The announcement comes as Par Equity completes a £1.6m investment into EC-OG, drawing on the pledged capital from the Regional Angels Programme for the first time. EC-OG has launched Halo, a subsea power hub, providing efficient, autonomous energy management for subsea applications. The company leverages its proprietary technology with deep sector expertise to service customers at a fraction of the cost of incumbent subsea power solutions. The investment will support a scale-up phase for the business, creating up to 40 jobs in Aberdeen over the coming 12 months.
Catherine Lewis La Torre, CEO of British Business Investments, said: “Angel investors play a vital role in the economy, bringing patient capital, business experience and skills to support the growth of smaller businesses. Our Regional Angels Programme is designed to address regional imbalances in the availability of angel finance by increasing the capital available to smaller, high growth potential, businesses through angel networks.”
Mark Barry, Senior Investment Manager, British Business Investments, said: “This £15m commitment from British Business Investments will enable Par Equity to increase its support for smaller businesses in the North of England, Scotland and Northern Ireland at a time when the business know-how and financial support that angel investors can deliver is needed more than ever.”
Paul Munn, Managing Partner of Par Equity, said: “Par Equity’s investment model, combining our EIS Fund with experienced business angel investors and co-investment capital, is a powerful recipe for providing patient capital. We already benefit from a flow of high quality investment opportunities and this commitment from the Regional Angels Programme will bring us increased financial firepower. It will help us enhance our growing reputation as the investment partner of choice for the best young companies in the regions and help them to attract the talent they need to realise their potential.
“At Par Equity we have long recognised and supported the opportunities offered by entrepreneurs and their companies based in the North. That philosophy is now in line with government thinking and this funding will enable us to leverage our network to find the best young companies to invest in, delivering value to them and the whole economy.”
Since it was founded in 2008, Par Equity has invested more than £70m in 57 companies and the portfolio has attracted over £110m of further investment from third party investors.
EC-OG joins Par’s portfolio of emerging stars such as: Current Health, a leading Edinburgh-based remote-patient monitoring platform; BrainwaveBank, the Belfast-based creator of a wearable headset device for EEG brain scanning that measures the mechanisms underpinning neurological disorders and therapies; and NPT, a Middlesbrough-based, cleantech company with a patented process to convert non-food plant residue into biofuels and chemicals. Other successful investments include deltaDNA, an Edinburgh-based analytics company, sold to Unity Technologies in 2019, ICS Learn, a Glasgow based distance learning business, bought by Primary Capital in 2018, and PathXL, a Belfast-based digital pathology solution, acquired by Phillips Healthcare in 2016.
The Regional Angels Programme helps reduce regional imbalances in access to early stage equity finance for smaller businesses across the UK, because it plays an important role in funding businesses with growth ambitions. The programme aims to address this issue by increasing the availability, supply and awareness of angel and other early-stage equity investments across the country, particularly in areas where this type of finance is less readily available.
The Regional Angels Programme works by committing funds for investment alongside business angels and other early stage equity investors, acting as a catalyst to bring longer-term capital to smaller businesses with growth ambitions. Launched in 2018, it forms part of the Government’s response to the Patient Capital Review.
Like all British Business Investments programmes, the new programme expects to generate a market rate of return on its investments and will be investing on a commercial basis.
- 08:00 am
Abu Dhabi Islamic Bank (ADIB), a leading Islamic financial institution, has become the first Islamic bank to successfully execute trade finance distribution transactions using Blockchain technology. The cross-border transactions, which were completed with multiple based banks, were made possible through ADIB's partnership with TradeAssets, a trade finance e-marketplace powered by Blockchain technology to help digitize the traditional processes of origination and distribution of trade assets. For the past year, ADIB's collaboration with TradeAssets has enabled it to automate trade finance transactions and conclude transactions successfully with banking counterparts in emerging markets.
Commenting on the milestone, Haytham Elmaayergi, Global Head of Transaction Banking at ADIB, said: "The completion of the first trade distribution transaction using Blockchain by an Islamic bank shows that ADIB is at the cutting-edge of global transaction banking. As the only Islamic bank providing end-to-end Sharia'a-compliant trade financing through digital channels, ADIB is committed to expanding its digital footprint in trade financing and distribution, enhancing the efficiency and productivity of businesses across the region and globally."
ADIB values the importance of incorporating emerging technologies and forming strategic partnerships in a rapidly evolving business climate. This commitment is represented in the bank's collaboration with TradeAssets, an e-marketplace that complements ADIB's diversified digital cash, trade and foreign exchange offerings, available to businesses through its flagship ADIB Direct platform.
Aimed at businesses of all sizes, ADIB Direct improves companies' ability to manage their finances locally and internationally. These features include customisable dashboards, cashflow forecasting and online trade issuance and financing which are accessible across all devices including a mobile app.
ADIB has received numerous awards for its digital cash management and trade finance offerings in recent months including 'Best Islamic Financier' at the International Trade Finance Awards 2019 and 'Best Islamic Trade Finance Provider' and 'Best Online Cash Management in the Middle East' and 'Best Islamic Digital Bank' by Global Finance. The bank was also named 'World's Best Islamic Bank' by the FT's The Banker Magazine, 'Best Premium Banking Service in the UAE' from Banker Middle East, and 'Best Islamic Bank' at the EMEA Banking Awards.
- 02:00 am

Kivra provides a digital mailbox to more than 3.7 million users in Sweden. Through the Kivra app, users can receive and process all their bills and important mail in one place, making life simpler while also sparing the environment. With over 2.5 million invoices to be settled every month, Kivra was looking for the most cost-effective and friction-free way to enable these payments, and now they’re partnering with Tink to make it easier to settle invoices with just a few clicks.
Settling the tab, without the headache
Tink’s payment solution, building on PSD2, brings direct bank payments into existing digital customer journeys. How does it work? Kivra’s customers simply click to pay directly on the digital invoice, select the bank account they want to pay from and approve the payment – all within the Kivra app.
And for Kivra this means that their users make their payments directly to the merchant or service provider, without Kivra needing to touch the money in between. Less hassle for both Kivra and their users, with more invoices getting paid on time.
Reducing the complexity in payments
The Tink platform is connected to all of the major European banks, giving customers the opportunity to unlock the many benefits that open banking can bring.
Tink VP of Payments, Tomas Prochazka adds, ‘With Payment initiation our goal is a simple, future-proof, plug-and-play solution that enables our customers to keep the payment experience in their world and unlock new digital sales and onboarding opportunities. You could create these connections to all the banks and different markets yourself, but the complexity and years of effort you’d have to put in is too much. Instead, we reduce this complexity by offering one API that supports and maintains all banks and markets – regardless of how each bank handles payments and transactions.’
Tink’s payment initiation is already available in select markets. You can learn more about it on our website, or even try out a demo.
- 06:00 am

TruNarrative, the global RegTech company has announced a new partnership with AccountScore, to integrate Open Banking connectors into the TruNarrative platform. Enabling Risk & Compliance teams to integrate affordability scores to aid onboarding and monitoring of customers.
The TruNarrative platform delivers financial crime detection, customer onboarding and transaction monitoring to Financial services, e-commerce businesses and gambling operators. Using their unique customisable decision engine and their App Store of over 50 third-party data providers and service integrations, their unified platform sits at the heart of many business’ customer acquisition, monitoring and compliance strategies.
AccountScore currently provides their Open Banking APIs and platform to Financial Services companies, tenant reference agencies and telecommunications companies, allowing them to verify information such as Customer Salary Amount, Affordability and Identity, a process that has historically involved the submission of paper documents and manual validity checks.
Importantly, AccountScore also provide a consumer facing portal allowing individuals to maintain control of the information they share with organisations.
Open Banking data is permissioned access to consumer or business banking data for the purposes of risk assessment, compliance and fraud detection. This helps regulated businesses such as lenders or gaming operators comply with their obligations for onboarding and transacting with their customers.
The partnership means TruNarrative customers have access to the information they need to make affordability decisions, in real time via the TruNarrative API.
Checking against Open Banking data can mean the difference between over extending a loan or allowing credit correctly to the underbanked. Affordability scores are also a key requirement enforced by the UK Gambling commission onto gaming companies to ensure a duty of care to their customers.
AccountScore’s Open Banking data will sit within TruNarrative’s AI driven platform and allow enrichment through the various third-party verification data sources in the TruNarrative App Store, providing firms with a more complete customer view facilitating both automated and manual decisions.
The TruNarrative decisioning and workflow platform allows granular-level decisioning across Credit Reference Agency, biometric, address, document verification and now Open Banking data.
Constantly changing regulatory environments and market conditions, such as those imposed by the current COVID-19 emergency, mean businesses need instant access to valuable data, and importantly, the ability to make quick changes to onboarding and monitoring processes.
Using AccountScore’s Open Banking data through TruNarrative will facilitate a low-friction journey for the customer, increased visibility and reduced operational cost for organisations.
Adam Doyle – Head of Gaming TruNarrative says;
“This is a relationship that I am truly excited about. As regulatory requirements shift increasingly towards the inclusion of affordability scoring, this partnership provides businesses with the much needed ability to monitor and protect customers throughout their entire lifecycle, whilst minimising impact on the customer experience.
And importantly, in this unprecedented global situation, ensuring players aren’t stretching themselves in testing times is essential for continuing to provide a safe environment for users of online services.”
Emma Steeley – CEO of AccountScore
“We are proud to be joining forces with TruNarrative in order to enable them to deliver cutting-edge Open Banking solutions to their clients. From income verification and affordability, to source of funds and identity verification, our partnership delivers a solution that provides multiple sectors the opportunity to take full advantage of the UK’s Open Banking framework coupled with our market leading analytics.”
John Lord CEO and Founder of TruNarrative– “ The partnership with AccountScore means we can deliver Open Banking data to our customers, further enriching their ability to make decisions, mitigating risk to business and reducing customer friction”
- 02:00 am

The nation-wide lockdown in the wake of Covid-19, predictably, has hit the poorest sections of society the hardest, especially migrant workers and the rural population. However, now, through the help of bank mitras and Aadhaar enabled payments, customers can withdraw upto Rs. 10,000 daily simply through the use of their thumb, which is a blessing in rural areas where there is a lack of adequate financial infrastructure. PayNearby, through its 8 lakh network of banking correspondents has been seamlessly facilitating cash withdrawal and transfer in this period - conducting over 8.5 lakh transactions per day.
The ground reality is that rural regions face a severe scarcity of ATMs and POS machines, expired or non-operational debit cards and the population in these areas are less digitally savvy regarding online payments. Only 5% of rural India which is 30k of the 6.5 lakh villages have access to ATMs. Last year, the government declared over 115 million debit cards invalid since they lacked the appropriate chip and PIN mandate. In the wake of this the pandemic lockdown, the owners of these invalid cards are now left in the lurch as they are non-functional. In this case, it was PayNearby that gave people access to financial services through their BC network.
Even as the finance ministry announced ₹1.75 lakh crore will be given to “80 crore poorest Indians” under the Pradhan Mantri Garib Kalyan Yojana (PMGKY) over three months starting April 1, there are several logistical challenges that impede their access to this relief package. Furthermore, there is a lack of awareness by the rural population themselves - 1.25 lakh crore DBT remains unwithdrawn in bank accounts. In such circumstances, it is banking correspondents who are doing the national duty of serving as disbursal points for cash withdrawal - doing over 125 crore worth transactions per day.
PayNearby has been integral in promoting AePS (Aadhar enabled Payment System) in the country. It currently has over 33% market share in AePS, with transactions more than doubling in the last month to almost 6 lakh daily. India’s unique demography is such that even as 1.1 billion people have bank accounts, a large chunk is unable to fill out official documents. Thus, India has greatly benefited from AePS for direct benefit transfer, which aids in seamless DBT deployment.
“We are extremely grateful to the government for establishing the Aadhaar system so successfully within the country. In times like these, the use of biometrics is a great equaliser in terms of financial access, as AePS resolves many operational hurdles, especially in rural areas. Currently, 93% of our retailers are dedicatedly serving in rural regions, with 1 lakh Digital Pradhans doing transactions daily, mindful of careful sanitation and social distancing. We are extremely privileged thatwe could answer to this call of National duty”, remarked Anand Kumar Bajaj, MD & CEO, PayNearby.
During these challenging times too, PayNearby’s platform and their Digital Pradhan retailers have been summoned to serve people at the last mile. Along with their banking partners and NPCI, they have been working tirelessly in severely affected areas where ATMs are non-operational or non-accessible, and even hospitals, police stations and NGOs are availing their services.
- 02:00 am

Curve, the banking platform that consolidates multiple cards and accounts into one smart card and app, has appointed Hannah Nixon to advise on the company’s regulatory activities and relationships.
Hannah has extensive experience in economic regulation and competition matters, working across a range of industries in the public and private sectors. She will help guide Curve’s regulatory strategy and framework focused on the UK and EU as well as advising on a range of regulatory matters important to Curve’s growth.
Hannah was the first CEO of the Payment Systems Regulator, the economic regulator for the UK’s £80tn payments industry and the first regulator of its kind in the world, where she built a high-performing organisation from scratch, driving competition and innovation in payments.
“Hannah’s remarkable experience working with some of the most respected regulatory organisations in the world is a huge asset to the Curve team,” said Shachar Bialick, Curve’s Founder and CEO. Curve is continuously innovating and constantly pushing the boundaries of payments models and for that we needed someone of the highest calibre to guide our regulatory strategy as we scale our operation throughout Europe and the US,” he added.
“I’m delighted to be joining Curve, a brilliantly dynamic and innovative company in a uniquely exciting sector” said Hannah Nixon, commenting on her advisory role at Curve. “The payments sector is flourishing with meaningful innovation that can truly change people’s lives for the better. One of the key roles of the PSR is to open markets and drive innovation. That’s something that I am passionate about and I shall be drawing on my regulatory experience to help Curve navigate through the regulatory landscape as the company continues its rapid growth,” she added.
Prior to joining the PSR, Hannah held several senior positions within regulatory bodies across various industries and is also currently a NED of National Grid Electricity System Operator and the Channel Islands Competition and Regulatory Authority. She was also previously a Senior Partner at Ofgem, the GB gas and electricity regulator.
Hannah is the latest significant appointment for Curve, which recently extended its leadership team with the appointments of Eyal Goldberg as Head of Machine Learning, Joseph-Daniel Millwood as Head of Growth, and Amanda Orson as VP, Head of North America.
- 03:00 am

Funding Circle, the small business loans platform, has today been approved for accreditation by the British Business Bank under the Coronavirus Business Interruption Loan Scheme (CBILS), term loan variant.
Funding Circle expects to open CBILS applications within the next week once it has completed the required legal and operational approvals with the Bank.
Keith Morgan, CEO, British Business Bank, said: “Our accredited lenders have seen an incredible demand for CBILS since the scheme became available. As the first newly accredited marketplace lending platform to be accredited under CBILS, Funding Circle will be able to provide more capacity, more choice and most importantly, vital funding for smaller businesses across the UK. This accreditation continues the British Business Bank’s long-term support for the growth of marketplace lending since its earliest stages.”
More than 80% of the UK’s smaller businesses have a finance relationship with CBILS accredited lenders. The British Business Bank is accelerating the onboarding of new lenders to further extend the scheme’s reach. The Bank continues to review applications from a wide range of lender types – from PRA-regulated banks, to platform lenders, debt funds, invoice finance lenders, asset finance lenders and responsible finance lenders.
Funding Circle is the largest online small business loan provider in the UK and has originated over £6.2 billion of loans to 57,000+ businesses.
- 03:00 am

Sopra Banking Software released on March 31 Cassiopae V4.7, a leasing and lending application, which is part of the company’s Sopra Financing Platform. The company met the ambitious release date announced ten months ago.
The new release, Cassiopae V4.7, includes an enhanced digital portal for dealers and merchants, credit card processing via electronic payment partners, revolving credit for individuals, and improvements in the management of real estate and equipment leasing.
“The delivery of Cassiopae V4.7 is a testament to our commitment to our customers and to the broader market. We thank our clients and teams for their support in meeting this ambitious deadline. We implemented a comprehensive process and delivered a product of uncompromising quality.” Comments Eric Bierry, CEO Deputy at Sopra Banking Software.
Recognized by IBS Intelligence as the world leader in lending systems for three years in row – 2017, 2018, 2019 – Sopra Banking Software continues to invest heavily in its Sopra Financing Platform, which is a global leading solution that provides end-to-end financing solutions for the leasing and lending sector. Sopra Financing Platform combines the strengths of two software solutions: Cassiopae leasing and lending plus Apak wholesale finance.
Sopra Financing Platform can be deployed globally, and more rapidly than ever.
The release of Cassiopae V4.7 is part of the company’s strategic, multi-year roadmap for the specialist finance market. Next steps include further integration between Apak and Cassiopae as well as regular software updates to meet emerging requirements.
- 01:00 am

Messaging apps; speech-based assistants such as Apple’s Siri and Amazon’s Alexa; and chatbots are entering the marketplace in large scale, all with a goal of enhancing everyday life. Businesses are taking notice; leveraging the technology to analyze peoples’ behavior in order to create a more personalized and efficient customer experience.
To help companies deliver a more transformative and differentiated customer experience (CX), CSG® (NASDAQ: CSGS) today announced the availability of its Conversational Artificial Intelligence (AI) solution, a disruptive technology that improves overall CX by enabling companies to rapidly develop, deploy and analyze conversational applications across a variety of communications channels.
Today’s digital world has created a paradigm shift where customers are demanding instant gratification. A primary differentiator for companies will be their ability to deploy conversational platforms that span voice and digital channels to create proactive efficiencies surrounding customer intent. In fact, a recent Capgemini report[1] noted 74 percent of organizations consider conversational assistants as a key enabler of the company’s business and customer engagement strategy.
In response to this market dynamic, CSG has teamed with Artificial Solutions, a leader in advanced intent-based AI, to deliver Conversational AI. This new solution gives companies the ability to communicate internally and externally through applications and web sites that provide human-like natural language via voice, text or gesture inputs, offering a host of benefits, including:
- Reduced costs: CSG Conversational AI helps decrease the burden on customer care agents and the level of interactions needed.
- Proactive customer engagement: Once implemented, the solution identifies trends unique to the business using it and delivers actionable data to enable proactive communications with customers.
- Increased resolution rate: The solution gives the customer the ability to have a conversation across multiple platforms (SMS, voice, text, chat, IVR, smart home devices), reducing the need to be passed to multiple customer care agents and departments.
- Consistent and compliant guidance to customers: The solution also provides consistent and compliant guidance to customers for multiple scenarios, which is critical in many regulated industries such as Finance, HealthCare, and Insurance – whether via an agent, a chat session, or a voice call.
“CSG Conversational AI, integrated with our market-leading array of customer engagement channels, provides a comprehensive solution for enterprises looking to digitally transform their customer interactions,” said Dave Bukovinsky, executive director, product management, CSG. “By quickly resolving issues through a predictive conversational approach, CSG Conversational AI will help increase customer satisfaction and improve perception to help companies deliver a differentiated customer experience with a measurable return on investment. We look forward to our continued work with Artificial Solutions as we bring this dynamic solution to the marketplace.” (video)
Solution Functionality
- Interfaces can be built in 35 languages, running over any service or device.
- Predictive abilities can understand the voice of the customer and learn their true intent.
- Advanced integration capabilities improve the user experience by incorporating relevant knowledge from external data sources (front and back office) to construct answers.
- Real-time analytics helps to personalize the conversation, optimize the system automatically and deliver actionable data insight back to the business, while compliantly capturing the voice of the customer.
- Hybrid natural language understanding and contextual awareness fosters multi-intent understanding, implicit personalization capabilities and tailored individual responses.
“We’re delighted to team up with CSG to help deliver AI applications that will transform digital customer interactions,” said Andy Peart, chief marketing and strategy officer, Artificial Solutions. “Their experience in solving complex business challenges and delivering value through the innovative use of technology makes them the perfect partner to bring CSG Conversational AI to the marketplace.”








