
Published
- 06:00 am
Alwrite, a next-generation tech platform empowering insurance titans and intermediaries has raised Rs 10 crore in its seed funding round from a group of venture capitalist and angel investors. Alwrite is a B2B tech platform that enables insurance companies, brokers, agents, corporate agents and banks to accelerate the quote placement process to provide seamless insuring services and to offer the best insurance options to their corporate clients. Bridging the gap between insurers and intermediaries, Alwrite offers an all-in-one quote procurement and placement, underwriting and user management, along with knowledge and risk management solutions to ease the process and increase insurance penetration.
After closely observing several limitations in the quote procurement and placement process in the commercial insurance segment, the idea of Alwrite was conceptualised to do away with the tedious and time consuming manual methods and to create more sophisticated quote slips.
The Indian insurance industry has registered a compound annual growth rate (CAGR) of 10.3% during the last 10 years owing to a remarkable improvement in its operational capabilities and the robust growth of the private sector in the country. Despite constant upgradation of functioning efficiency, the commercial insurance segment still operates in an old manner where the internal insuring process is still manual. The quote placement (the step before policy issuance) process is done on excel sheets and emails and it takes an estimated 30 efforts by intermediaries and insurance companies for a single policy for a commercial entity. The entire manual process takes 14-21 days with a lot of scope for error, an uncapped PI risk and is very cost intensive. Further, Alwrite also eliminates the duplication of work caused by multiple intermediaries quoting to multiple insurance companies for a single risk. Alwrite’s sophisticated algorithms and tenanted architecture assure data security for each user.
Speaking about the seed fund raising, Mr. Aditya Dadia, Founder, Alwrite said, “Our objective was to improve the time consuming and manual backend quote procurement process for commercial insurance line with an innovative, quick tech based solution. The commercial insurance sector is the last sector to be revolutionised by fin-tech innovations that have taken the BFSI space by storm. Such a revolution has already been noticed in the retail insurance segment and has been long overdue in the commercial space. We came up with the Alwrite solution which helps in reducing the costs, turn-around times and the PI risk by digitising the entire quote procurement and placement procedure. We have plans to use the funds to further develop the product and expand the service across the country.”
The innovative concept of Alwrite and growth of the commercial insurance sector encouraged the group of angel investors to invest in the promising startup. The investors are Apurva Parekh, Executive Vice Chairman, Pidilite Group, Viral Thakker, Partner and Lead: Strategy, AI and Analytics, and M&A. World Climate lead at Deloitte India, Amit Sheth, Sanjay Bhagat, Shrenik Shah and Sumit Bohra.
Alwrite has been getting encouraging responses from insurance brokers, insurance agents, insurance corporate agents and banks that sell insurance including major Insurance companies. The platform has already partnered and is in talks with a number of leading banks and insurance organisations to ensure a quick, easy, cost-effective and hassle free insurance processing experience for their corporate customers.
- 01:00 am
- Regulation is needed to thaw the ‘Crypto Winter’ – 67% of respondents believe that for crypto currencies to thrive, more regulation is needed to ensure their long-term sustainability of digital currencies.
- Web3 services are on the horizon, with 55% predicting financial institutions will offer successful Web3 services within two to five years. But Non-Fungible Tokens (NFTs) are losing steam - a significant 85% of respondents indicate that they do not own any NFTs. Some may interpret this as a sign of waning interest or even a proclamation of the "death" of NFTs
- A sizeable 27% of respondents recognise the transformative potential of CBDCs, specifically for cross-border payments, while 25% assert that CBDCs have the capacity to completely reshape consumer payments through a more accessible and efficient payment method.
- Open Banking progress is stalling, with 38% see lack of interoperability as the main challenge preventing the full success of Open Banking. This points to a necessity for standardised protocols and frameworks, which are, sadly, still some way off.
- Automation is gaining ground – with 46% of respondents now cleaning and integrating their data, and 28% citing poor integration of their tech ecosystems as a primary challenge, automation of RegTech, AI and CX processes is under the spotlight.
Laurence Coldicott, Senior Content Director of Fintech Connect Europe, says: “As the fintech ecosystem braces for a sustained period of market unpredictability and dynamic challenges, our 2023 benchmark report illustrates that innovation is meeting resilience and creating unexplored opportunities to redefine the industry. Being at the forefront of technological advancements can help fintech and financial services players ride the next wave of digital disruption and win a competitive edge.“Respondents point to the transformative potential of AI-powered systems in driving everything from personalised customer experiences to data-driven insights that can inform strategic decision-making. The growing allure of blockchain lies in its promise to revolutionise the very foundations of financial transactions and usher in heightened transparency and disruptive business models.“At the same time, the need for streamlined, interoperable systems that can efficiently handle the complexities of regulatory reporting is placing more importance on aligning technology infrastructure with the imperatives of staying compliant. It’s often suggested that a more structured regulatory framework would provide stability and legitimacy to the crypto market, allowing it to thrive in the face of mounting challenges. As far as our respondents are concerned, crypto is in need of a shot in the arm from regulatory authorities.”
- Digital innovation and AI – how is generative AI revolutionising CX, operational efficiencies and data analytics, and what will be the impact on traditional and challenger banks?
- Embedded finance - how are more open APIs driving innovation, and what is the role of digital identity in keeping payments secure?
- Web3 – as NFTs lose steam, are institutional blockchain applications, DeFi, stablecoins, CBDCs and asset tokenisation are pushing Web3 into a new era?
- RegTech – how is the fast-changing regulatory environment is spurring fintechs to devise streamlined tech solutions to solve internal and external challenges?
- 07:00 am

Roqqett, an Open Banking payments platform, will be launching at Open Banking Expo, 18th October 2023. Roqqett’s solution, Roqqett Pay, significantly reduces the checkout time of online purchases, offers businesses instant gross settlements, with lower fees compared to card issuers, and allowing customers to pay using their banking app
Roqqett Pay is a single-click checkout solution that takes users straight through to their bank’s authenticating process on their phone without the need to upload card details. By replacing cards with the customer’s smart phone, the process creates a secure purchase journey, and avoids the fees and chargebacks associated with regular card payments.
Roqqett Pay is on average 74%* cheaper for businesses compared to major card issuers. Roqqett Pay also supports business growth and resolves cash flow challenges with instant settlements, meaning all payments are received at point of purchase. For some businesses, this means receiving payments before items are even shipped – a lifeline for businesses with smaller margins.
Roqqett launches with its first customer, FairFX, a multi-currency card provider. With the help of Roqqett, FairFX card holders can instantly top up their card using their banking app, helping them to easily manage their money, no matter where they are travelling.
Jack Mitchell, Director at FairFX, says, “When it comes to moving money, the top priorities for customers are security and speed. Roqqett offers our customers both of these. As a solution, it’s been easy to integrate to our application, with just a few lines of code. We’re both saving money, with much lower transaction fees, and enhancing our customer experience – it's a clear win-win.”
Paul Stephens, Chief Commercial Officer at Roqqett, says, “I’m thrilled to be launching our game-changing solution at Open Banking Expo this year. The current economic climate is particularly harsh on businesses, with operating costs and fees associated with selling products higher than ever before. I believe Roqqett offers all online businesses a lifeline, with lower fees and a faster and simpler customer experience that helps to convert sales.”
Roqqett was founded in 2020 with the goal of making payments frictionless and fast. In November 2022, Roqqett was acquired by the Equals Group. The acquisition provided Roqqett with tools unavailable to other Open Banking solutions, including multi-currency IBAN’s with instant gross settlement.
The Roqqett team will be bringing their new solution to the Open Banking Expo, London on October 18th and 19th 2023.
- 01:00 am
Clearpay, a leader in Buy Now, Pay Later (BNPL), has today published research revealing that BNPL use is rising across all age groups, with 30% of British adults using the service to make at least one payment over the 12 months ending August 2023. BNPL was most popular among Millennials and Gen X, at 41% and 36% respectively.
The ‘Economic Impact of Clearpay in the UK’ report, produced in conjunction with Oxford Economics, highlighted how BNPL helps mitigate financial stress as a driving factor for use. Nearly four in five (78%) of respondents said that the service helped them reduce the stress related to the cost of large purchases, while a further two-thirds (65%) said that it helped mitigate the stress associated with festive spending.
Respondents expressed that BNPL helped them reduce financial worries, especially when compared to credit card spending. 45% of BNPL customers surveyed perceived the tool to be less stressful than credit card borrowing, compared to just 10% who said they found credit cards the less stressful option of the two.
Significantly, nearly four in five (78%) respondents said they found BNPL cheaper than other credit payment options, with a similar proportion (77%) indicating that it helped them avoid high-interest credit card debt. When focusing on Clearpay customers surveyed, these values increased to 83% and 81% respectively. Ease of use and transparency was also highlighted by respondents, with 86% able to anticipate payments correctly and four in five (80%) indicating that they did not struggle to make their payments.
Rich Bayer, Clearpay’s UK Country Manager, said: “Fresh data like this is incredibly valuable for the future of the UK credit market, as it tracks the impact of the latest payment innovations. Thanks to BNPL, splitting a purchase over multiple payments no longer has to come with the stress of high-interest rates or the risk of revolving debt. It’s no surprise that it has now become a preferred everyday payment option trusted by consumers from all generations.”
The growth in popularity of BNPL payment methods in the UK comes as the use of more expensive credit options continues to stall. Bank of England data indicated that, while the proportion of UK households using BNPL has grown at pace since 2020, both credit card and overdraft usage have seen small declines over the same period.
The report also examined Clearpay’s economic impact in the UK. Since August 2022, the company was found to have contributed nearly £1 billion (£940 million) in additional sales to its UK merchants, as well as making them collective savings of £100 million through gains such as lower fraud rates, improved order processing, inventory management, lower marketing costs, lower default rates and lower returns.
Researchers also calculated that the incremental sales enabled by Clearpay had supported 11,000 jobs throughout the UK in that period, across merchant partner businesses, their supply-chains and through economic activity stimulated by employee-wage spending.
- 01:00 am

Infront, a leading provider of wealth management solutions, is now offering a web-based solution for end customers of wealth managers in Germany and Switzerland. The Wealth Portal is a modern platform that allows banks and wealth managers to provide their clients online access to investment information, evaluations, and documents anytime, anywhere. The new web-based solution can be used seamlessly across both mobile devices and desktop.
With the Wealth Portal platform, financial service providers in wealth management can offer their clients an innovative white-label platform. This allows investors to gain a simple and direct overview of their investments and portfolios, ensuring maximum transparency.
Infront's Wealth Portal is a cutting-edge tool that enables wealth managers to digitise their offerings and offer the services that today’s demanding clients expect. Investors can easily view their portfolio holdings, performance, and transaction history with just a few clicks via a user-friendly and intuitive interface, as well as accessing reports and documents through the secure messaging service. The Wealth Portal significantly enhances the user experience, enables around-the-clock access to information, and will further strengthen client loyalty to banks and wealth managers.
The Wealth Portal can be integrated with existing Infront portfolio solutions. Banks and wealth managers can manage the sharing of information, customise the interface according to their preferences and needs, and connect digitally with their clients. Financial service providers are always informed whether the information and messages are viewed by the clients, thereby revolutionising communication between the client and wealth manager while meeting regulatory requirements. The modern architecture and security design are also perfectly suited to meet the growing regulatory requirements for IT security.
Udo Kersting, General Manager of Infront Germany, emphasises, “Our new Wealth Portal modernises the user experience for investors. The platform allows institutions to bring their user interface to a highly modern and interactive standard without significant technical effort. Investors can use this new solution to view their investments easily and find out about current developments. The Wealth Portal is a crucial channel to adequately meet today's user needs – an absolute necessity given the wealth transfer to younger generations. We are convinced that this platform will strengthen the relationship between wealth managers and investors. The user-friendly integration of digital solutions also gives institutions the opportunity to reach and meet the needs of new customer groups in the future.”
- 06:00 am

Bud Financial (Bud), a leading AI-powered data intelligence platform for the financial services and banking industry, has appointed two new senior leaders to continue ramping up commercial growth and product innovation. Rachel Fairhurst joins the company as VP of Credit Risk & Client Success, and Jakub Piotrowski as VP of Product.
Rachel arrives at Bud with over 20 years of experience in senior credit roles, developing deep cross-sector knowledge of credit and risk functions in management roles at large corporations and startups alike, including Bank of America, Credit Kudos, Auden, and Equifax.
Passionate about financial inclusion, Rachel’s role at Bud will be to drive the strategy and success of Bud’s Assess solution, which enables clients in the financial services sector to supercharge their affordability and credit scoring and decisioning processes, to enhance their own client experiences and reducing risk across their portfolios This will involve working closely with Bud’s product department, headed up by Jakub Piotrowski.
Joining Bud with extensive experience as a commercially-focused product leader, including six years in the C-Suite at Meniga, a provider of digital banking solutions, Jakub will drive the expansion of Bud’s suite of AI-powered financial insights and data intelligence solutions. His role will ensure that Bud, as an AI trailblazer in the financial sector and the company behind an advanced enterprise-level AI with generative interface for banks, continues its strong momentum as a leading innovator in this space.
Bud, led by founding team Ed Maslaveckas, CEO, and George Dunning, COO, has built a stellar lineup of tech and finance experts to drive the business’s hypergrowth ambitions and enhance its AI-powered data intelligence offerings. Bud’s growth plans are powered by a strategic investment from TransUnion in 2023, following a strong Series B performance the previous year, which saw $80m raised from an impressive group including HSBC, Goldman Sachs, ANZ, Investec’s INVC fund and InnoCells.
Rachel Fairhurst, VP of Credit Risk & Client Success, said: ‘I’m very pleased to be joining a company I’ve long admired for its dedication to using open banking technology as the springboard for fairer, more accurate, and more accessible lending. One of my key priorities in this new role will be helping our clients, from niche lenders to large enterprises, to deploy and reap the full value of our solutions in their organisations. I’m also looking forward to working with the product and commercial teams to shape our strategy, carrying my passion for helping high-performing teams thrive into everything I do here.”
Jakub Piotrowski, VP of Product, said: ‘As the possibilities of AI and its applications in fintech grow, it’s a very exciting time to be joining one of the sector’s forerunners. Bud is a highly ambitious innovator, and it’s a great pleasure to be working towards some truly game-changing goals with such an impressive team. There’s huge potential to take our products further, and to do more than ever to level the financial playing field for consumers. Our upcoming launches will represent key milestones in this journey.’
- 02:00 am
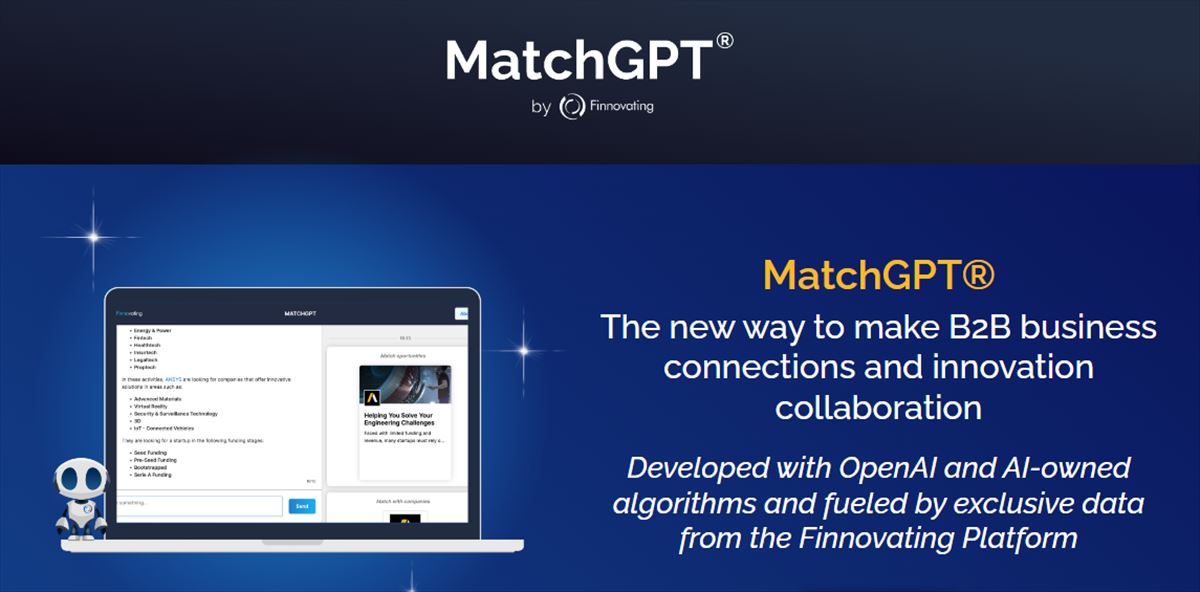
Finnovating launched MatchGPT®, the world's first Match Generative Pre-Trained Transformer focused on connecting tech companies to accelerate B2B business and collaborations in Asia. It has been developed using OpenAI and AI-owned algorithms and fuelled by exclusive data from the Finnovating Platform, an AI-Deal Matching Platform for Tech Companies.
B2B continues to gain traction in the Asian Fintech industry
In 2022, the capital raised by corporations engaged in B2B businesses in Asia amounted to 15,116 million dollars, representing a 17% of the total investment in the fintech industry worldwide. It seems that this trend is on the rise, given that in the first half of 2023, the capital raised by corporations engaged in B2B businesses in Asia amounted to 3,792 million dollars, representing a 13% of the total global investment in the fintech industry, according to data from FT Partners.
Several notable companies that have successfully secured substantial capital include Toss and GLN International in South Korea, UnionBank and Advance Tech Lending in the Philippines, Amber Group and Aspire in Singapore, Halodoc and Light Microfinance in Indonesia, and Roojai in Thailand.
This scenario highlights the rise of B2B solutions within the Fintech industry, which continues to grow in Asia, with 15,000 active Fintech companies, 7% more than the previous year, according to data from the Finnovating platform (which has 100,000 technology companies in more than 130 countries).
Of the total Fintech companies in Asia: 6,700 are specialised in B2B business and 6,100 in B2C. 1,100 Fintech are using blockchain technology and 820 the artificial intelligence (AI). 2,500 are SaaS or platform Fintech companies.
With B2B companies spending an average of 10% of their annual revenue on business development and 4% on IT solutions, falling advertising and investment ROI ratios have become a pressing concern for many companies. In addition, technological solutions for closing deals and partnerships between corporations and tech startups are increasingly crucial for the Fintech industry. Finnovating has therefore introduced MatchGPT to the Asian market, a solution designed to facilitate these connections and partnerships, ensuring the continued growth and success of businesses in the region.
A solid foundation for AI technologies
Since its inception, the Finnovating platform has collected over 20 million interactions among 100,000 tech companies, providing the perfect foundation for training cutting-edge GPT AI technologies. The result of this endeavor is MatchGPT®, a groundbreaking AI-driven solution for matching tech companies and fostering innovation.
In the end, their proposal is based on providing all the contacts and profiles of our B2B business platform in the tech industry to this big brain to be much more efficient in generating business between corporates and startups.
"If you want to know the seven most important fintech companies in Kenya, it's not only going to list them for you but also connect you with the one that interests you through the platform. MatchGPT® isn't just another product but a vertical integration with the Finnovating platform, opening a new chapter in the sector”, explains Rodrigo García de la Cruz, Finnovating's CEO and founder.
Key distinctions between MatchGPT® and ChatGPT
García de la Cruz also emphasizes the differences between MatchGPT (called also Conrad) and ChatGPT, clarifying that MatchGPT® was not developed from GPT-3.5 or GPT-4. The primary differences include:
Focus: MatchGPT® is designed for B2B matchings and interactions, catering to companies interested in technology, innovation, and business; it is also used by Governments to attract and engage with tech communities over the world. ChatGPT, however, is a generic B2C solution for a broader user base.
Objective: MatchGPT® serves as an intelligent assistant to match, connect, and facilitate transactions, effectively reducing the gap between companies worldwide. ChatGPT, on the other hand, functions primarily as a conversational chatbot without matching and transactional features.
Construction: MatchGPT® is built on proprietary behavioural and transactional data from Finnovating's platform, which boasts over 20 million interactions between 100,000 tech companies from more than 125 countries. In contrast, ChatGPT relies on more generic information extracted from the web.
Personalized Results: MatchGPT® delivers tailored results to registered users of the Finnovating Platform which intends to trigger a match and business with the right client/partner, while ChatGPT provides identical responses to all users, regardless of their background.
The possibilities with this technology are virtually limitless. A few examples might be: identify the leading 7 B2B fintech companies utilizing artificial intelligence and machine learning in France, learn how to expand your fintech business to the United Arab Emirates, discover key connections in Mexico to scale your insurtech, find the top investors seeking Series A B2E businesses in Singapore, or explore lucrative business opportunities in the US healthtech industry.
A new era of B2B GPT solutions
"We started using some of OpenAI's algorithms to see how we could create our own GPT, but oriented towards businesses, towards commerce. We realized that this huge amount of well-structured data allowed us to achieve results with great precision, far removed from what other companies achieve and which does not meet the demands of this technology" explains Pedro Uría, Finnovating Ambassador in Asia.
- 05:00 am

In a move that marks another significant milestone for Token.io, the leading account-to-account (A2A) payment infrastructure provider has announced the expansion of its direct open banking connectivity network to Sweden, Norway, Denmark and Finland, where it now offers Account Information Services (AIS) and Payment Initiation Services (PIS) services. This unlocks new opportunities for Payment Service Providers (PSPs), including leading payment platform Paysafe, which has expanded its coverage with Token.io to offer consumers and merchants a frictionless service in Denmark.
Paysafe’s A2A payment capabilities (otherwise known as Pay by Bank) allow customers to pay merchants securely and directly from their bank account using their online banking to authenticate the payment. The purchase or account top up takes place immediately and directly through the website or the gateway of the merchant.
“The expansion of TokeAn.io’s connectivity network in Scandinavia demonstrates our commitment to contributing to the evolution of the European payments landscape,” comments Todd Clyde, Chief Executive Officer of Token.io. “Not only are we committed to enabling the growth of customers like Paysafe, it’s our mission to enable Pay by Bank to become a mainstream payment method so that more merchants and consumers can benefit from better payment experiences.”
“We are excited to expand our relationship and coverage with Token.io, utilising its bank integration infrastructure to fuel our Pay by Bank solution,” said James Tiltman, VP Product, Alternative Payments, at Paysafe. "The recent boom of open banking is nothing short of a revolution, empowering consumers with seamless transactions, control over their financial data, and a plethora of innovative services.”
Open banking powered A2A payments do not require registration, or tedious, error-prone data entry, making them faster and easier than cards and 3D Secure security protocols. End-users authenticate the payment directly with their bank for a more frictionless experience that can also deliver higher success rates than cards.
“Token.io enables payment service providers (PSPs) like Paysafe to offer a pan-European A2A payment method through a single integration to our API. By leveraging open banking for A2A payments, PSPs can offer smoother payment experiences with high success rates,” comments Charles Damen, Chief Product Officer at Token.io. “With Scandinavia representing one of the most exciting markets for instant and account-to-account payments, this is a significant move that will unlock new opportunities for Token.io and our customers.”
A2A payments are the leading e-commerce payment method in Finland, and in Norway have become a key pillar of the online payments landscape. It is a similar situation in Sweden, where recent research shows over 80% of people use A2A payments on a regular basis. Elsewhere, Denmark is primed for A2A payment update, with a mobile banking penetration rate of 94%.
Token.io offers direct connectivity for open banking-enabled payments and data access to a minimum of 80% of bank accounts in each of its 20 supported markets; the highest depth of connectivity penetration per market of any provider. Building and maintaining all of its bank connections in-house enables the company to deliver optimal performance, highly responsive support and API-driven innovation.
Its expansion into Scandinavia is the latest in a series of milestones for the company. Token.io announced the launch of its Virtual Accounts product this summer, and was recently recognised with Juniper Research’s esteemed "Open Banking Innovation Platinum Award" for the second consecutive year, further solidifying its position as a global innovator in the payments space.
- 01:00 am

Today Juni, the financial platform built for digital commerce, has enabled its cross-border payments capabilities, facilitating transactions to the US and mainland China for its customers across Europe.
Businesses operate in an increasingly globalised world and data shows that the global B2B cross-border payments market is expected to total $56.1tn by 2030. Digital commerce businesses need to be able to easily source inventory, pay vendors, contractors and do intercompany transfers on an international scale.
To enable its customers to transact with overseas vendors and partners, Juni is extending its Send Money product which will now allow EEA-based companies to make Cross-Border Payments to mainland China and the US. Payments can be made directly and securely from the customer's Juni USD account.
The launch is another step to realise Juni’s vision of becoming a banking alternative for digital commerce businesses, and strengthening its core banking feature offering.
“Legacy banks often struggle to offer competitive international transfers with a smooth customer experience and it’s something we know is incredibly important to our customers," says Samir El-Sabini, CEO & Co-founder of Juni. “Our new cross-border payments feature ensures ecommerce businesses can pay vendors, suppliers and do intercompany transfers easily. This is one of many steps we’re taking to become a banking alternative for our customers.”
Businesses working with global entities can use Juni to move money between multi currency IBAN accounts in USD, GBP, EUR, NOK and SEK, with account payments FX capped at 0.5%.
“We’re really excited to bring this feature to market”, says Shelley Havemman, Senior Director of Product at Juni. “By facilitating USD to USD international transfers simply and efficiently, we strengthen our banking proposition while laying the foundation for expanding our invoice management offering to include inventory payments. We will look to add additional jurisdictions in the coming months.”
- 07:00 am

Liminal Custody Solutions (Liminal), the fastest-growing digital asset custody and wallet infrastructure provider in the APAC and MENA region, is thrilled to announce a significant rebranding initiative that underscores its commitment to innovation, excellence, and customer-centricity. This strategic move aims to reshape and elevate the brand’s identity, ushering in a new era of secure, compliant, and automated digital asset custodial solutions.
Positioning the company as a "custody and wallet expert", the rebranding signifies Liminal's expansion beyond wallet infrastructure. This exercise ensures that the brand remains at the forefront of digital asset custody, delivering enhanced services to clients and partners.
The digital asset industry is pivoting towards custody as the need for security and risk mitigation emerges as a top consideration. Liminal has recognised the necessity to expand its services to stay on top of these shifts. With its new outlook, Liminal has dedicated itself to building comprehensive layers that encompass compliance, security, and regulatory readiness.
Commenting on the new look, Mahin Gupta, Founder of Liminal, said, "We anticipate a mature, compliant, and standardized web3 ecosystem across the APAC and MENA regions, which will attract institutions to build on Web3. This rebrand aligns with our long-term vision of offering secure, compliant, and efficient custody solutions. Every aspect of our roadmap reinforces this commitment. We are now better positioned to serve this mission by offering improved services and demonstrating our dedication to a compliant, secure, and innovative web3 ecosystem."
As a part of this transformative initiative, Liminal has unveiled a vibrant new colour palette that symbolizes abundance and strength. Additionally, a more robust and visually appealing solid colour logo, paired with improved typography, is anticipated to enhance brand visibility and recall significantly. This comprehensive effort extends across the entire spectrum of the brand, encompassing the website, product user interface and user experience, marketing collateral, and all brand-related materials. Although the name "Liminal" remains unchanged, the rebrand introduces fresh design elements and vibes. The redesigned website, in particular, will adopt a more product-centric approach, enabling customers to access vital information swiftly while adhering to web3 design standards that aim to deliver a more meaningful B2B/SaaS experience. This strategic approach ensures a seamless transition for existing customers, emphasizing trust-building and continuous satisfaction.
Liminal is poised to expand its footprint in the coming year. With expectations of faster regulatory clarity in the APAC and MENA regions, the company is set to launch regulated custody operations in four regions in the next quarter, providing businesses with a secure, compliant, and regulated custody layer. This will enable businesses to focus on delivering the promises of web3 to end users.
Further sharing upcoming expansion plans of the company, Gupta added, "We are poised for expansion and engagement, with a particular focus on APAC and MENA regions. Currently, we are looking at Hong Kong, Indonesia, Abu Dhabi, Dubai, Nigeria and Taiwan. Our dedicated local teams will be delivering tailored solutions and building business relationships within these markets."








