
Published
- 09:00 am
Commenting on a near 26% year-on-year increase in IHT receipts, Laura Tommis, Trust Manager at ZEDRA, said: “HM Revenue and Customs receipts for IHT for the period April 2021 to August 2021 showed an increase of nearly 26% in comparison with the same period last year. Whilst this was not unexpected given the significant increase in property prices and the state of stock markets over the last year, it shows that planning for IHT should be considered as an important aspect in personal financial planning. As the Government needs to further increase tax receipts, there may also be future changes to some of the current IHT exemptions and allowances, such as Business Property Relief, which could mean it is best to look at planning opportunities utilising reliefs available now rather than delaying matters.”

Matt Gibson
Regional Sales Director at Gigamon
It is no surprise that the pandemic heightened the need for the financial services industry to undergo rapid and dramatic digital transformation. see more
- 06:00 am
Smonik Systems (Smonik), a data management and reconciliation software and services provider, announced that Charitable Impact recently implemented Smonik's automated data extraction process. This implementation will help them quickly and easily extract data from bank and broker statements.
Charitable Impact is Canada's donor-advised fund for everyone, where it's easy to manage all your charitable giving from one place. The implementation of Smonik will help Charitable Impact reduce manual data efforts so they can focus on assisting donors in supporting their favourite charities.
So far, more than $875 million has been donated by people using Charitable Impact's platform, and they've helped over 140,000 people across Canada give to 10,000 different charities. Donors who use Charitable Impact get a free online Impact Account, which is like a bank account for charitable giving. With an Impact Account, donors can set aside charitable dollars to give away to any registered charity, give with friends, and access support from a team of philanthropic experts. Charitable Impact also helps people donate and invest assets, such as publicly traded securities.
"We've been so impressed with Smonik. By taking away the administrative burden of manually extracting data for donor statements, we have more time to focus on what we do best: supporting people in creating the change they want to see in the world."
Before implementing Smonik's data extraction software, Charitable Impact manually extracted data from bank and brokerage monthly statements. Smonik's software now helps them automate the extraction of client data from the statements and create customized output files to integrate the extracted data with Charitable Impact's internal systems. Smonik's automated tools increase efficiency and data accuracy for Charitable Impact, resulting in measurable cost savings and a reduction in time-intensive manual processes.
"Smonik is thrilled to work with an innovative organization like Charitable Impact. They've created a new way for people to make a difference — one that flips the script and puts donors in the driver's seat of their charitable giving. Like many others, they faced cumbersome and costly data collection and extraction challenges that detracted from their core purpose: helping people engage with charity. Smonik's software was created in much the same way — we saw a void in the ability of institutional investors to process unstructured data, and we created an innovative, automated data management solution to meet their most complex needs. We're proud to now include Charitable Impact in our growing client roster," said Sethu Bijumalla, CEO at Smonik Systems.

Michael Moran
Senior Currency Strategist. at ACY
AUD, Risk FX Jump; EUR, GBP Up, JPY Dips, VIX Slumps, Stocks Up see more
- 09:00 am
DeepTarget Inc., a solution provider that utilizes data mining and business intelligence to deliver targeted engagements across digital channels for financial institutions, today announced its Digital Experience Platform and 3D StoryTeller™ were selected as finalists in the “Best Smart Banking Tech Solution” category of the Banking Tech Awards 2021, powered by FinTech Futures.
The annual award, now in its 22nd year, recognizes innovation in the use of IT in financial services worldwide. The “Best Smart Banking Tech Solution” is awarded to a banking technology solution that leverages emerging and smart technologies, such as artificial intelligence (AI), machine learning (ML), robotics and/or big data, to bring clear and measurable improvements to the organization and customer experience.
DeepTarget’s DXP allows FIs of all sizes to engage their customers throughout their connected digital ecosystem with personalized messaging that has the power to enhance data-powered cross-selling, onboarding and loyalty engagements. The DXP also includes DeepTarget’s 3D StoryTeller™, discoverable AI-powered financial stories, and built-in predictive targeting. This transformative user experience enables financial institutions to uniquely match targeted offers, financial fitness information, relevant onboarding information and relevant community messaging to consumers based on specific financial life stages.
"We are very excited about this international recognition of our innovations!” said Preetha Pulusani, CEO of DeepTarget. “Indeed, it is an honor to stand beside industry colleagues and heavyweights in the Best Smart Banking Tech Solution category. Our intense focus on digital customer engagement and marketing are empowering the digital strategies and transformation of a range of FIs of different sizes as we continue on this mission to ensure that our tech platform is accessible and usable across the board - by the very large as well as very small, community FIs.”
To see the full list of this year’s finalists and for more information about the awards, please visit Fintech Futures. The winners will be announced at this year’s ceremony in London on November 24th, 2021.
- 05:00 am
Enhanced AI and Machine Learning Functions Enable Users to Gain More from Precise Decision in Stock Selection and Investment in the Hong Kong and U.S Stock Markets |
Finetic, a Hong Kong-based intelligent stock selection and investment education platform has developed its own AI-assisted investment analysis system, which provides weekly picks of quality stocks in major global markets, including Hong Kong, China and the U.S.. The selection is made by machine-learning analysis of the most up-to-date data of about 2,500 listed companies in Hong Kong, in conjunction with technical analysis as well as review of a unique combination of the factors affecting company stock performance.
HO Man Ho, Percival, Founder and CEO of Finetic Finetic's automatic selection process helps users avoid emotional decision-making and speed up the investment research process contributing to a more profitable outcome in stock investment. Given the unpredictability of the stock market, it takes a long time for individual investors to develop and practice investment skills. Finetic is also offering educational tools and guidance that can simplify the learning curve and further increase the return on investment. Relaunch of Enhanced System and Algorithm Mr. Ho Man-ho, Percival, Founder of Finetic and an experienced investor, created a stock analysis program known as Percival Core (the "system") in 2005. The system collected, analysed and quantified basic and technical (price/volume) data of all Hong Kong stocks. The outcome of the process is a selection of "high-growth stocks", which have a strong foundation and technical characteristics (high potential in substantial price surges). The system has recently been improved with AI components allowing for analysis of even more data and correlations as well as self-learning for better investment outcomes. Apart from data analysis, the improvements allow pattern recognition (including cup and handle, double-bottom, and bottom flat patterns), giving references to users for research and execution of precise investment strategies. Percival said that thanks to the system, he has been able to maintain his capital strength for stock investment over the past 16 years, and managed to avoid the impacts of the 2008 financial crisis. In view of Percival Core's performance, from 2018 onwards, Percival started licensing the system-generated stock selection results then known as Amelia and Swing to third party distributors. In early 2021, Percival stopped licensing the results to third parties due to differences over cooperation terms. However, many users still wanted the stock selection results. In response to popular demand, Percival founded Finetic Ltd., a new intelligent stock selection platform through which the Percival Core system was relaunched into the market in May 2021. Apart from technical design and user experience enhancements, an investor education component directly supervised by Percival has been added to better facilitate users to make profits from investing in quality and profitable stocks. Finetic Chief of Staff Virginia Chan said "The Sunday Club webinars hosted by Percival on the platform are well received by our members. At the events, members can acquire stock investment basics from Percival's experience sharing and insights. Participants can also have their investment-related questions addressed." Enhanced Functions to Optimise Stock Selection Precision Finetic has further upgraded the system by introducing a "Reinforcement Learning" algorithm – creating a complex environment for the AI system to nurture its self-learning capability in the volatile stock market. Percival has also equipped Finetic with a 'supercomputer' (data science workstation) costing over US$25,000 to train the AI system to better perform stock selection. The "Reinforcement Learning" algorithm has the capability of outsmarting its designer and ideation. By receiving AI-recognised 'rewards' whenever Percival Core identifies good stocks, the AI learns from its actions. Through simulated transactions and a track record of stock picks that go through a price surge, the system begins to self-learn and discover the requisite parameters of stocks with explosive growth potential. Finetic is currently applying this advanced technology to the research of stock buy and sell points and is near the final testing phase. Once finalized, Percival Core will be able to find stocks with growth potential as well as their best buy and sell points, which will significantly increase the chance of positive investment returns. Successful deployment of this technology will also provide Finetic with more favorable conditions and advantages to develop in the B2B market. In November, Finetic will participate in Fintech Week 2021, which is co-organised by the Hong Kong Financial Services and the Treasury Bureau and InvestHK. At the exhibition, Finetic will showcase a range of products and services, along with the artificial intelligence pattern recognition technology. That will be an occasion for finance professionals and the investing public to learn more about Finetic's technologies and business development. Looking to Enter the International Market The Percival Core engine has seen continuous improvements since 2005, weathering numerous market shocks including the 2008 financial crisis and COVID-19. Finetic is proud to develop in the well regulated and organised financial sector of Hong Kong, and is eager to take its experience forward to service other international markets. "Finetic has a complete and effective stock selection system catering for the Hong Kong, China A-Share and U.S. stock markets. Its offerings include a complete list of quality stock selections, market analysis and investor tools. In the future, it is planning to further expand its offerings and global audience. Stock selection services for different countries/regions such as Taiwan, Singapore, and the United Kingdom will be launched subsequently in short succession." |

- 05:00 am
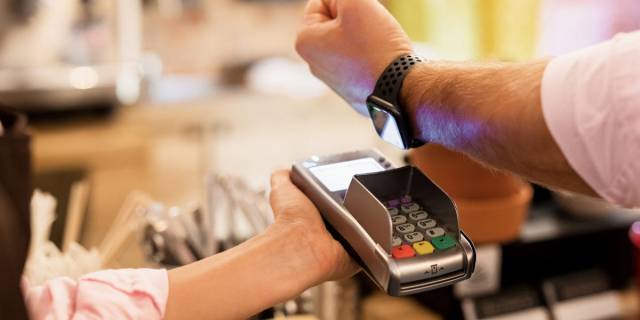
Apple introduced a number of features and tie-ups to enhance its payments offerings and spur user growth.
Apple will let users add COVID-19 vaccine cards to the Apple Wallet.
- The integration builds on Apple’s previous efforts to expand the wallet’s use cases—like supporting student IDs and insurance cards, per TechCrunch.
- The wallet could see an uptick in adoption among Apple users looking for a convenient solution to state governments mandating proof of vaccination to enter public establishments. Those new wallet users might then adopt it for payments as well.
The tech giant enabled a dynamic CVV feature for Apple Card users in iOS 15.
- Advanced Fraud Protection changes the CVV tied to the card each time it's viewed in the Wallet app or after it's auto-filled from Safari, per MacRumors. This makes it so that each transaction carries a unique CVV code, adding an extra layer of security.
- The feature can help create more trust among customers using Apple Card, especially for those who may have been wary following outages in the last few months.
Apple also forged partnerships to expand Apple Pay acceptance.
- Payment and expense management platform PayHawk now lets users add their Payhawk Visa card to Apple Pay, and fintech startup wamo integrated Apple Pay into its app so customers can make QR code payments with the mobile wallet. Cryptocurrency exchange Kraken also recently let users purchase crypto with Apple Pay.
- These tie-ups give Apple Pay users more spending touchpoints, which can help boost the wallet’s payments volume.
The big takeaway: Apple’s latest feature enhancements might push iOS users to adopt its payment offerings and help it gain a stronger foothold in the wider payments space.
Despite Apple’s leadership position in the mobile payments space, the company still has a large addressable market to tap into—less than 40% of iPhone owners use Apple Pay, based on our forecasts. And the company has an estimated 6.4 million Apple Card users out of the 116.3 million iOS users that it’s expected to reach this year, per Insider Intelligence forecasts. Building out offerings with more convenient tools and improved security can help Apple close the gap between the number of Apple-branded payment users and iPhone owners.
Go deeper: For a closer look into Apple’s payments ambitions, including growth opportunities, areas where it can improve, and how it stacks up against competitors, check out the US Mobile Payments Forecast 2021 report.
- 05:00 am
The Consumer Financial Protection Bureau (CFPB) today released its first in-depth report analyzing complaint submission patterns by U.S. Census tract. The report, “Consumer complaints throughout the credit life cycle, by demographic characteristics,” finds that the complaints from wealthier communities and communities with higher percentages of white, non-Hispanic residents were more frequently about loan origination and performing servicing, while the complaints from communities of color and lower income communities were more frequently about credit reporting, identity theft, and delinquent servicing. The findings are based on the nearly 1 million consumer complaints submitted to the CFPB between 2018 and 2020. The report uses a novel approach to classify complaints by matching the relevant consumers to census tract-level U.S. Census demographic data. Today’s report highlights the value of consumer complaint data for understanding the varied experiences of consumers using consumer financial products and services.
“Today’s report confirms that the experiences and concerns of communities, with consumer financial products and services, vary by race and wealth,” said CFPB Acting Director Dave Uejio. “Our consumer complaint data is a crucial tool for understanding varying consumer experiences, including across racial and economic divides.”
The report, the first analysis of its kind, finds that consumers from lower income and predominantly Black and Hispanic communities submitted credit reporting and delinquent servicing complaints at a higher rate per resident than consumers from higher-income and predominantly white, non-Hispanic communities, who were more likely to submit complaints related to loan origination and performing servicing. Asian American and Pacific Islander communities had higher rates of submitting credit reporting complaints than predominantly white, non-Hispanic communities; however, they also had a lower share of delinquent servicing complaints.
Some of the report’s other findings are:
- Complaints about loan originations increased by nearly 50% over the course of 2020, driven largely by mortgage complaints. This increase was centered in higher-income neighborhoods and neighborhoods with fewer people of color.
- Neighborhoods with the highest share of white, non-Hispanic consumers submit complaints about loan originations at more than twice the rate of neighborhoods with the highest share of Black consumers.
- Consumers from neighborhoods with the highest share of Black residents submit the most complaints per resident. Census tracts with the greatest share of Black residents (95% and over) have estimated complaint rates that are double the rates for tracts with the lowest share (5% and under).
- Lower income census tracts (those at or below 40% of their area’s median income) submit around 30% more complaints per resident than census tracts at around 100% of their area’s median income.
- Lower-income and communities of color are more likely to submit complaints about credit reporting, identity theft, and delinquent servicing, while higher-income and majority white, non-Hispanic communities are more likely to submit complaints about origination and performing servicing.
The findings from today’s research brief will help inform the CFPB’s work. The CFPB will continue its research into consumer complaint data as part of its larger commitment to put consumers, and their varying experiences with consumer financial products and services, at the foundation of all its work.
If you are having an issue with a consumer financial product or service, you can submit a complaint to the CFPB at www.consumerfinance.gov/complaint. We’ll work to get you a response from the company.

Matt Phillips, VP
Head of Financial Services at Diebold Nixdorf UK&I
Commenting on The Treasury’s Access to Cash Consultation closing today, Matt Phillips, VP, Head of Financial Services at Diebold Nixdorf UK&I, says: see more
- 04:00 am
- Less than half (42%) of compliance professionals in the legal sector think that 5MLD will have a net positive impact on their ability to detect and prevent financial crime
Less than half (42%) of compliance professionals in the legal sector think that the Fifth Anti-Money Laundering Directive (5MLD) will have a positive impact on their ability to detect and prevent financial crime according to new research released today by LexisNexis® Risk Solutions, the global data and analytics provider. This is 20% lower than the overall research average of 60% across other regulated industries in the UK, including real estate, banks, lenders, wealth management, accounting and gambling.
Two fifths of compliance professionals (40%) in the legal sector also believe that the regulation will have no impact in mitigating risks, and 14% believe the regulation will have the opposite to its intended effect by negatively impacting their firm’s ability to detect and prevent financial crime.
Adding to the issue, the research found that it is costing the legal sector on average 12% more to implement 5MLD than for other regulated industries, at £940,200 per law firm, compared to an average of just over £836,000 across other sectors.
Nina Kerkez, Director of UK&I Consulting at LexisNexis® Risk Solutions, comments:
“From our substantial research into 5MLD implementation programmes across the UK’s regulated industries, it’s interesting to see that the cost of implementation in the legal sector is substantially higher than the average across other sectors. It is possible that the legal sector, by its nature, deals with clients of higher risk, which in turn require more due diligence performed on them, bringing the costs of onboarding up.
“Without adopting the right tech to streamline compliance checks and create a more flexible, risk-based approach to compliance, law firms face a difficult future in keeping up with changing requirements.
The research appears to reflect the perennial conflict within firms between fee-earners, who want to onboard clients quickly, with minimal friction, and compliance teams who try to minimise the firm’s exposure to risk – an area that 5MLD and the requirement to demonstrate a risk-based approach to compliance are putting additional pressure on.
The reality is, firms can have the best of both worlds; fast, frictionless and safe onboarding, alongside robust and ongoing assessment of client risk that protects the firm from exposure to financial crime, and therefore the reputational and financial damage that could come from dealing with the wrong client.
Given the constantly shifting global political landscape and our 24-hour news cycle, there’s no wonder that 56% of firms surveyed* felt the biggest obstacle AML creates is the time it takes to collate the information. However, by automating processes using big data and smart analytics tools, legal professionals can slash the time taken to conduct checks, and reduce the possibility of error, leaving them free to focus on what’s important – keeping clients happy.








