
Published
- 06:00 am
Citi joins Mastercard’s City Possible™ network to transform the dialogue around government services and enable local governments to engage their residents more simply, inclusively, and cost effectively
Mastercard and Citi today announced a new partnership to support local residents and small businesses through greater public-private sector collaboration. Through City Possible, Mastercard’s partnership and co-creation framework for cities, the two global leaders will bring their collective resources, expertise, and integrated urban development frameworks to the City Possible network.
The partnership will initially grant City Possible network members access to “Citi Start Saving” and “City Builder by Citi” through the Mastercard City Insights Digital Marketplace. The Citi Start Saving program allows U.S. municipal and nonprofit organizations to expand access to financial services and advance economic progress in underserved and low-income communities. City Builder by Citi is a free, data-driven platform that aggregates information about community investment opportunities and includes information on 16,000+ U.S. cities, 73,000 census tracts, 485 community development projects, and 180 funds and community development entities. The new tools will provide City Possible members the ability to assess the impact of a climate or economic event to support policy and program development. The partnership will also explore ways to help city leaders develop more efficient procurement processes as well as identify avenues to support an inclusive recovery through joint disbursement solutions.
Since its inception, City Possible has facilitated a framework where members can draw on the collective expertise and resources of all stakeholders in order to replicate innovative solutions that address urban challenges. City Possible works to foster collaboration and co-creation, drive inclusive economic development, and build more resilient communities.
“Cities need to think about how to adapt to a digital world in a way that leverages technology to bring more people into the digital economy,” commented Miguel Gamino, Executive Vice President, Enterprise Partnerships and Head of Global Cities and City Possible at Mastercard. “Partners like Citi allow us to continue to expand the range of solutions we can provide to the City Possible network, which has already played an important role in helping to build more inclusive communities.”
“Technology is interconnecting cities like never before, and Citi has been focused on solutions to enhance the urban experience for citizens, government and corporations alike,” noted Andy Taylor, Managing Director, North America Public Sector Group, Citi. “Partnering with Mastercard will accelerate these endeavors and generate new thought leadership across the City Possible network.”
Today’s announcement builds on Mastercard and Citi’s longstanding partnership to provide innovative solutions to multinational corporations, financial institutions and public sector organizations across the globe. Last year, Citi also joined the Priceless Planet Coalition as a founding partner. Created by Mastercard, the coalition unite the efforts of consumers, financial institutions, merchants and cities to fight climate change through the restoration of 100 million trees over five years – together with climate science and forest restoration experts Conservation International (CI) and World Resources Institute (WRI).
- 02:00 am
· London, the South East, the North West and the East of England account for 86% of equity deals despite hosting just 55% of businesses
· Distance matters – in 82% of equity investment stakes between 2011 and 2020, the investor and company are within two hours of each other; 61% are within one hour of each other
· British Business Bank invested £943m in businesses outside of London in 2020/21
More than four in ten businesses in the UK were using external finance in 2021 but a lack of local investors means economic potential continues to be wasted across the UK’s Regions and nations. The British Business Bank’s first annual Regions and Nations Tracker, published today, reveals that regional disparities persist particularly in access to equity finance and private debt.
Core debt products including overdrafts, loans and credit cards are the most used forms of business finance in all regions and nations of the UK, but equity finance and private debt can support companies with the potential for rapid growth.
The report found London, the South East, the North West and the East of England accounted for 86% of equity investment and 69% of private debt investment despite hosting just 55% of UK businesses. By contrast, Yorkshire and the Humber accounts for just 1.5% of equity investment and 4.9% of private debt activity while hosting 7.2% of the business population. London still dominates growth finance, accounting for 62% of equity investment and 35% of private debt investment despite only having 19% of the UK’s SME population.
Investors favour short distance deals
The UK’s uneven distribution of growth finance is not driven by a lack of high growth potential business in certain areas of the country but by the presence of local investors. Investors are far more likely to invest in businesses close to their office - in 82% of equity investment stakes between 2011 and 2020, the investor and company are within two hours of each other; 61% are within one hour of each other.
The preference for short distance deals has not been impacted by the increase in remote working due to Covid-19, the data shows only a slight uptick in the mean and median travel time in 2020. In over half of investment stakes in 2020, the investor and company are within 30 minutes or less of each other, and on average within 70 minutes.
Catherine Lewis La Torre, CEO of British Business Bank, said: “The lower flows of finance in certain regions and localities reflect a population of businesses operating with fewer choices. These gaps in growth finance are undoubtedly holding back ambitious entrepreneurs and lead to wasted economic potential. This is something the British Business Bank is committed to changing.”
The British Business Bank’s commitment to address regional imbalances
The Bank remains committed to addressing regional imbalances in access to external finance. 86% of businesses supported by British Business Bank’s programmes are based outside of London.
Between 2020 and 2021, the Bank invested £943m into businesses based outside of London (exceeding its original target of £868m).
Across its Regional funds, record deployment was recorded this year principally due to a strong second half of 2020/21, providing a £357m flow of finance into regional finance markets in 2020/21.
Regional fund managers also successfully secured co-investment from other Bank-delivered programmes, such as the Future Fund, to best support local companies.
Rural business owners more pressed into injecting personal funds
Access to growth finance is particularly difficult for rural business owners who were more likely to resort to injecting personal funds into their businesses in 2020, especially in the construction sector. The report found 38% of rural construction business owners used personal funds compared to 27% of their urban counterparts.
The report argues that investors with a local presence are critical to the success of UK equity ecosystems. The data shows a clear positive correlation between equity deals per high-growth business, and the strength of the local investor base.
Uneven spread of equity finance across the UK
The report reveals a striking degree of concentration in equity activity. Taken together, the top 20 local authorities, which also include non-London hotspots such as Manchester, Bristol, Cardiff, and Newcastle upon Tyne, account for 58% of all deals since 2011.
London, Scotland and the North East of England fall within what the report calls the “self-contained” category due to the prevalence of the local investor base in equity transactions in companies within each geography. London is the most self-contained region, with 90% of equity investors in London businesses also based in London, followed by Scotland at 81% and the North East with 66%.
- 04:00 am
Compleat Software partnership with Advanced delivers ‘next-generation’ automation finance and accounting solution
Compleat Software, the Accounts Payable (AP) and Purchasing Automation software provider, today announces its partnership with Advanced, a business software and services provider.
The new partnership represents the most recent expansion of the Compleat Software partner network that will provide Advanced customers in the UK, USA, and Australia with digital invoice capture, accounts payable automation, online buying and digital procurement through Compleat Software.
Focussing primarily on services within health and care, education, public sector, enterprise, and commercial organisations, Advanced customers will be able to automate important yet time-consuming and often admin-heavy tasks that are carried out manually - reducing the risk of human error, fraud, and financial loss.
Advanced offers a tailored TruePartner program, working closely alongside external organisations, independent software vendors and resellers to support with marketing and integration services that fit specific business needs, differing from a one size fits all approach in the competitive market.
The addition of Compleat’s Advanced Spend Analytics and Supplier Category Management increases reporting to every general ledger and enhances spend visibility, allowing organisations to make better informed financial decisions and spend more time proactively driving business improvements for cost savings and success.
Speaking of the partnership, Phil Douglas, CEO at Compleat Software, said: “With Advanced’s focus on its customers' growth and success, and its ambition to ensure that it is partnering with leading solution providers, this partnership is a great fit for all involved. We are excited to see where this partnership leads, and what the future holds for our customers, our solutions, and for each other.”
Daniel Docherty, Director of Strategy at Advanced, concludes, “The integration of Compleat Software will be an excellent addition to our portfolio of solutions and the capabilities that we can deliver. At Advanced, we constantly strive to improve the range of products and services we can offer our customers and clients that will be truly transformative to their business growth and success. We’re looking forward to seeing where this partnership will take us.”
- 01:00 am
- Financial SuperApp Papara has reached ten million users, after experiencing significant growth in past year
- The milestone comes as Papara reaches its five-year anniversary in August, with an impressive 106% year-on-year growth in registered users
- The leading fintech has also increased its variety of products & services as it gears up to expand throughout into Europe
Market-leading Turkish fintech Papara today announces that it has hit the ten million customer milestone, coinciding with its fifth anniversary since being founded in August 2016. Active in a Turkish financial market that hasn’t adequately served customer needs, Papara has grown to become the largest fintech in Turkey in recent years and one of the largest in the wider region. Its mission is to level the financial playing field and leverage its digital platform to provide financial freedom across the market, and give people the chance to manage their money in the way that suits them best.
Papara is a Financial SuperApp that provides instant, free, multi-currency transfers for its users. The fintech offers consumers a one-stop shop for paying bills, trading digital currencies, and tracking their spending habits, while being able to use the Papara Card around the world to make cross-border transactions with no fees. For businesses, Papara also facilitates mass-payment, proving a corporate card that can be tailored to facilitate varying spending patterns and enables a secure check-out option for merchants. Founded in 2016, Papara has since been completely bootstrapped, with no external investment to date.
During the pandemic, Papara has grown substantially as lockdowns meant that digital banking options became more widely adopted. Papara has experienced notable growth since its inception, with a 106% year-on-year increase in registered users and active user growth of 71%. Amid such growth, Papara has continued emphasis on developing new features to enhance the customer experience such as global money transfers, spending management tools and IBAN screening. Having successfully established a leading presence within the Turkish fintech market, Papara is set to continue adding to its user base and expand into Eastern Europe.
Ahmed F. Karslı, founder and CEO of Papara comments on the achievement:
“Reaching over 10 million customers is an incredible milestone and wouldn’t have been possible without the brilliant work of our dedicated team and passionate users. We’re proud to be supporting customers of varied backgrounds to create an equal, fairer financial system. That said, this is only the beginning for us here at Papara. We have plenty of exciting initiatives and product features in the works which we’re excited to share with our users, and we look forward to welcoming our next set of ten million users to the Papara family.”
- 05:00 am

- 198 million securitised derivatives traded in Q3 2021 compared to 102 million in Q3 2020
- Most traded underlyings were DAX 40, NASDAQ 100 and OMX 30
- Last 12 months’ trading volumes increased 173% year-on-year
Spectrum Markets, the pan-European trading venue for securitised derivatives, has released its latest Quarterly Business Update, revealing continued positive momentum as it reaches its two-year anniversary.
Third-quarter trading volume grew by 94% year-on-year. 198 million securitised derivatives were traded on the exchange from July to September, compared to 102 million during the same period last year, underlining the firm’s continued strong growth.
During the quarter Spectrum also saw the one-billionth securitised derivative traded, ahead of its second anniversary on October 3rd. Looking at the first two years of trading further illustrates the progress Spectrum has made, with the number of securitised derivatives traded in October 2020 to September 2021 increasing by 173% on the same period the year before.
“Delivering another strong quarter of organic growth in which we hit the one-billion milestone is a great way to see in our second birthday, and I’m very proud of the progress we have made in those two years,” said Nicky Maan, CEO of Spectrum Markets. “We continue to make very good headway on our long-term growth plan, with the addition of Turbos on equities to our portfolio last month being a particular highlight.”
“Looking ahead, the next 12 months will be about continuing to develop the platform by further improving and extending connectivity options and trading infrastructure, as well as welcoming new members to the venue and exploring new product opportunities.”
During Q3 2021, 33.3% of individual trades took place outside of traditional hours (i.e. between 17:30 and 9:00 CET). 84.1% of this activity was on indices, 8% on currency pairs,7.7% on commodities, and 0.2% on equities, with the most traded underlyings being DAX 40 (28.6%), NASDAQ 100 (15.2%) and OMX 30 (15.1%).
- 06:00 am
- Jagath De Silva to spearhead development of Sri Lankan office
- New delivery center to take advantage of local talent to support global clients
Exactpro, a leading software testing services provider for financial market infrastructures, is pleased to announce the appointment of Jagath De Silva as CEO of its new subsidiary in Sri Lanka.
In his new role with Exactpro, Jagath De Silva will spearhead the company’s growth in Sri Lanka with the aim of making use of the leading local talent and harnessing the potential of the new market.
Jagath brings over two decades of fintech and delivery experience to Exactpro, having previously held a number of senior executive and technological engineering roles throughout his 20+ years at the Virtusa Corporation. He was a founding member of the Quality Assurance practice of Virtusa, and also held the position of Software Quality Engineering Head of Sri Lanka from 2014, where he led a team of 800+ Software Quality engineers until his most recent role as head of the Global Tech Factory, an extended engineering arm of their Global Technology Office.
Jagath De Silva sits on the advisory committees of both the Sri Lanka Association for Software Services Companies (SLASSCOM) Technology forum and Sri Lanka Institute of Information Technology (SLIIT) Business School.
De Silva’s appointment follows the announcement of Exactpro’s expansion into Sri Lanka in July, enabling Exactpro to continue strengthening support for global clients, including major exchanges and firms in the UK and US. Exactpro will also bring new capabilities to the local market, including the ability for specialised testing and engineering quality into software systems. By engaging at the grassroots level with universities and youth programmes, Exactpro aims to acquire, build and nurture world-leading talent.
Iosif Itkin, CEO and co-founder of Exactpro, said: “We’re thrilled to welcome Jagath to the expanding global Exactpro team. Jagath will be able to utilise his impressive industry and leadership experience to spearhead Exactpro’s new delivery centre in Sri Lanka to the benefit of our international clients and the local business community.”
Commenting on his appointment, Jagath De Silva, CEO, Exactpro Systems - Sri Lanka, said: “I look forward to leading Exactpro’s expansion into Sri Lanka and providing a great opportunity for over 100 local software testing specialists. As the financial sector undergoes further transformation and faces new challenges, assuring system quality has become a boardroom issue, and Exactpro is well placed to meet this challenge being the industry leader in testing services in the global financial market.”
Currently employing over 700 around the world, Exactpro is proud to have been able to attract and retain a team of experienced and talented specialists and looks forward to continuing the delivery of its services to clients out of both the existing and new locations.
- 02:00 am
Bloomberg announced today that the Council of Europe Development Bank (CEB) has adopted its Multi-Asset Risk System, MARS Front Office, a robust and streamlined risk management system that enables the bank to assess the impact of trading activity on the risk profile of its books.
The CEB is a multilateral development bank that provides financing and technical expertise for projects that promote social cohesion and strengthen social integration in Europe. In addition to benefitting from the MARS Front Office consolidated pricing and risk analytics, including pre-trade and daily post-trade valuations, Greeks and scenario analysis, the CEB has also opted to utilise “PnL Explain” reports, a new functionality that helps firms understand fluctuations in market value and the contributions of the various underlying market factors.
“Streamlining our valuation and risk processes with MARS Front Office has helped us improve our risk monitoring. As a result, we’ve also been able to increase efficiencies, which allows us to better focus our efforts and resources,” said Grégoire Demoulin, Financial Risks Division at the Council of Europe Development Bank.
“To remain resilient, financial firms need timely, transparent and comprehensive risk analytics, as well as efficient coordination between front office and risk management teams", said Leila Sadiq, Global Head of Front Office Risk at Bloomberg. “MARS Front Office provides firms with the ability to immediately understand the impact of a trade on their risk profile, and thus to make better-informed decisions more systematically, reduce risks and improve their operations.”
The CEB is a long-standing customer of Bloomberg and also uses BVAL Derivatives, a pricing service that provides independent valuation for a wide range of derivatives from vanilla to complex, and MARS XVA for counterparty risk management.
Bloomberg’s suite of MARS risk solutions, which are delivered on the Bloomberg Terminal and via APIs, provide risk analytics for cash and derivatives securities. The suite helps traders, portfolio and risk managers manage front office risk, market risk, XVA counterparty risk, credit risk, hedge accounting, as well as collateral and SIMM requirements – all by using a common pricing and data library, providing consistency from front to back. MARS Front Office supports firms with intraday valuation and on-demand risk analytics, advanced scenario and stress test capabilities as well projected cashflows and “PnL Explain” reports. MARS Valuations provides credible and complete end-of-day market valuations for enterprise usage and reporting.

Mark Patrick
Global Head of Payments at CellPoint Digital
The pandemic has irreversibly changed the retail customer journey, with see more
- 07:00 am
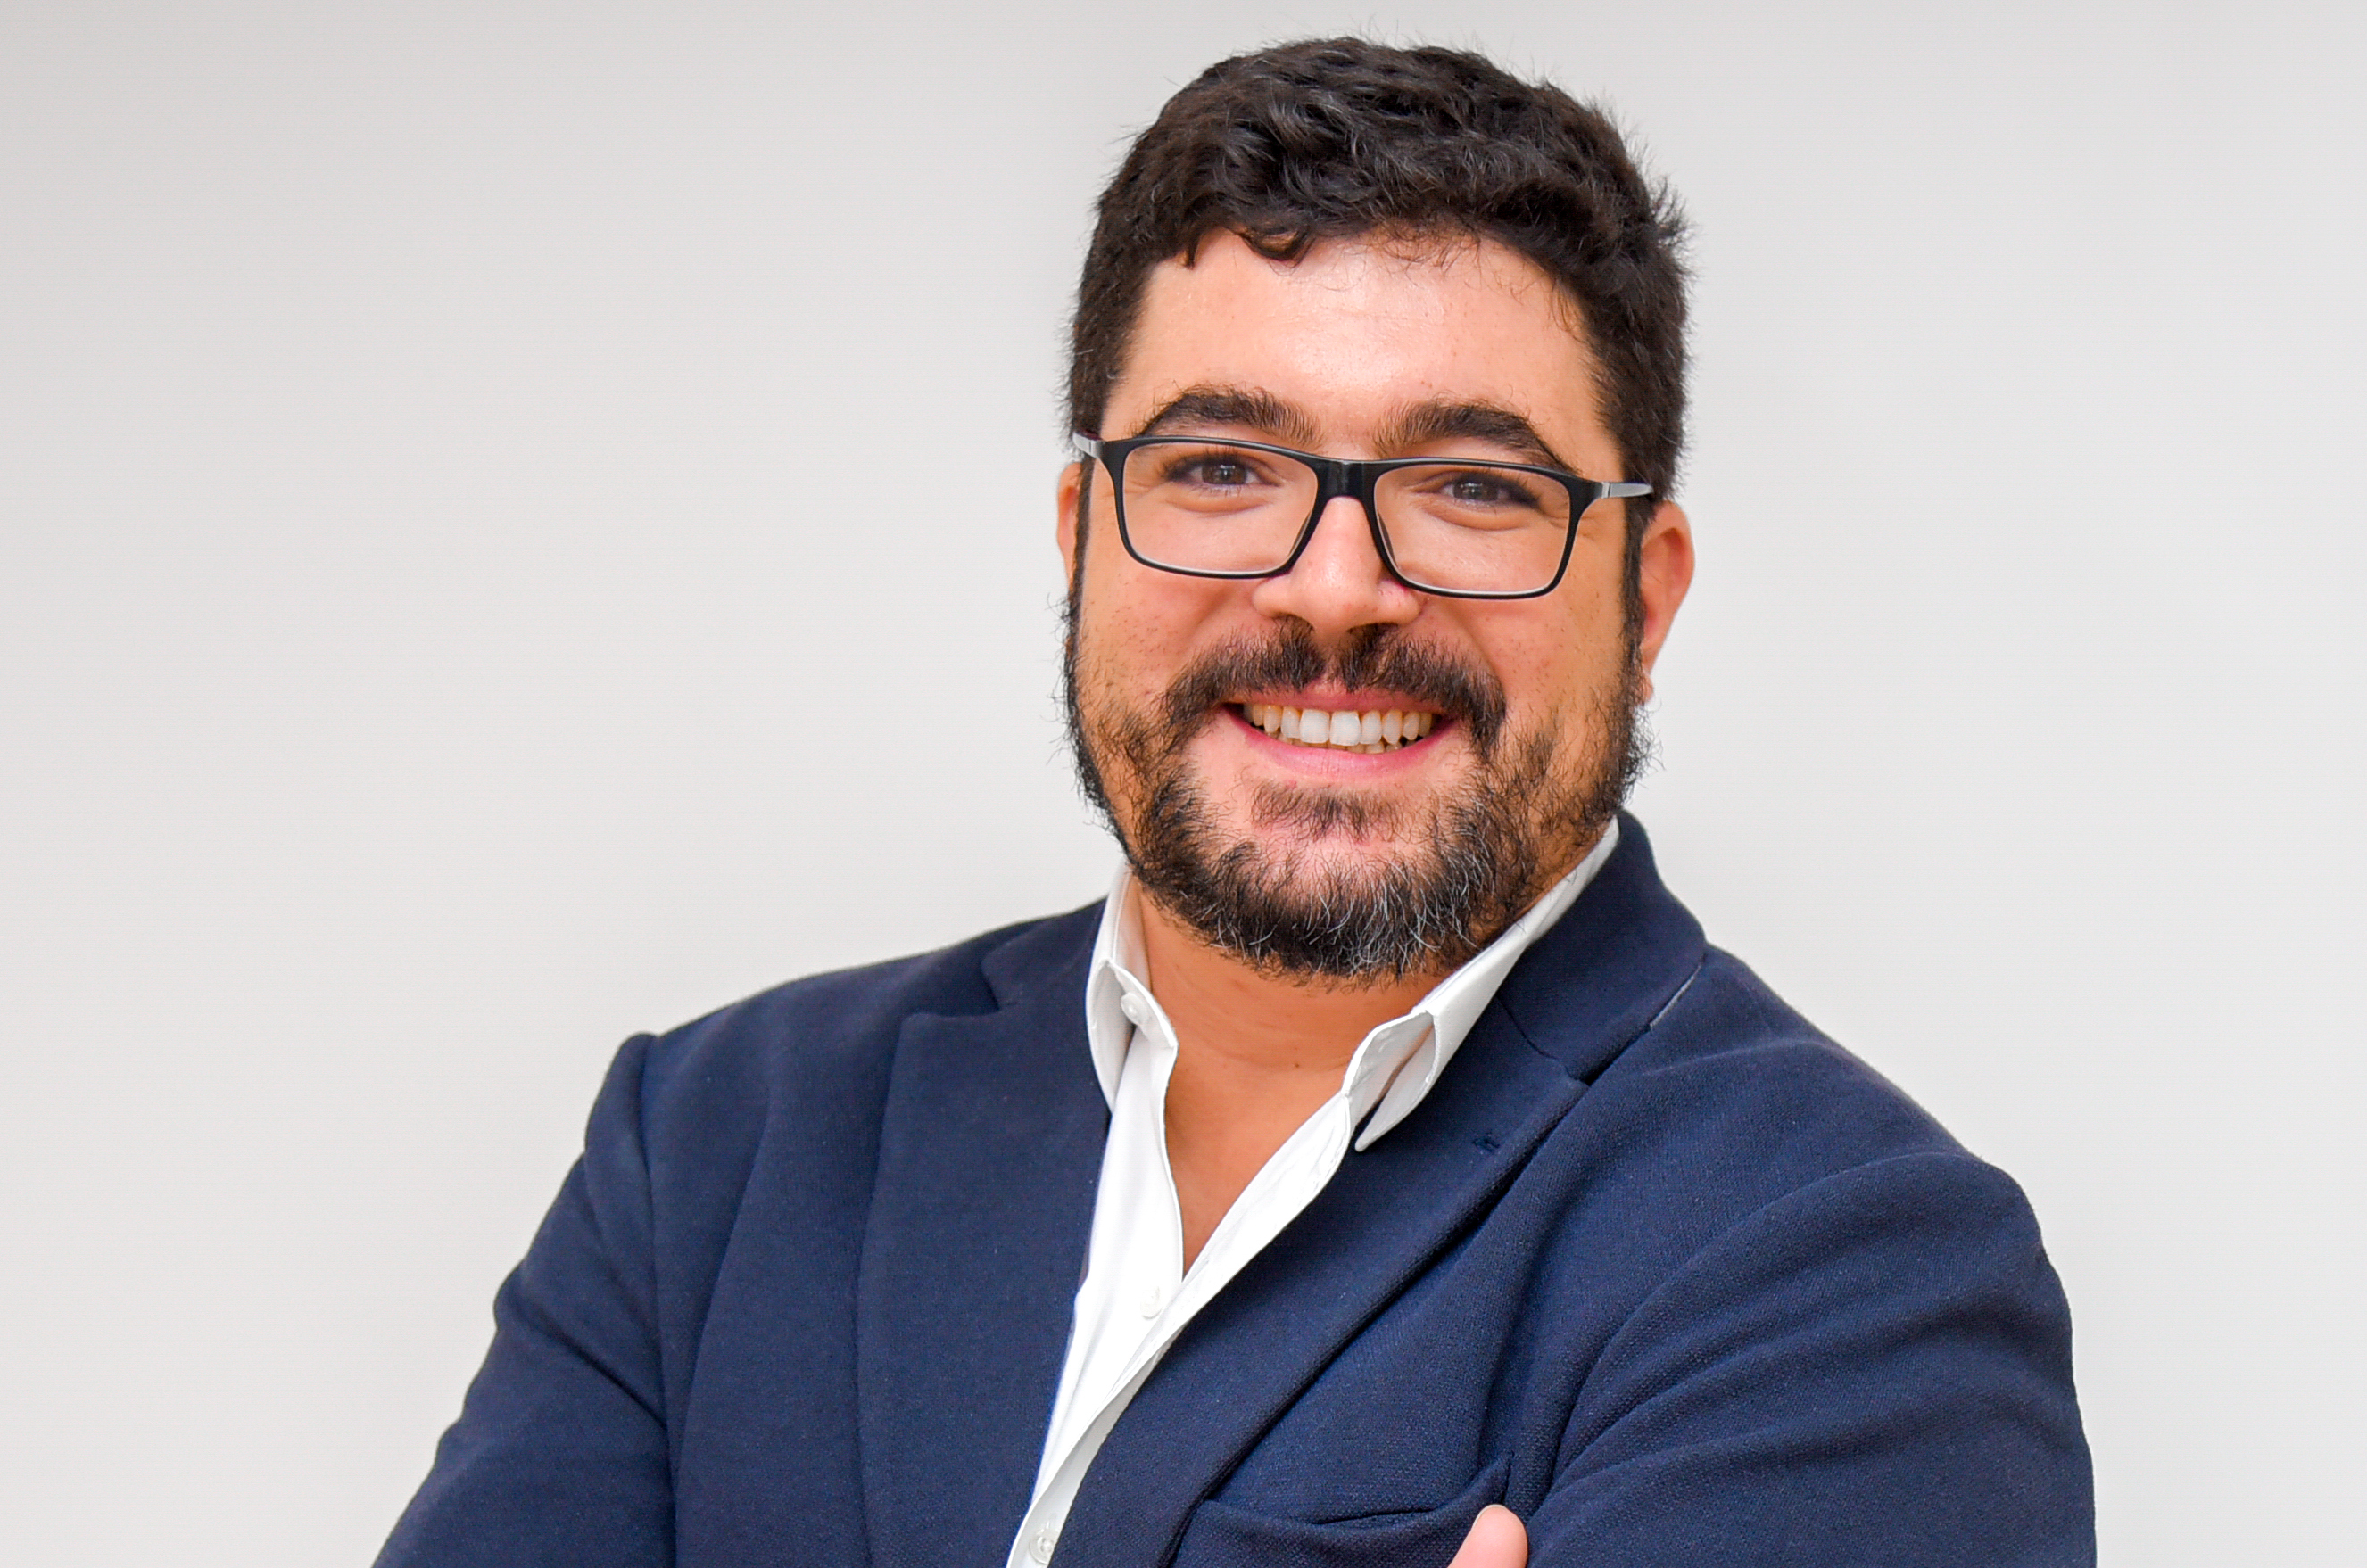
Nutanix has announced the appointment of Yacine Kherbane to Vice President, EMEA Marketing. The promotion is effective immediately and he will be based in Paris.
In his new role, Kherbane will manage a high performing team across EMEA that has been integral to Nutanix’s success of driving a record pipeline, new business growth and increased partner engagement.
“The hybrid multicloud era for enterprises is accelerating, making it an exciting time to be appointed to lead marketing activities in EMEA to help speed up business growth across the region,” commented Yacine Kherbane. “I am looking forward to working closely with my talented team to devise and deploy a comprehensive marketing strategy that will drive customer adoption and migration, to underpin the next phase of growth.”
With 23 years’ experience in IT, Yacine Kherbane is a recognised marketing leader who also enjoys a solid reputation internally since joining Nutanix more than seven years ago. He first joined Nutanix in September 2014 as Marketing Manager for Southern Europe & Middle East, Israel & Turkey.
Ben Gibson, Chief Marketing Officer, Nutanix, said: “Yacine has established himself as an outstanding collaborator across the global marketing organisation. He is ideally qualified to further drive our momentum to help communicate Nutanix’s value in helping companies modernise their infrastructure and build out a hybrid multicloud environment. Yacine’s appointment is testament to his commitment and accomplishments achieved to date within our organisation.”
- 02:00 am
Veriff, a global identity verification provider, today announced that it will be launching a tech hub for its product and engineering teams in Barcelona. This comes on the heels of its New York City office opening in late 2019 and building a stronger presence in London earlier this year as the company expands globally, now with over 300 employees from 35 different nationalities. Well on its way to reaching its goal of 500 employees by Q2 next year, Veriff will tap into the impressive talent pool in Barcelona and will be an active part of the burgeoning tech ecosystem in the city.
Barcelona offers a dynamic startup ecosystem and has attracted more private equity investment in recent years than Madrid, Dublin and Amsterdam, making it the fifth-biggest source of venture capital in Europe. Veriff’s VP of Product Duncan Steblyna will lead the hub and will be joined by several team members from Veriff’s Estonia headquarters who will serve as ambassadors of the company culture.
Veriff is looking for a number of new hires to join the team with the goal of reaching 50 employees by early next year, including DevOps engineers, machine learning engineers, senior information security engineers, senior software engineers, a head of design, and a senior product manager.
“We’re thrilled to call Barcelona our next home, not only because it’s a strong European tech hub, but also because it has some of the best product and engineering talent in the world,” said Steblyna. “This is another critical step in our global expansion as we protect customers around the world from identity fraud, and I look forward to building another strong team in our new Veriff location.”








